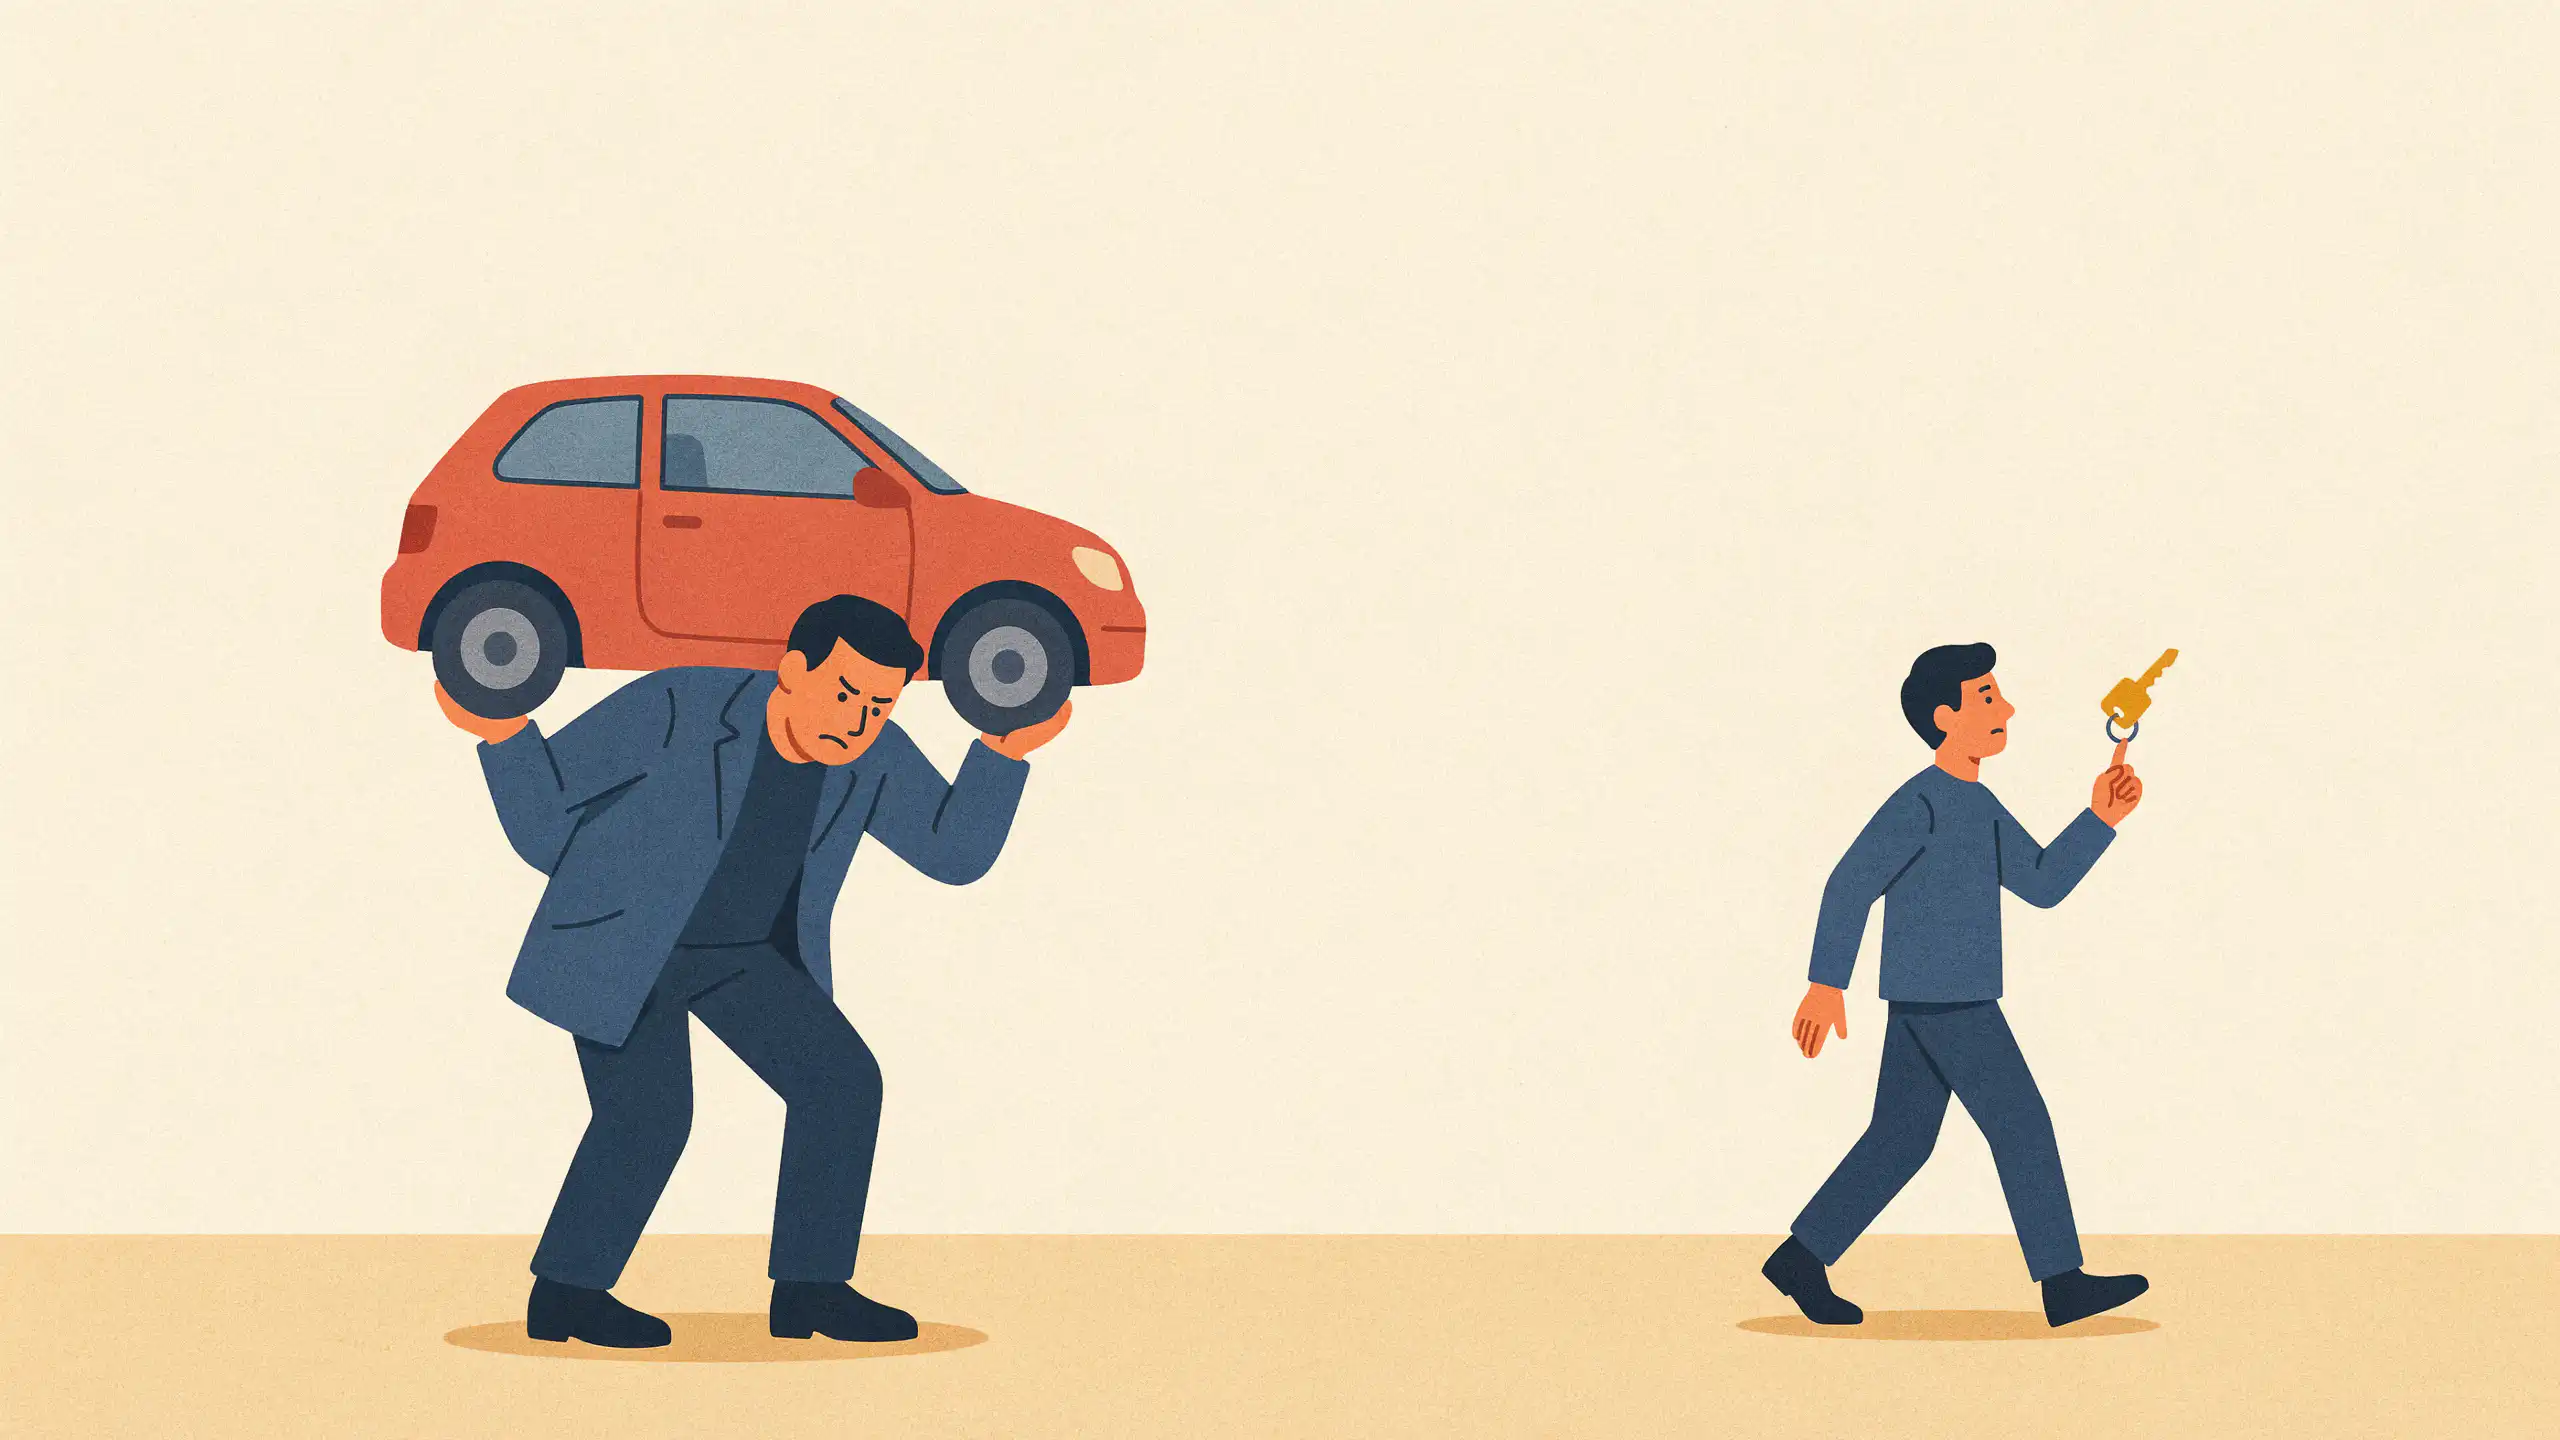

Cosigning a loan makes the whole debt yours. The lender can collect from you, and other lenders can count it as your debt when you borrow, even if the borrower never misses a payment. Before you sign for a child, partner, or friend, make sure you could cover every payment yourself without strain.
Most lenders must give you the federal Notice to Cosigner, which says that if the borrower doesn’t pay, “you will have to.”
Depending on your state, the lender can come straight to you without trying the borrower first. It can sue you or garnish your wages to collect.
Because the lender can report the loan as your debt, the borrower’s late payments can show up on your credit report and lower your score.
Say you cosigned your daughter’s $450-a-month car loan six months ago and now want a mortgage. Under Fannie Mae‘s rules, the mortgage lender can drop that payment from your monthly debts only with 12 months of her canceled checks or bank statements proving on-time payments. She has six. Her car payment counts as yours and shrinks the mortgage you qualify for, even though she has never been late.
So picture the borrower stopping payments tomorrow. If you couldn’t take over every remaining payment without draining your savings or falling behind on your own bills, say no to the loan and help another way.
- Instead of backing the whole loan, give a smaller sum outright, toward a down payment or first month’s rent.
- Fund the deposit on a secured credit card in their name. On-time payments build a credit history of their own if the issuer reports to all three credit bureaus.
- For an apartment, check whether the landlord accepts a guarantor company such as Insurent, which backs the lease for a one-time fee, usually 70% to 90% of a month’s rent on a one-year lease.
If you’ve already signed, ask the lender for online access or monthly statements, and ask it to agree in writing to warn you of any missed payment. Check your credit reports monthly. On a private student loan, ask the loan servicer about cosigner release, which drops you from the loan once the borrower makes a set number of on-time payments in a row and qualifies on their own. Have them apply the moment they’re eligible.
If you wouldn’t take on this debt for yourself, don’t take it on for someone else.

Editorial & Advertiser Disclosure: The editorial content on this page is not provided, commissioned, reviewed, approved, or otherwise endorsed by any advertiser. Opinions expressed here are ours alone, not those of any advertiser. The offers that appear on this site are from companies that compensate us. That compensation may influence which products we cover and where and how they appear on a page – including the order in which they appear – but it does not influence our evaluations, ratings, or opinions. We do not include every company or offer available in the marketplace.
Related: