
If your mortgage interest, property taxes, and charitable gifts land just under the standard deduction, most of that spending doesn’t cut your tax. Bunch two years of gifts and other flexible deductions into one year and itemize, then take the standard deduction the next. Run the numbers both ways first. The bigger your gifts, the more bunching adds.
On the standard deduction, mortgage interest and property taxes count for nothing, and since 2026 a married couple filing jointly can deduct only $2,000 of cash gifts a year, or $1,000 for other filers. If that couple gives $10,000, $8,000 of it goes undeducted.
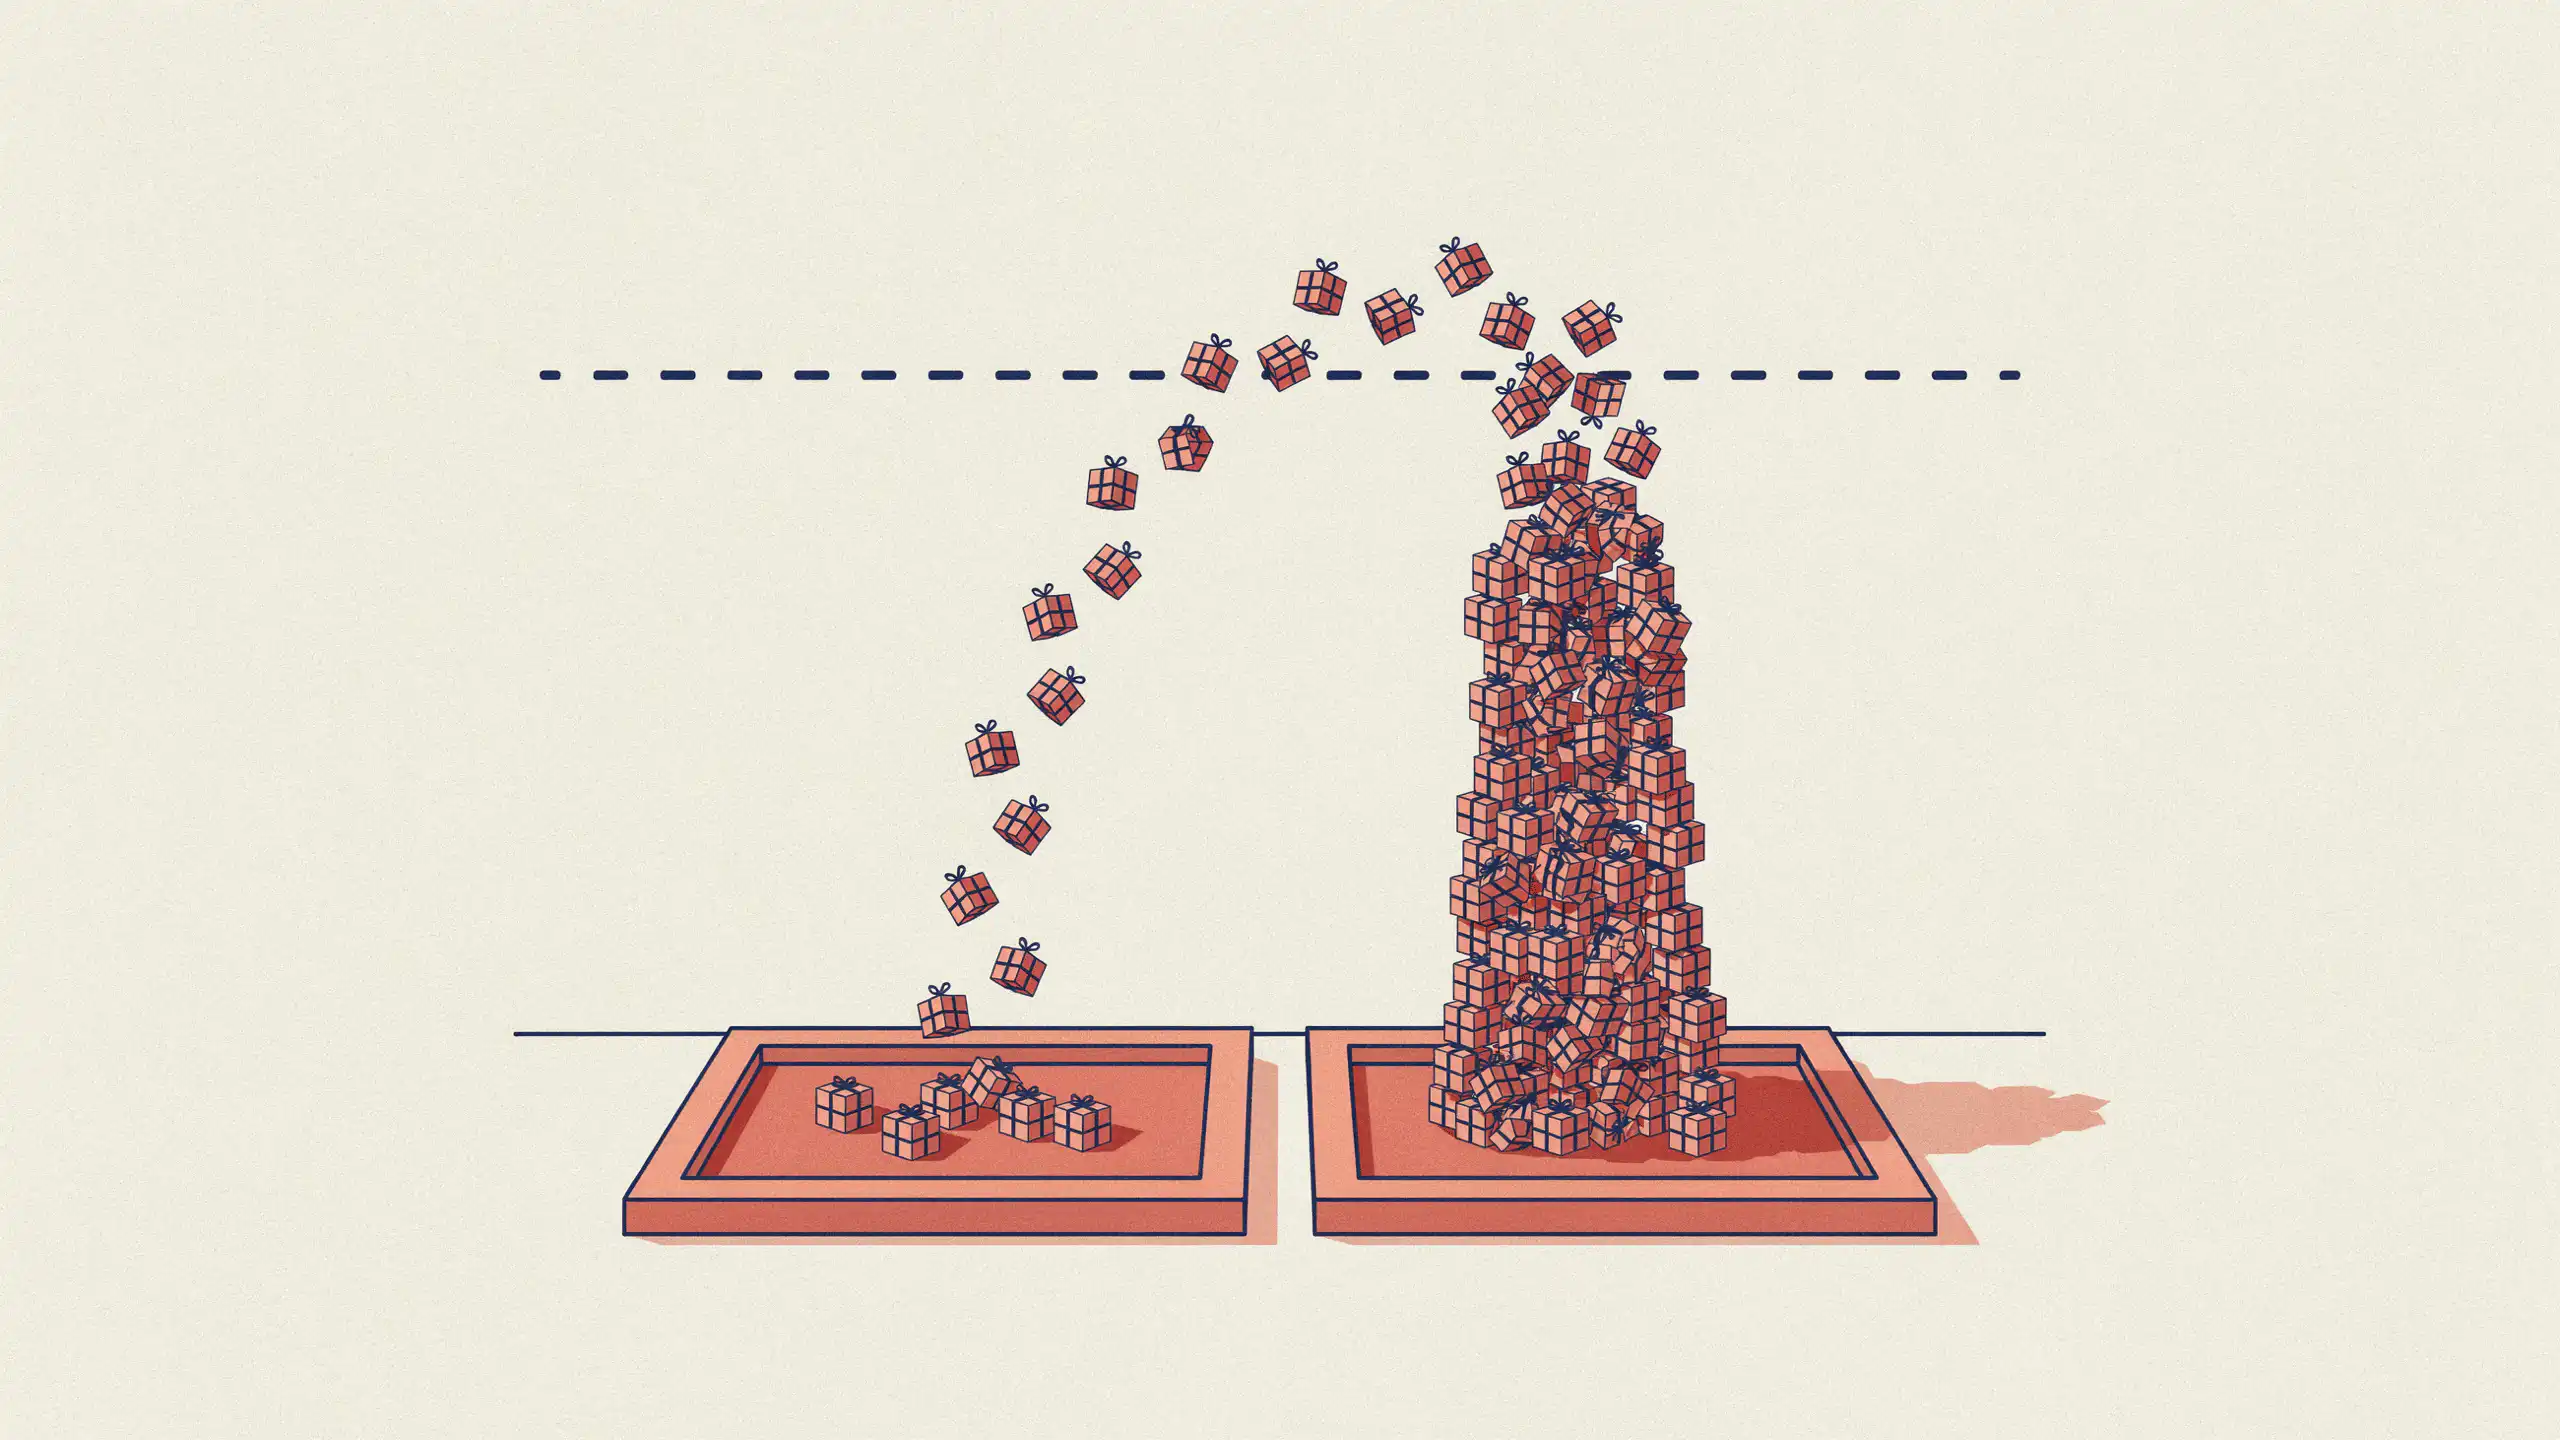
Bunching fixes this with timing. Deductions count in the year you pay them, and gifts in particular can go out whenever you choose. Pay two years’ worth in one calendar year, and that year your itemized total can top the standard deduction. The next year, take the standard deduction as usual.
Suppose that couple’s mortgage interest, property taxes, and $10,000 of gifts come to $2,000 less than the standard deduction, and their adjusted gross income is $150,000. Since 2026, the first $750 of their gifts, 0.5% of that income, isn’t deductible when they itemize. Giving $20,000 in one year puts that year’s itemized total $7,250 over the standard deduction, and the following year they take the standard deduction. Compared with deducting $2,000 of gifts each year, they deduct $3,250 more over the two years.
Gifts are the easiest deduction to move. Fund a donor-advised fund with two years of gifts and you deduct them that year, then recommend grants to your charities on their usual schedule. Two other deductions can also move into the bunching year:
- A property tax installment your county has already billed, paid by December 31, as long as your state and local taxes stay under the federal cap
- Elective medical or dental work, since only medical costs above 7.5% of adjusted gross income count
In the off year, send any new gifts straight to charities. Money put into a donor-advised fund doesn’t count toward the capped gift deduction, so a contribution that year earns no deduction at all.
Each fall, before your year-end gifts go out, total this year’s and next year’s deductions both ways, counting the capped gift deduction in each standard year. If one bunched year plus one standard year deducts more than two standard years, bunch.

Editorial & Advertiser Disclosure: The editorial content on this page is not provided, commissioned, reviewed, approved, or otherwise endorsed by any advertiser. Opinions expressed here are ours alone, not those of any advertiser. The offers that appear on this site are from companies that compensate us. That compensation may influence which products we cover and where and how they appear on a page – including the order in which they appear – but it does not influence our evaluations, ratings, or opinions. We do not include every company or offer available in the marketplace.
Related: