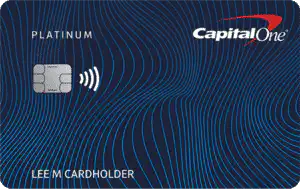
Capital One Platinum Secured Credit Card
- Best for: Rebuilding credit, or starting it, on a small refundable deposit
- What Sets It Apart: A $49 or $99 deposit can open a $200 credit line; considered for a higher line in as little as six months
- Cost: $0 annual fee; $49, $99, or $200 refundable deposit; 29.24% variable APR
- Features: Starting credit line of at least $200; extra deposit raises it up to $1,000; reports to all three credit bureaus; no foreign transaction fees
- Pros: Low deposit options; no annual fee; deposit returned when you upgrade to the unsecured Platinum
- Cons: No rewards; high interest on carried balances; no stated timeline for the upgrade

Open the Capital One Platinum Secured if you’re rebuilding credit or starting from scratch and want a $200 credit line for as little as $49 down. It has no annual fee but pays no rewards, so first see if you’re pre-approved for Discover’s secured card, which takes the same deposits and pays cash back.
Capital One sets your deposit at $49, $99, or $200 based on your credit history, and checking your eligibility doesn’t affect your credit score. The card is for people who can’t get an unsecured card yet, so if that check offers you the unsecured Capital One Platinum, take it and skip the deposit.
Key Features
- Starting credit line of at least $200, whichever deposit you pay
- Extra deposit within 35 days of approval, before you activate the card, raises the starting line up to $1,000
- $0 annual fee and a 29.24% variable APR, the rate charged on balances you carry
- A higher credit line possible after as few as six months, without another deposit
- Account reported to all three credit bureaus
Pros
- Deposits as low as $49, so building credit ties up little cash
- No foreign transaction, replacement card, or authorized user fees
- Deposit returned as a statement credit when Capital One upgrades you to the unsecured Platinum
- Deposit can be paid in installments over 35 days
Cons
- No rewards, before or after the upgrade
- High interest on any balance you don’t pay in full by the due date
- No stated timeline for the upgrade
- Deposit accepted only by electronic transfer from a bank account
- Approval still depends on your income and existing debt, though no credit score is required
It suits people rebuilding after late payments or a bankruptcy, or starting with no credit history, who would rather keep the deposit small than earn rewards. Discover’s secured card pays cash back on the same three deposit amounts, and if your credit is fair rather than damaged, Capital One’s Quicksilver Secured earns 1.5% cash back on a $200 deposit.

Editorial & Advertiser Disclosure: The editorial content on this page is not provided, commissioned, reviewed, approved, or otherwise endorsed by any advertiser. Opinions expressed here are ours alone, not those of any advertiser. The offers that appear on this site are from companies that compensate us. That compensation may influence which products we cover and where and how they appear on a page – including the order in which they appear – but it does not influence our evaluations, ratings, or opinions. We do not include every company or offer available in the marketplace.
Related: