
If your work health insurance is ending, get a quote from the government’s health insurance Marketplace before you sign up for COBRA to keep yours. COBRA charges the whole premium, including your employer’s share, while Marketplace tax credits are based on your household income for the year. Decide within 60 days of losing coverage, before the Marketplace window closes.
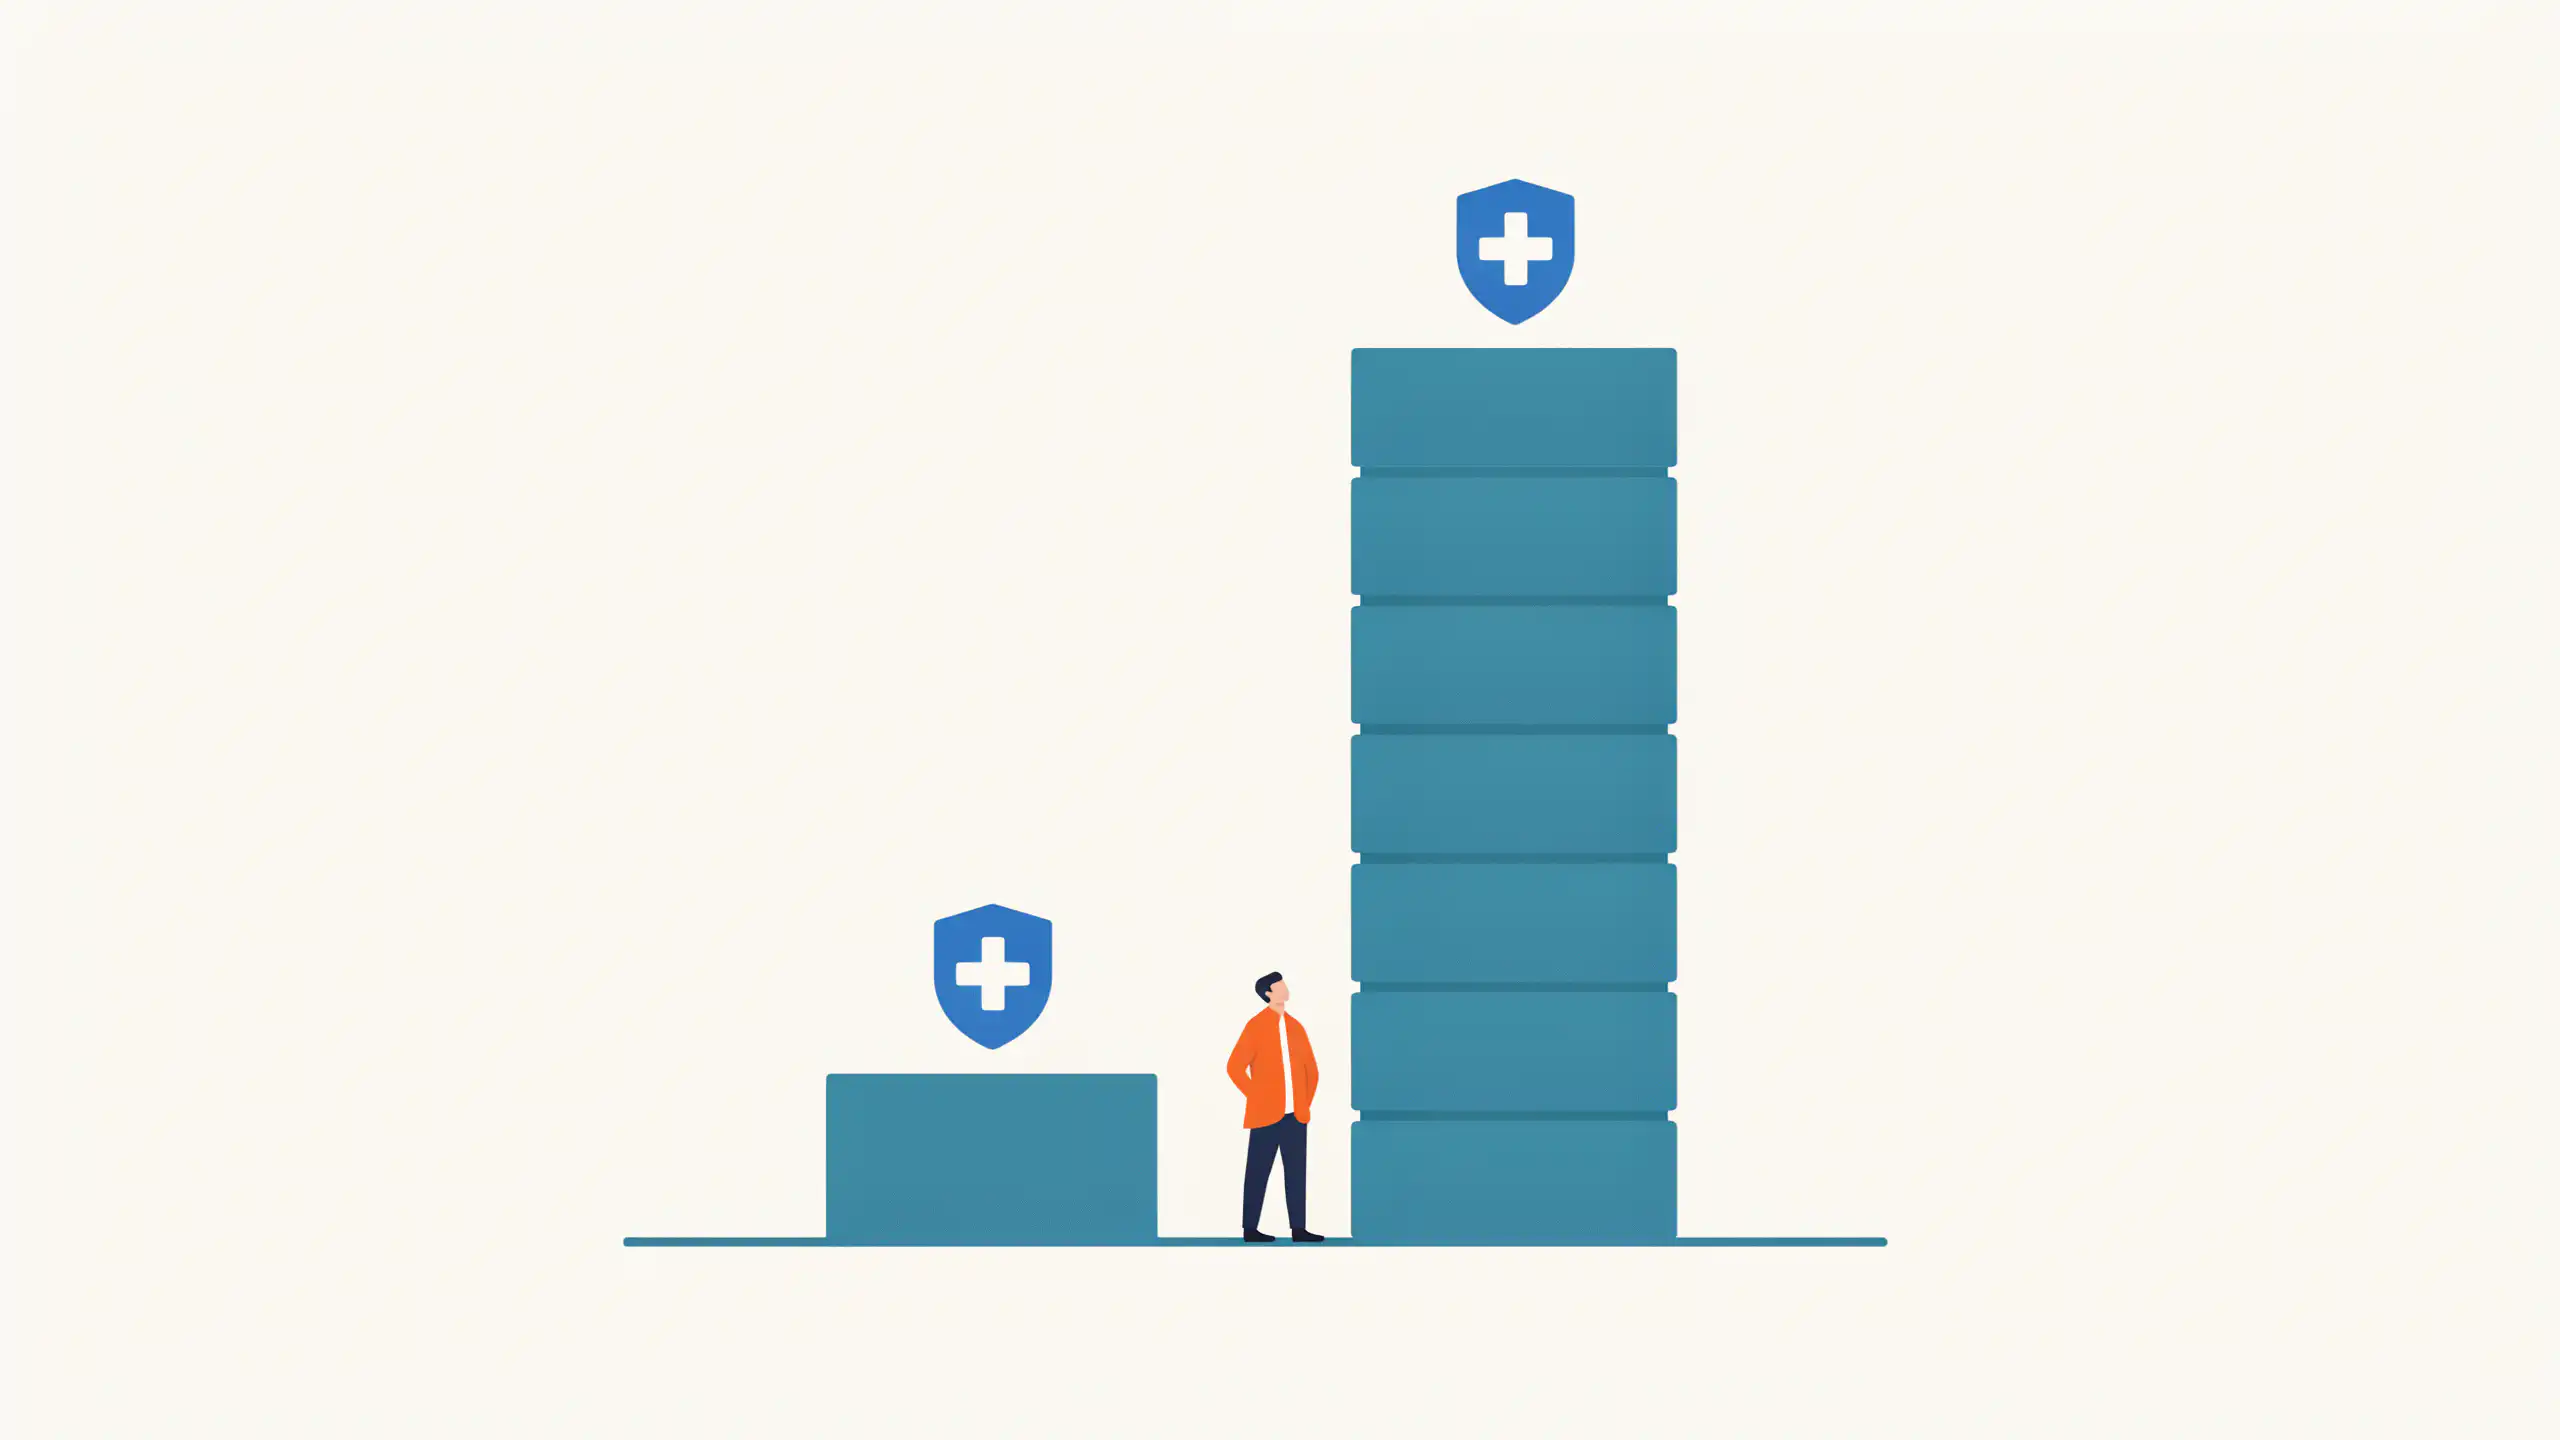
COBRA feels like the safe choice because you keep the same plan and doctors. What changes is the price. Employers pay most of the premium for active workers, so if yours covered 85%, COBRA costs nearly seven times what you paid for it at work.
Marketplace premium tax credits are based on your household income for the calendar year, not on whether you have a job. After a June layoff, your income estimate counts six months of pay plus any severance and unemployment benefits. Being offered COBRA doesn’t disqualify you from the credit. Only enrolling in it does.
Price both before you sign anything, and subtract any COBRA subsidy your severance package includes. COBRA can wait while you shop, since its coverage is retroactive once you sign up and pay. HealthCare.gov’s plan preview shows Marketplace prices after the credit once you enter your ZIP code, household, and income estimate. If your state runs its own Marketplace, use its site instead. Check deductibles, out-of-pocket maximums, and whether your doctors are in network.
The Marketplace sets your real deadline. Whether you quit, were laid off, retired early, or lost family coverage through a spouse’s job, you have 60 days after the work coverage ends to pick a plan. Pick one up to 60 days before that coverage ends, and it starts the first of the following month. You can switch even after signing up for COBRA, but only inside that window, unless COBRA runs out or your former employer stops subsidizing it. Dropping COBRA or stopping payments won’t reopen the Marketplace before open enrollment.
COBRA wins in two cases. If you’ve already paid most of this year’s deductible or out-of-pocket maximum, COBRA keeps that progress because it’s the same plan, while a new Marketplace plan starts you at zero. And if you’re mid-treatment with doctors no local Marketplace plan includes, keep COBRA and price the Marketplace again at open enrollment, when anyone can switch.
Once you’re on a Marketplace plan, report a new job or a raise right away. Otherwise you’ll repay the extra credit when you file your taxes.

Editorial & Advertiser Disclosure: The editorial content on this page is not provided, commissioned, reviewed, approved, or otherwise endorsed by any advertiser. Opinions expressed here are ours alone, not those of any advertiser. The offers that appear on this site are from companies that compensate us. That compensation may influence which products we cover and where and how they appear on a page – including the order in which they appear – but it does not influence our evaluations, ratings, or opinions. We do not include every company or offer available in the marketplace.
Related: