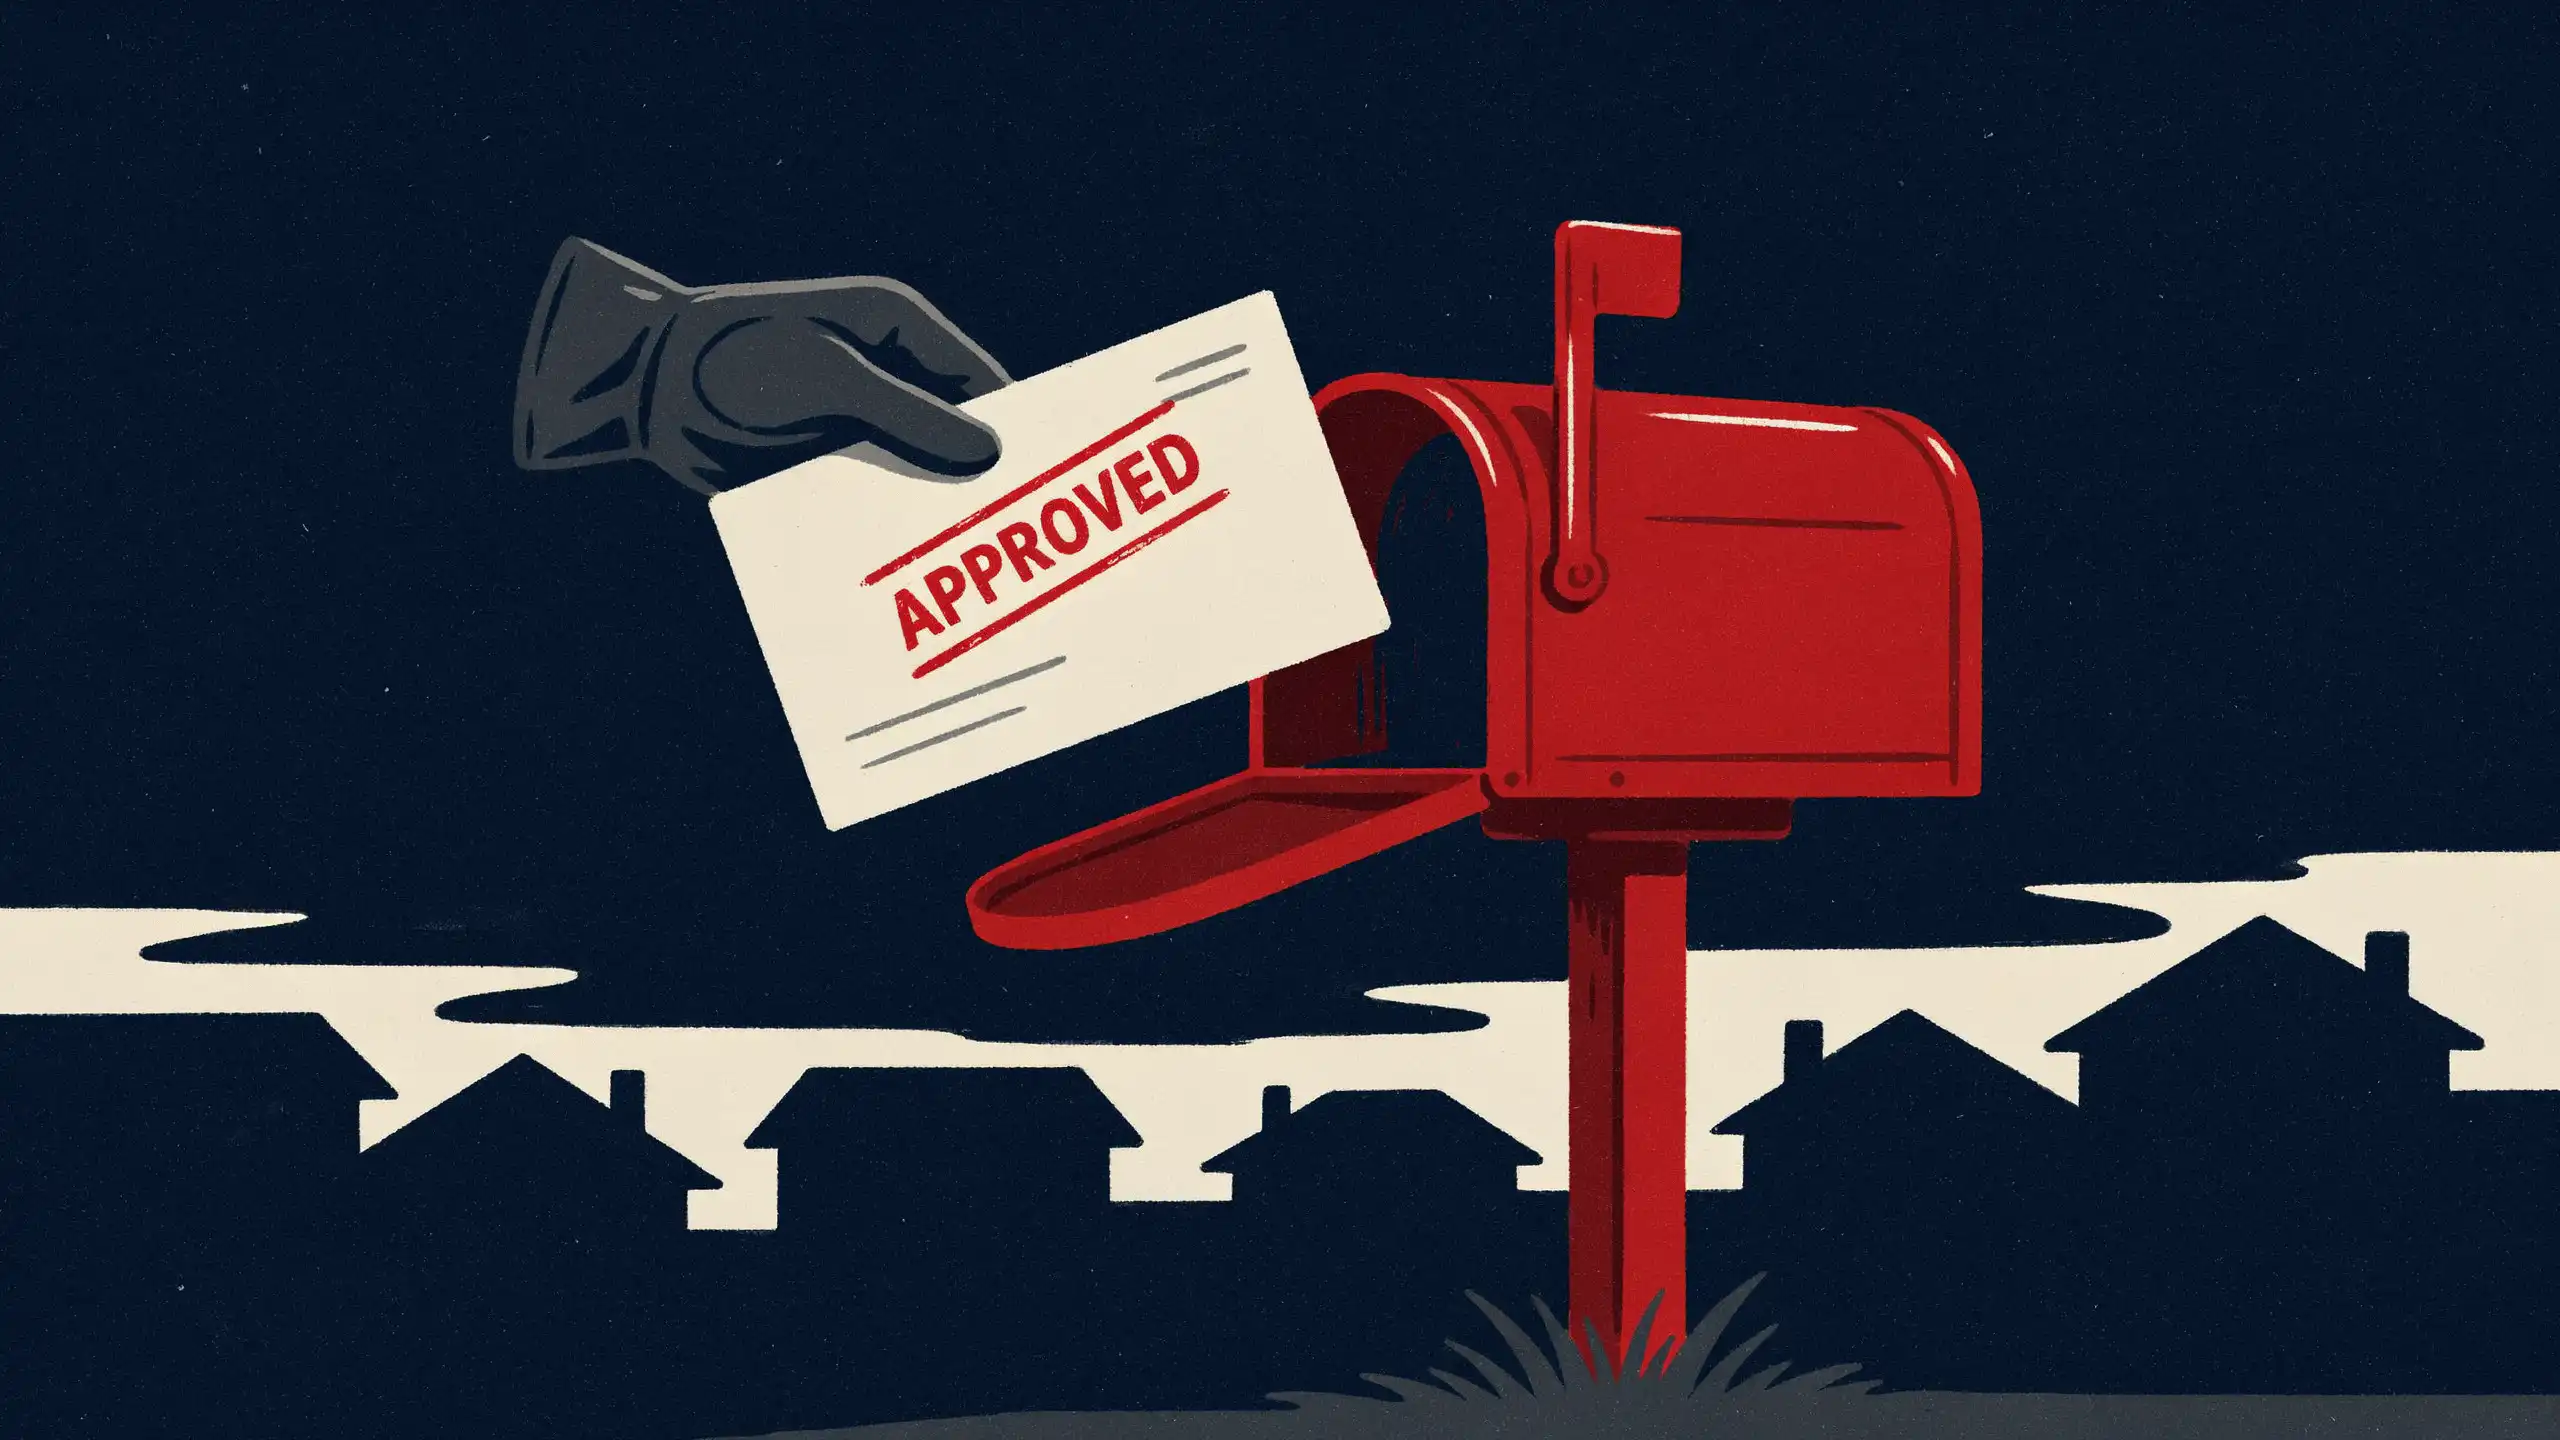

To anyone who pulls it from your mailbox, a preapproved credit card offer announces your name, your address, and that a lender has already picked you. Opt out of these prescreened offers at OptOutPrescreen.com or 1-888-5-OPT-OUT, the free service the credit bureaus run, and the offers drawn from your credit report stop coming.
An unlocked curbside box puts that envelope within reach of anyone walking past. Experian warns that a thief could pair a stolen offer with your Social Security number and birth date from a separate theft and apply for credit in your name.
These offers start with your credit report. A lender or insurer sets its criteria, such as a credit score range in a given area, and the credit bureaus supply a list of everyone whose report fits. A credit freeze won’t take you off those lists. Equifax and TransUnion both say companies can still prescreen a frozen report, so the offers keep coming.
Type OptOutPrescreen.com into your browser yourself, or call 1-888-5-OPT-OUT (1-888-567-8688). The site asks for your Social Security number and birth date, so reach it directly instead of through a link in an email, a text, or an ad. Experian says those two are optional but help your request go through, and the FTC adds that they stay confidential and can’t be used for anything else.
Then pick how long the opt-out lasts. The five-year opt-out finishes online or on the call. A permanent opt-out starts the same way, then needs the Permanent Opt-Out Election form signed and mailed back. Processing takes up to five days, but the FTC says it can be several weeks before the offers stop. Shred any that arrive in the meantime, and keep shredding offers from banks you already use, which the opt-out doesn’t cover.
Experian says opting out won’t hurt your credit scores. What you give up is offers you might have wanted. The FTC notes they can show you what’s available and help you compare costs, sometimes with better terms than you’d get applying on your own.
Because the same site or phone line opts you back in whenever you want offers again, the permanent form costs you nothing but a stamp. If you choose five years instead, set a calendar reminder to renew before it runs out.

Editorial & Advertiser Disclosure: The editorial content on this page is not provided, commissioned, reviewed, approved, or otherwise endorsed by any advertiser. Opinions expressed here are ours alone, not those of any advertiser. The offers that appear on this site are from companies that compensate us. That compensation may influence which products we cover and where and how they appear on a page – including the order in which they appear – but it does not influence our evaluations, ratings, or opinions. We do not include every company or offer available in the marketplace.
Related: