
Refinancing federal student loans with a private lender swaps them for a private loan, and the switch can’t be reversed. You give up income-driven payments, Public Service Loan Forgiveness, federal deferment and forbearance, and discharge if you die or become disabled. Refinance federal loans only if the rate savings beat all of that.
A refinance quote shows one number, the new rate. It doesn’t show what disappears when the new lender pays off your federal loans. Those loans carry rights under federal law that no private lender has to match.
Those rights matter most in the years you can’t predict. For most federal borrowers, the Repayment Assistance Plan that opened on July 1, 2026, sets payments at 1% to 10% of income, cut by $50 a month for each dependent, with a $10 minimum. Whatever is left after 30 years of payments is forgiven. Public Service Loan Forgiveness cancels the remaining balance after 120 qualifying payments while you work for government or a qualifying nonprofit. Federal loans can also be deferred or put in forbearance, and they’re discharged if you die or become totally and permanently disabled.
A refinance can still make sense with a steady, high income, no plans for public service work, and a rate cut big enough to matter. Price it before you sign. On $40,000 repaid over 10 years, dropping from 7% to 5% saves about $4,800 in interest, roughly $40 a month. Ask whether $40 a month is worth giving up the right to tie your payment to your income after a layoff.
Two moves keep the protections. Refinance private student loans whenever the rate is better, since they have no federal protections to lose. If all you want is one payment, a federal Direct Consolidation Loan combines federal loans without leaving the program. Its rate is the weighted average of the old rates, rounded up to the nearest eighth of a percent, so it won’t lower your interest.
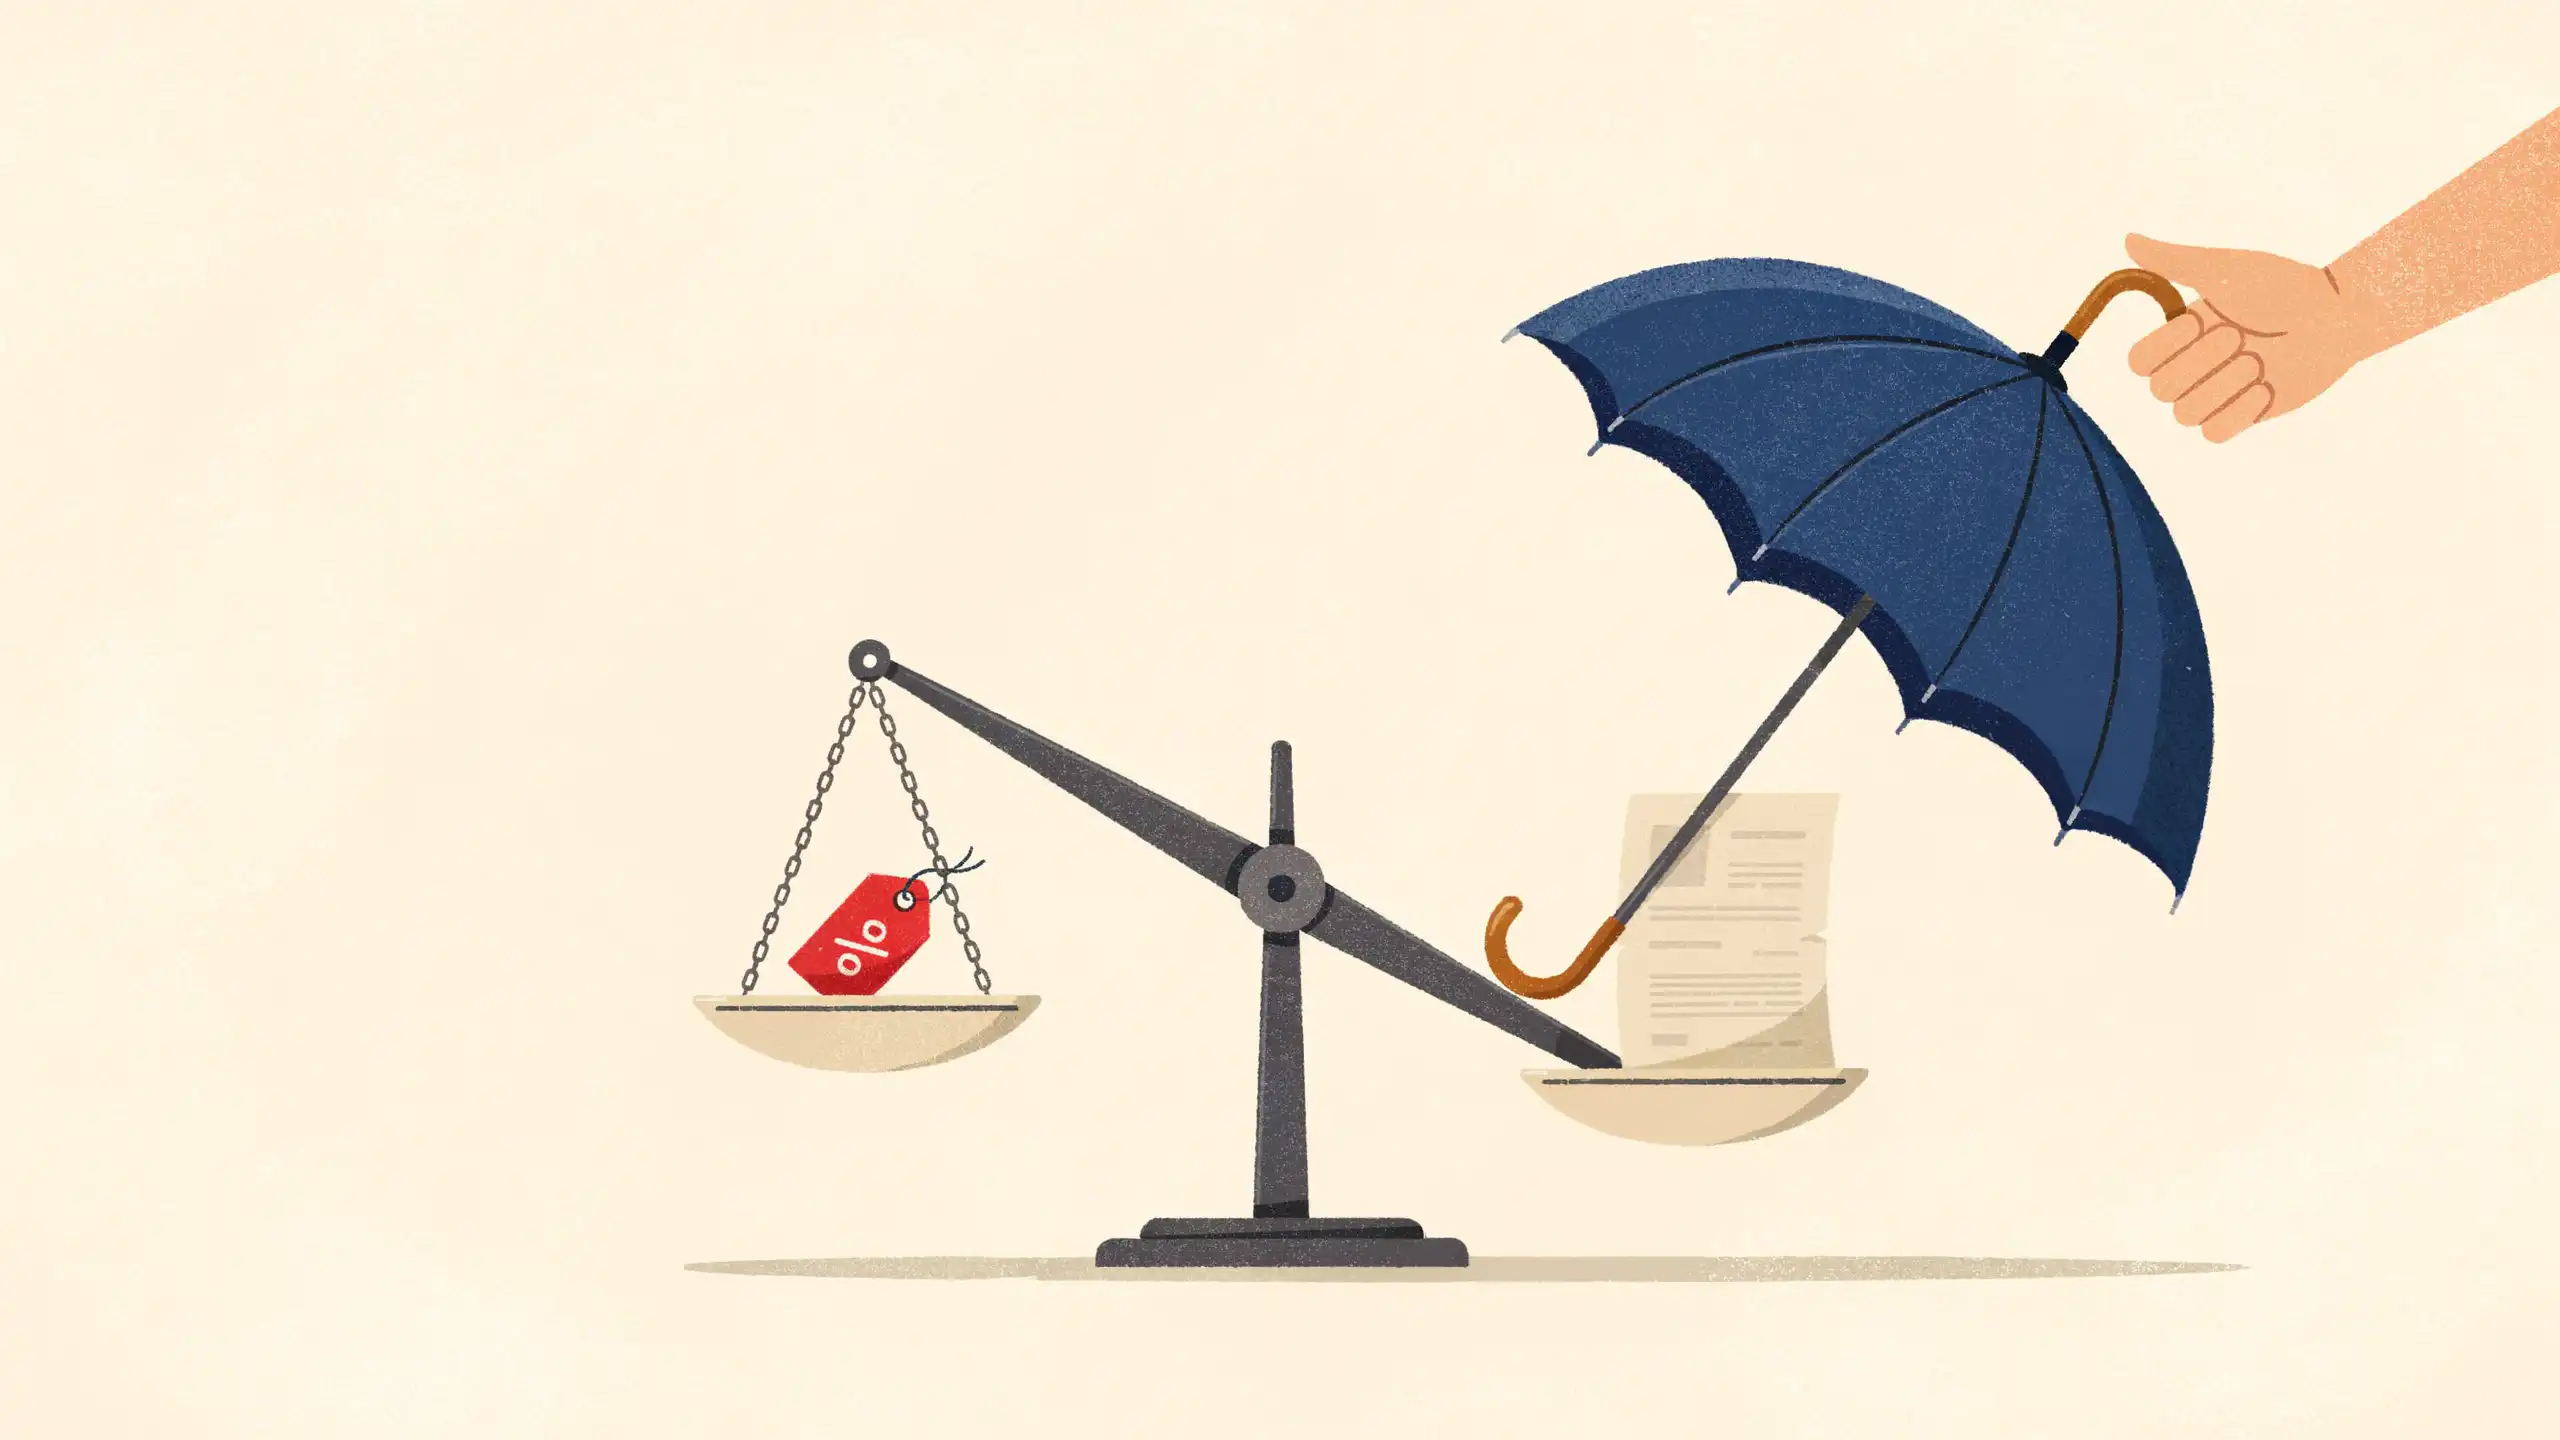
Treat the federal protections as insurance you’d be canceling to lower the premium. If you’d want that coverage after a job loss or a diagnosis, keep the loans federal.

Editorial & Advertiser Disclosure: The editorial content on this page is not provided, commissioned, reviewed, approved, or otherwise endorsed by any advertiser. Opinions expressed here are ours alone, not those of any advertiser. The offers that appear on this site are from companies that compensate us. That compensation may influence which products we cover and where and how they appear on a page – including the order in which they appear – but it does not influence our evaluations, ratings, or opinions. We do not include every company or offer available in the marketplace.
Related: