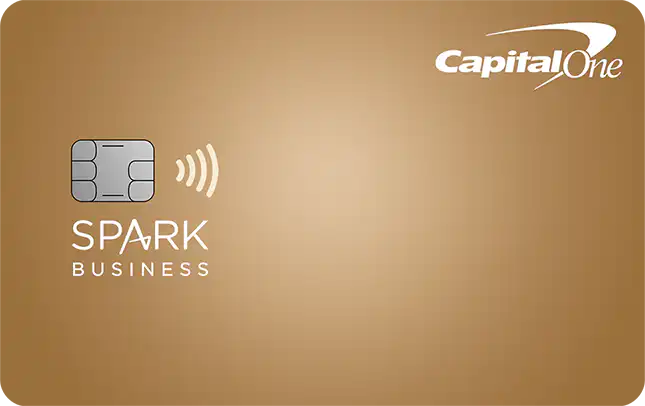
Capital One Spark Classic for Business
- Best for: Business owners with fair credit, a side business included
- What Sets It Apart: The only card in Capital One’s business lineup that takes fair credit, and it costs nothing to keep
- Rewards: 1% cash back on every purchase; 5% on hotel stays and car rentals booked in Capital One Business Travel; cash back never expires
- Features: Activity reported to the personal credit bureaus; free employee cards with spending limits; account managers, virtual card numbers, and QuickBooks exports; $0 fraud liability
- Annual Fee: $0
- Security Deposit: None; the limit depends on your personal credit and finances
- APR: 29.24% variable
- Cost: No foreign transaction fee
- Credit Needed: Fair; a pre-approval check doesn’t affect your score
- Eligibility: Business owners, sole proprietors included, who apply with their SSN; revenue and time in business can count
- Pros: Open to fair credit; a pre-approval check that doesn’t affect your score; on-time payments can help your personal score; cash back never expires
- Cons: Just 1% back; no welcome bonus or intro APR; a carried balance costs more in interest than its purchases earn; late payments and high balances can hurt your personal score

Get the Capital One Spark Classic for Business if your fair credit rules out better business cards. It charges no annual fee and reports to the personal credit bureaus, so paying on time with a low balance can help raise your score. With excellent credit, apply for the Spark Cash Select instead, which pays 1.5% back.
Capital One sells it to business owners with fair credit, which its guidelines define as a loan default in the past five years or less than three years of credit history. A side business can qualify, since a sole proprietor applies with a Social Security number in place of a tax ID.
Key Features
- $0 annual fee and no foreign transaction fee
- 1% cash back on every purchase, and 5% on hotel stays and car rentals you book through Capital One Business Travel
- 29.24% variable APR, the yearly interest rate on balances you carry
- Free employee cards, each with a spending limit you set
- Account activity reported to the personal credit bureaus
Pros
- The only Capital One business card open to fair credit, with a pre-approval check that doesn’t affect your score
- On-time payments can help your personal credit score
- Cash back that never expires, redeemed as a statement credit or a check
- Account managers, virtual card numbers, and purchase records you can export to QuickBooks or Excel
Cons
- Just 1% back, so a business spending $2,000 a month earns $240 a year, $120 less than with the no-fee Spark Cash Select’s 1.5%
- No welcome bonus or intro APR
- A carried balance costs more in one month’s interest than its purchases earned in cash back
- Late payments and high balances can hurt your personal credit score
Owners with fair credit or a short credit history get a no-fee business card, and each on-time payment goes on their personal credit report. The Spark Cash Select pays 1.5% back but asks for excellent credit, which, by Capital One’s guidelines, takes at least three years with a card or loan and a limit above $5,000.
Learn more about the Capital One Spark Classic for Business or see how it compares to the best small business credit cards.

Editorial & Advertiser Disclosure: The editorial content on this page is not provided, commissioned, reviewed, approved, or otherwise endorsed by any advertiser. Opinions expressed here are ours alone, not those of any advertiser. The offers that appear on this site are from companies that compensate us. That compensation may influence which products we cover and where and how they appear on a page – including the order in which they appear – but it does not influence our evaluations, ratings, or opinions. We do not include every company or offer available in the marketplace.
Related: