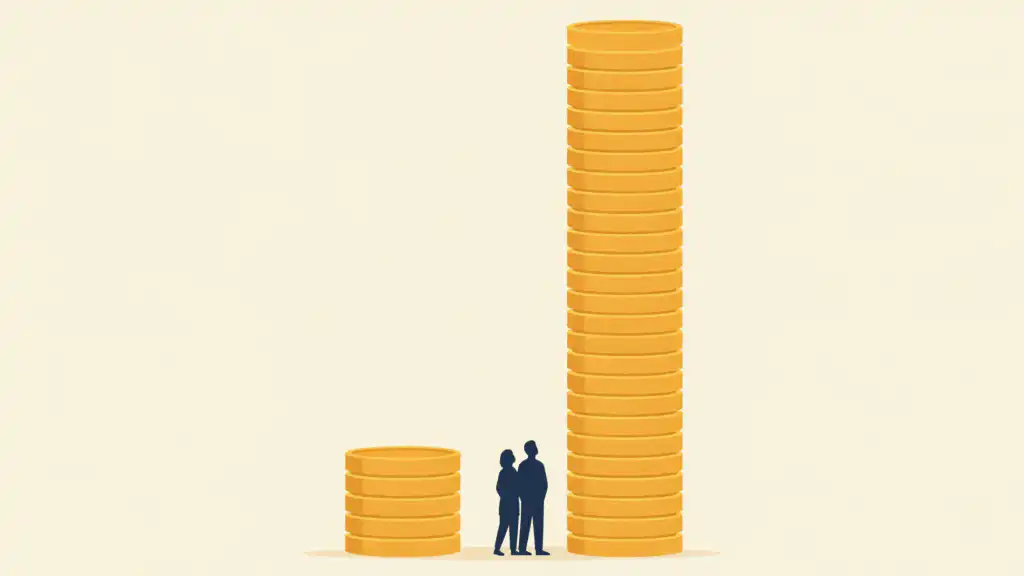

Claiming Social Security at 70 instead of 62 makes your monthly check about 77% larger if your full retirement age is 67. If you’re healthy and can cover the gap from savings, delay your claim. The larger checks make up for the missed years by about age 80, and they rise with inflation for life.
The increase is set by law. With a full retirement age of 67, which covers anyone born in 1960 or later, claiming at 62 pays 70% of your full benefit for life. Each year you wait past 67 adds 8%, so claiming at 70 pays 124%. Divide one by the other and the check at 70 is 77% larger.
The price is eight years of checks you don’t collect. If you leave out taxes and what the early checks could have earned invested, the 70 claimer’s lifetime total of payments passes the 62 claimer’s at about age 80. Cost-of-living raises don’t move that point, because they lift both checks by the same percentage.
The Social Security Administration’s 2023 life table gives a 62-year-old man about 20 more years and a woman about 23, so the average 62-year-old lives past 80. For a married higher earner, waiting also sets the survivor’s income, because a widow or widower can step up to the deceased spouse’s check, delayed credits included.
Delay if you’re healthy and savings or work income can cover the years until 70, especially as a couple’s higher earner. Withdrawals from a traditional IRA can bridge the gap, and they shrink the required minimum distributions that start in your 70s. Claim sooner if your health or family history points to a shorter life, if waiting means running up debt, or if you’re the lower earner and your spouse is the one delaying.
Delaying Social Security doesn’t delay Medicare. Sign up around your 65th birthday anyway, because a late start can add a penalty to your Part B premium for as long as you’re enrolled. Coverage from your or your spouse’s current job at an employer with 20 or more workers lets you wait without a penalty until eight months after that job ends.
Before you pick an age, log in to your my Social Security account at ssa.gov and open your Statement, which estimates your check at every age from 62 to 70. Then price the gap years against your own savings, not a rule of thumb.

Editorial & Advertiser Disclosure: The editorial content on this page is not provided, commissioned, reviewed, approved, or otherwise endorsed by any advertiser. Opinions expressed here are ours alone, not those of any advertiser. The offers that appear on this site are from companies that compensate us. That compensation may influence which products we cover and where and how they appear on a page – including the order in which they appear – but it does not influence our evaluations, ratings, or opinions. We do not include every company or offer available in the marketplace.
Related: