
Your 40s still give new savings time to compound, so check now whether you’re on track for retirement. Fidelity’s guideline is to have at least three times your salary saved by 40 and six times by 50. Push your 401(k) contributions toward the yearly limit, fund an IRA, and start adding some bonds to your investments.
Find a retirement shortfall at 45, and you have about 20 years to close it before 65. Find it at 60, and you have five.
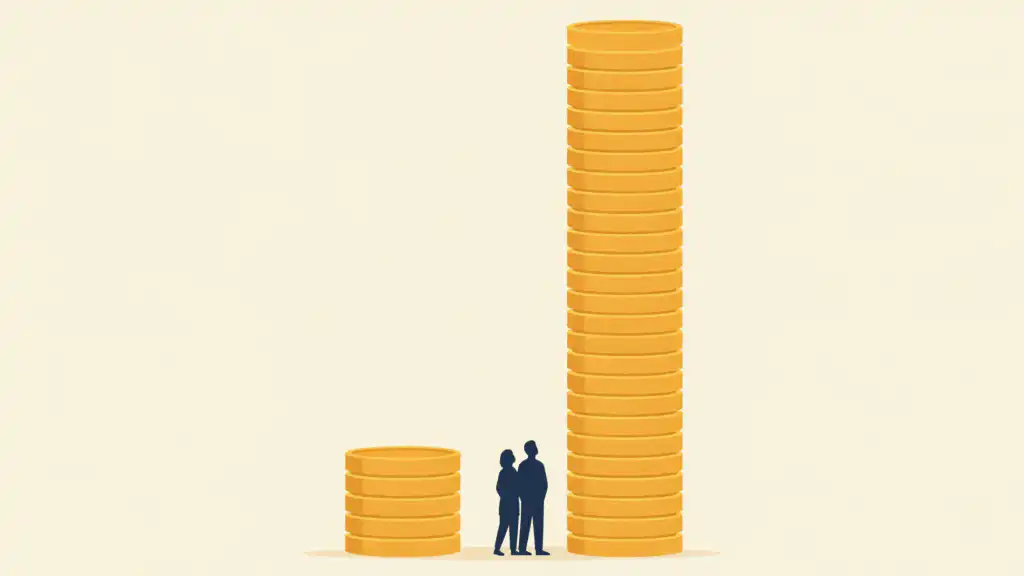
At a hypothetical 7% average annual return, $150,000 saved at 45 plus $1,000 a month grows to about $1.1 million by 65. Starting the $1,000 a month at 45 rather than 50 means five more years of deposits, $60,000 in all, and about $200,000 more at 65.
So divide your retirement savings by your salary now and compare the result with Fidelity’s guideline. It assumes you’ve saved 15% of your pay since age 25, any employer match included, and will retire at 67. The total to aim for is your retirement number, about 25 times the yearly spending Social Security won’t cover.
Whatever your numbers show, make these moves this decade:
- Max out your 401(k) at $24,500 a year, or get as close as your budget allows. The limit covers only what you put in, so an employer match comes on top. Some plans set a lower cap for high earners.
- Fund an IRA up to its annual limit too. Having a 401(k) doesn’t stop you, though it can limit the tax deduction on a traditional IRA. A high income can also limit Roth IRA contributions.
- Put retirement ahead of college savings and a bigger house. There are loans for school and for homes, but none for retirement.
- Move a small share of your savings from stocks into bonds each year, so you aren’t making one big switch near retirement.
If you’re behind, also plan to work a few years longer. Each extra year of work adds a year of saving and leaves one less year of retirement for your savings to pay for.
Log in to your 401(k) this week and raise your contribution by two percentage points, then add a point with every raise until you hit the limit.
To choose a provider for your IRA, compare the best places to open an IRA.

Editorial & Advertiser Disclosure: The editorial content on this page is not provided, commissioned, reviewed, approved, or otherwise endorsed by any advertiser. Opinions expressed here are ours alone, not those of any advertiser. The offers that appear on this site are from companies that compensate us. That compensation may influence which products we cover and where and how they appear on a page – including the order in which they appear – but it does not influence our evaluations, ratings, or opinions. We do not include every company or offer available in the marketplace.
Related: