
Your card issuer can close a credit card you stop using, and it doesn’t have to warn you first. Losing that card’s limit can lower your credit score. Keep each idle no-fee card open by moving one small subscription you already pay onto it, with autopay set to the full statement balance so it costs nothing extra.
The cards at risk are the ones you keep for your credit score and never touch. Think of the no-fee card you opened years ago that now sits in a drawer, often your oldest account.
There’s no standard timeline for how long a card can sit unused. Some issuers may close an inactive account after several months, others after a year, and some cut the credit limit first. Federal rules bar inactivity fees on credit cards, so no fee ever tips you off.
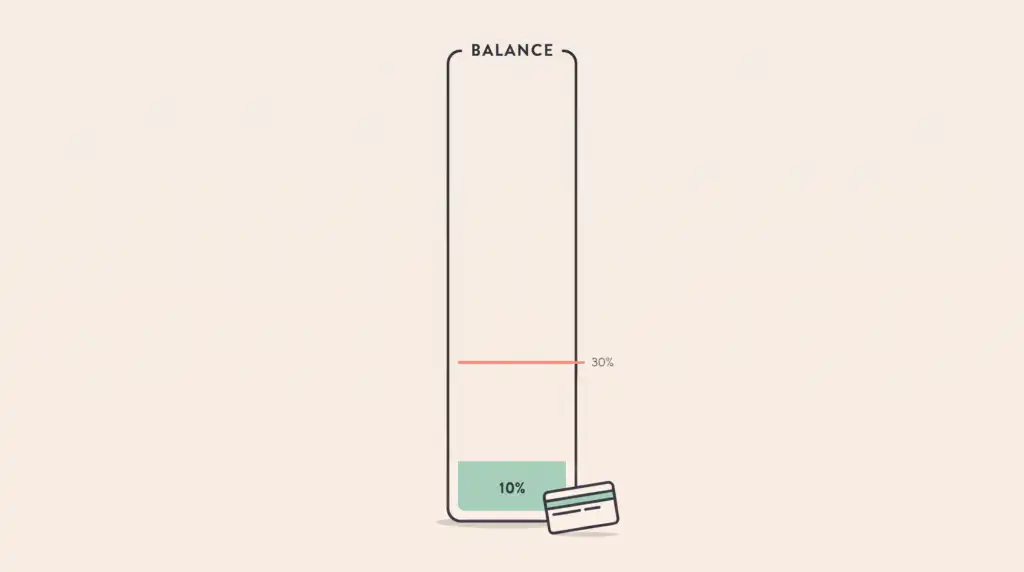
A closure doesn’t erase the card’s history right away. Your credit reports can keep a card closed in good standing for as long as 10 years, and FICO and VantageScore both count it when they measure the age of your accounts. What changes first is your credit utilization, the share of your available credit you’re using, because the closed card’s limit leaves that total.
Say you carry $3,000 across cards with $20,000 in combined limits, so your utilization is 15%. If the issuer closes the $8,000-limit card you got in college, the same $3,000 becomes 25% of $12,000. The age hit comes years later, when the closed account falls off your reports and stops counting toward your account age.
Each card takes a few minutes to set up:
- Move one small subscription you already pay, such as a streaming service, onto the idle card. You’d pay that bill anyway, so the card stays active with no new spending.
- Set autopay to the full statement balance. Most cards give purchases a grace period, so a statement paid in full by the due date carries no interest.
- Turn on an alert for every charge. Each month’s alert confirms the subscription still bills to this card, and any other alert is a charge to check.
- Keep the physical card at home instead of in your wallet. The subscription only needs the number.
Check each card’s last purchase date in its app, and this week, set up any card that has sat idle for a few months.

Editorial & Advertiser Disclosure: The editorial content on this page is not provided, commissioned, reviewed, approved, or otherwise endorsed by any advertiser. Opinions expressed here are ours alone, not those of any advertiser. The offers that appear on this site are from companies that compensate us. That compensation may influence which products we cover and where and how they appear on a page – including the order in which they appear – but it does not influence our evaluations, ratings, or opinions. We do not include every company or offer available in the marketplace.
Related: