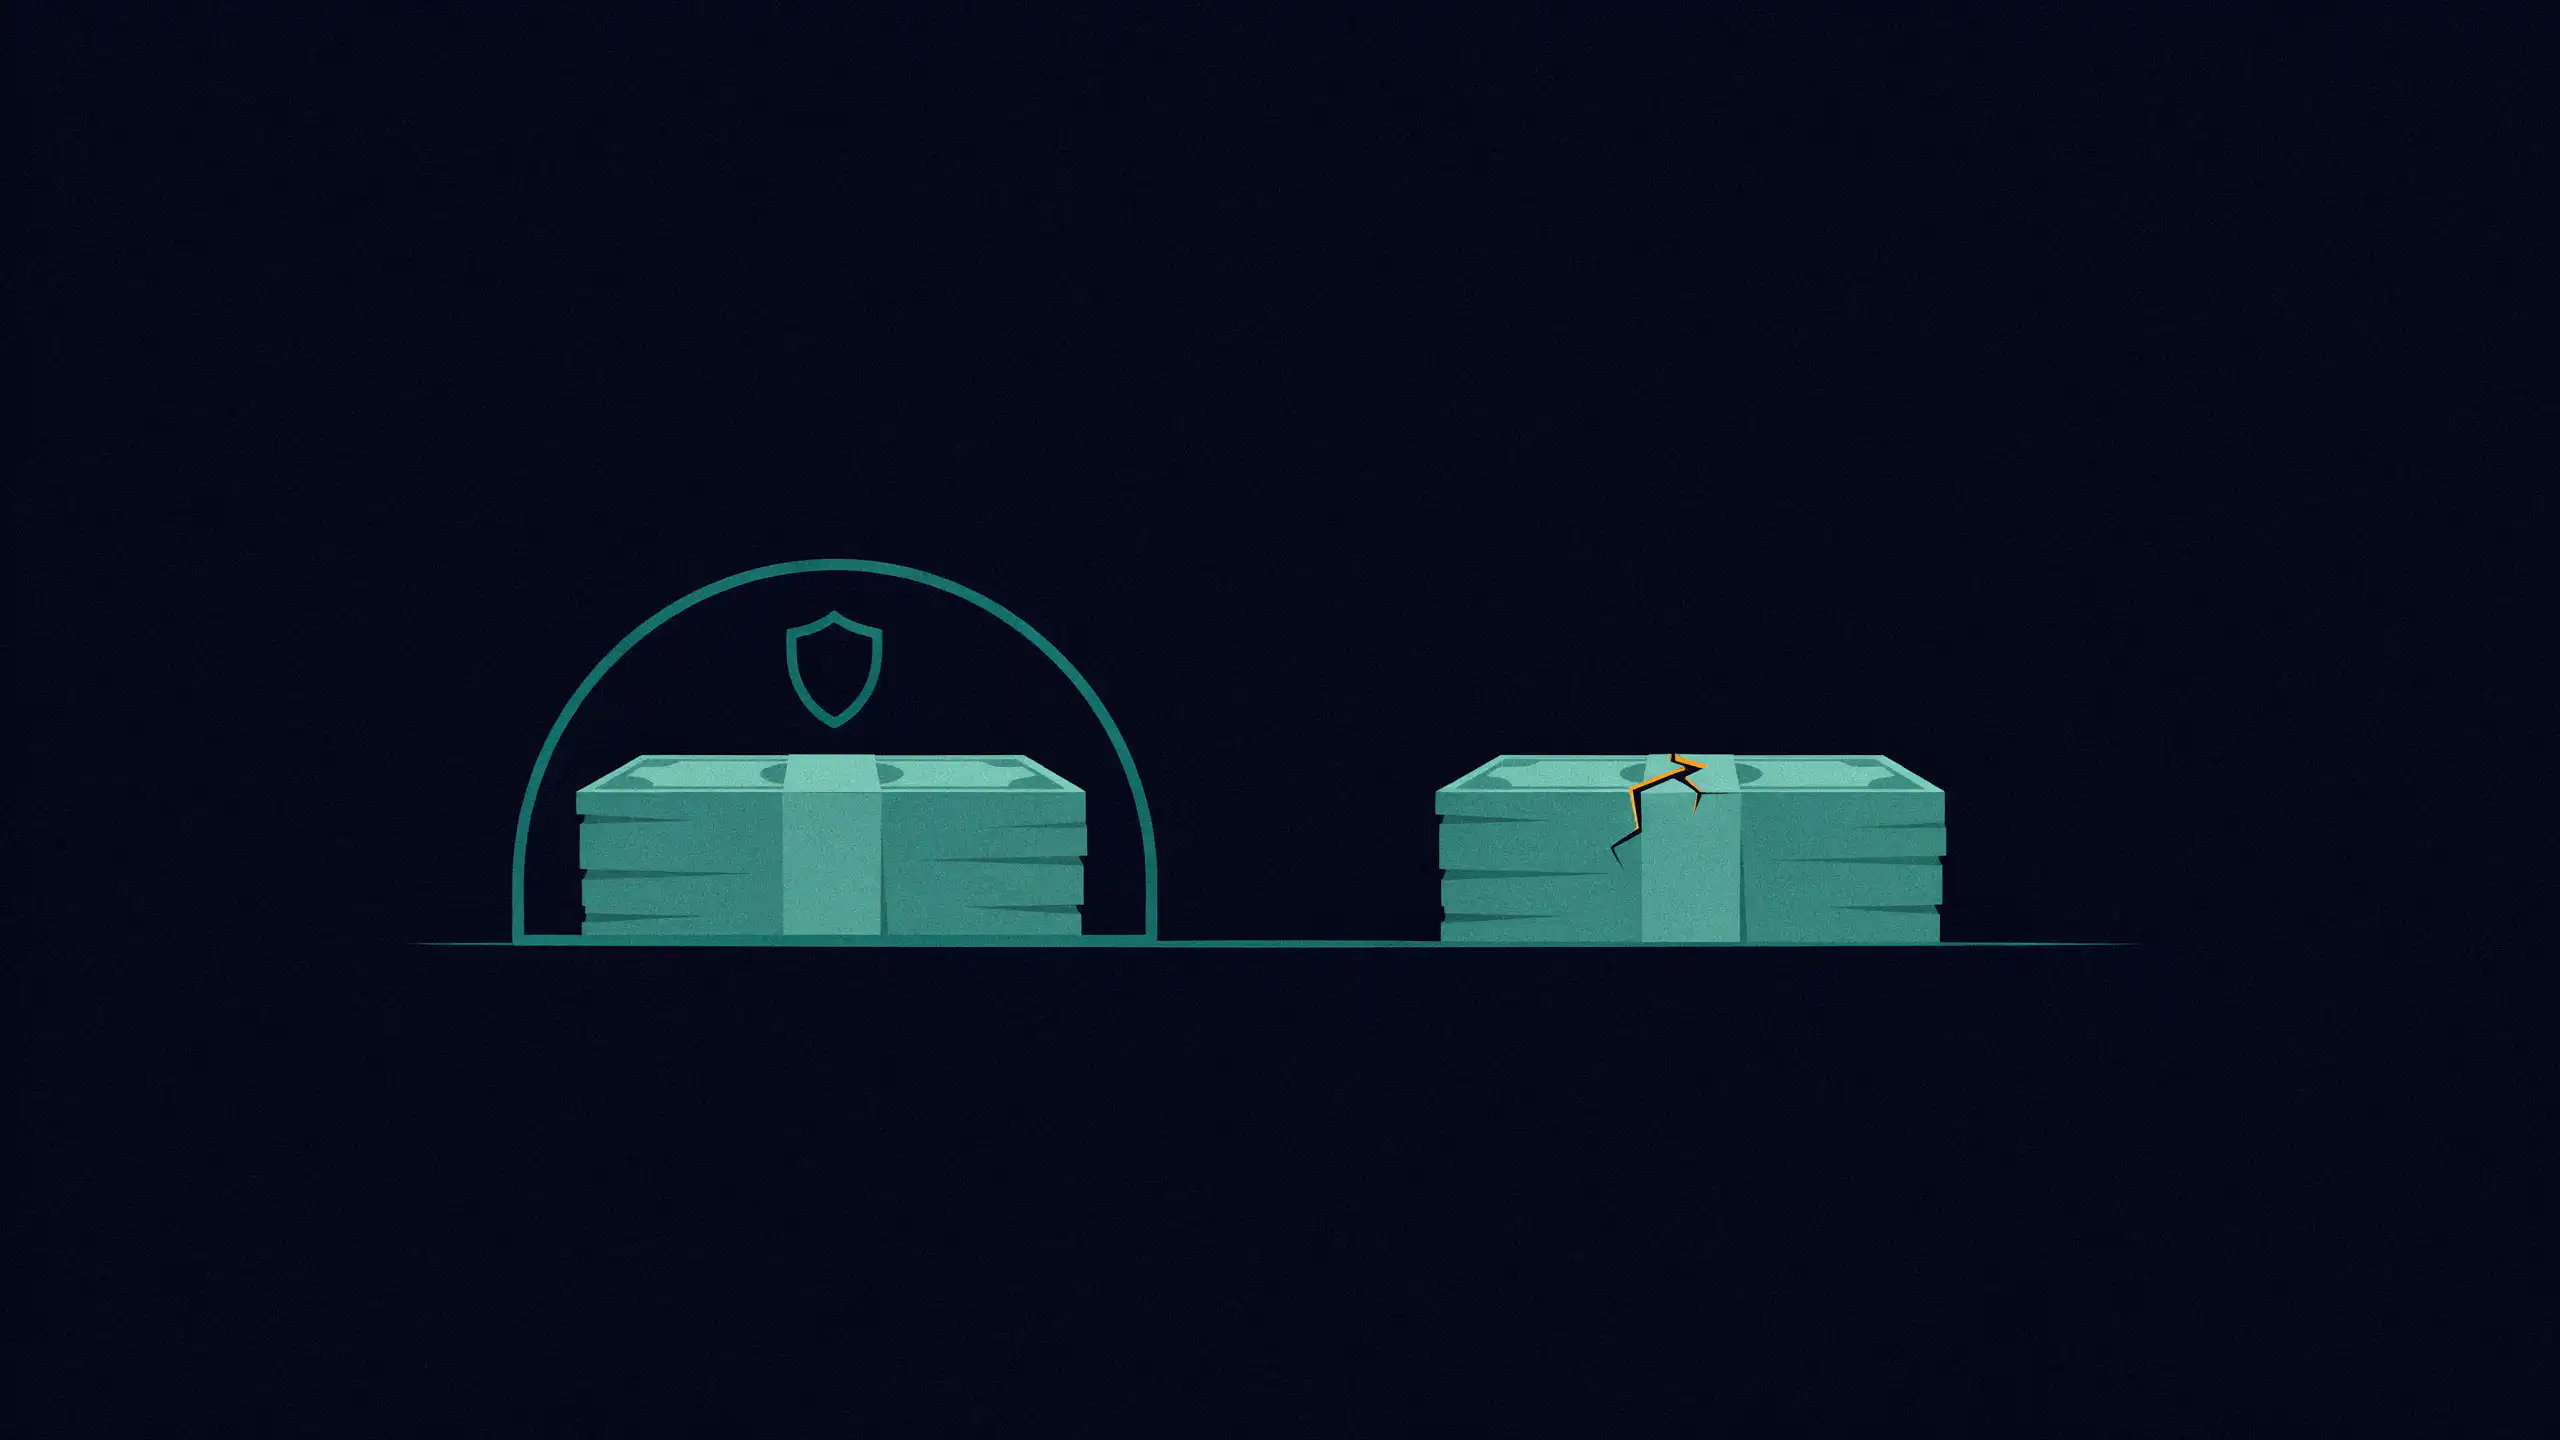

A money market account is a bank deposit, insured up to $250,000. A money market fund is a mutual fund that aims to hold $1 a share but carries no FDIC guarantee. Check which one you’re buying before you move cash, and keep money you can’t afford to lose in the insured account.
The names are nearly identical, and a brokerage screen and a bank app can both show your cash sitting in a money market. What protects that cash depends on which one it is.
The account side is simple. FDIC insurance covers a money market account up to $250,000 per depositor, per bank, for each ownership category, and NCUA coverage works the same way at a credit union. If the institution fails, insurance pays back your balance up to that limit.
The fund works differently. It buys short-term debt and tries to keep its share price at $1, and the FDIC doesn’t insure it. SIPC protects your fund shares if your brokerage collapses, but not against a drop in their value. Losses are rare, not impossible. In September 2008, the Reserve Primary Fund’s shares fell to 97 cents after Lehman Brothers collapsed. New York Fed researchers later found at least 28 other funds that would have dropped below $1 without help from their sponsors.
So tell them apart before you move money. A fund has a prospectus and a ticker, usually five letters ending in XX, and it reports its return as a 7-day SEC yield. An account pays a stated interest rate at an insured bank or credit union.
Then match the money to the product. Emergency savings and anything you can’t afford to see shrink belong in the insured account. Cash you’re holding for investing can go in a government money market fund, which must keep at least 99.5% of its assets in cash, government securities, and short-term loans fully backed by them.
A fund’s appeal is yield. That 7-day SEC yield is net of expenses and usually follows the Fed’s rate changes. Compare it with the best insured rate you can get before you give up the guarantee.
Check where your emergency savings sit today. If the holding has a ticker ending in XX, that money is in a fund, not an insured account.

Editorial & Advertiser Disclosure: The editorial content on this page is not provided, commissioned, reviewed, approved, or otherwise endorsed by any advertiser. Opinions expressed here are ours alone, not those of any advertiser. The offers that appear on this site are from companies that compensate us. That compensation may influence which products we cover and where and how they appear on a page – including the order in which they appear – but it does not influence our evaluations, ratings, or opinions. We do not include every company or offer available in the marketplace.
Related: