
Check your homeowners or renters insurance declarations page to see whether your house and belongings are covered at replacement cost or actual cash value. Replacement cost pays today’s price to rebuild or rebuy. Actual cash value deducts wear and age first, so wherever you find it, ask your agent to quote the upgrade.
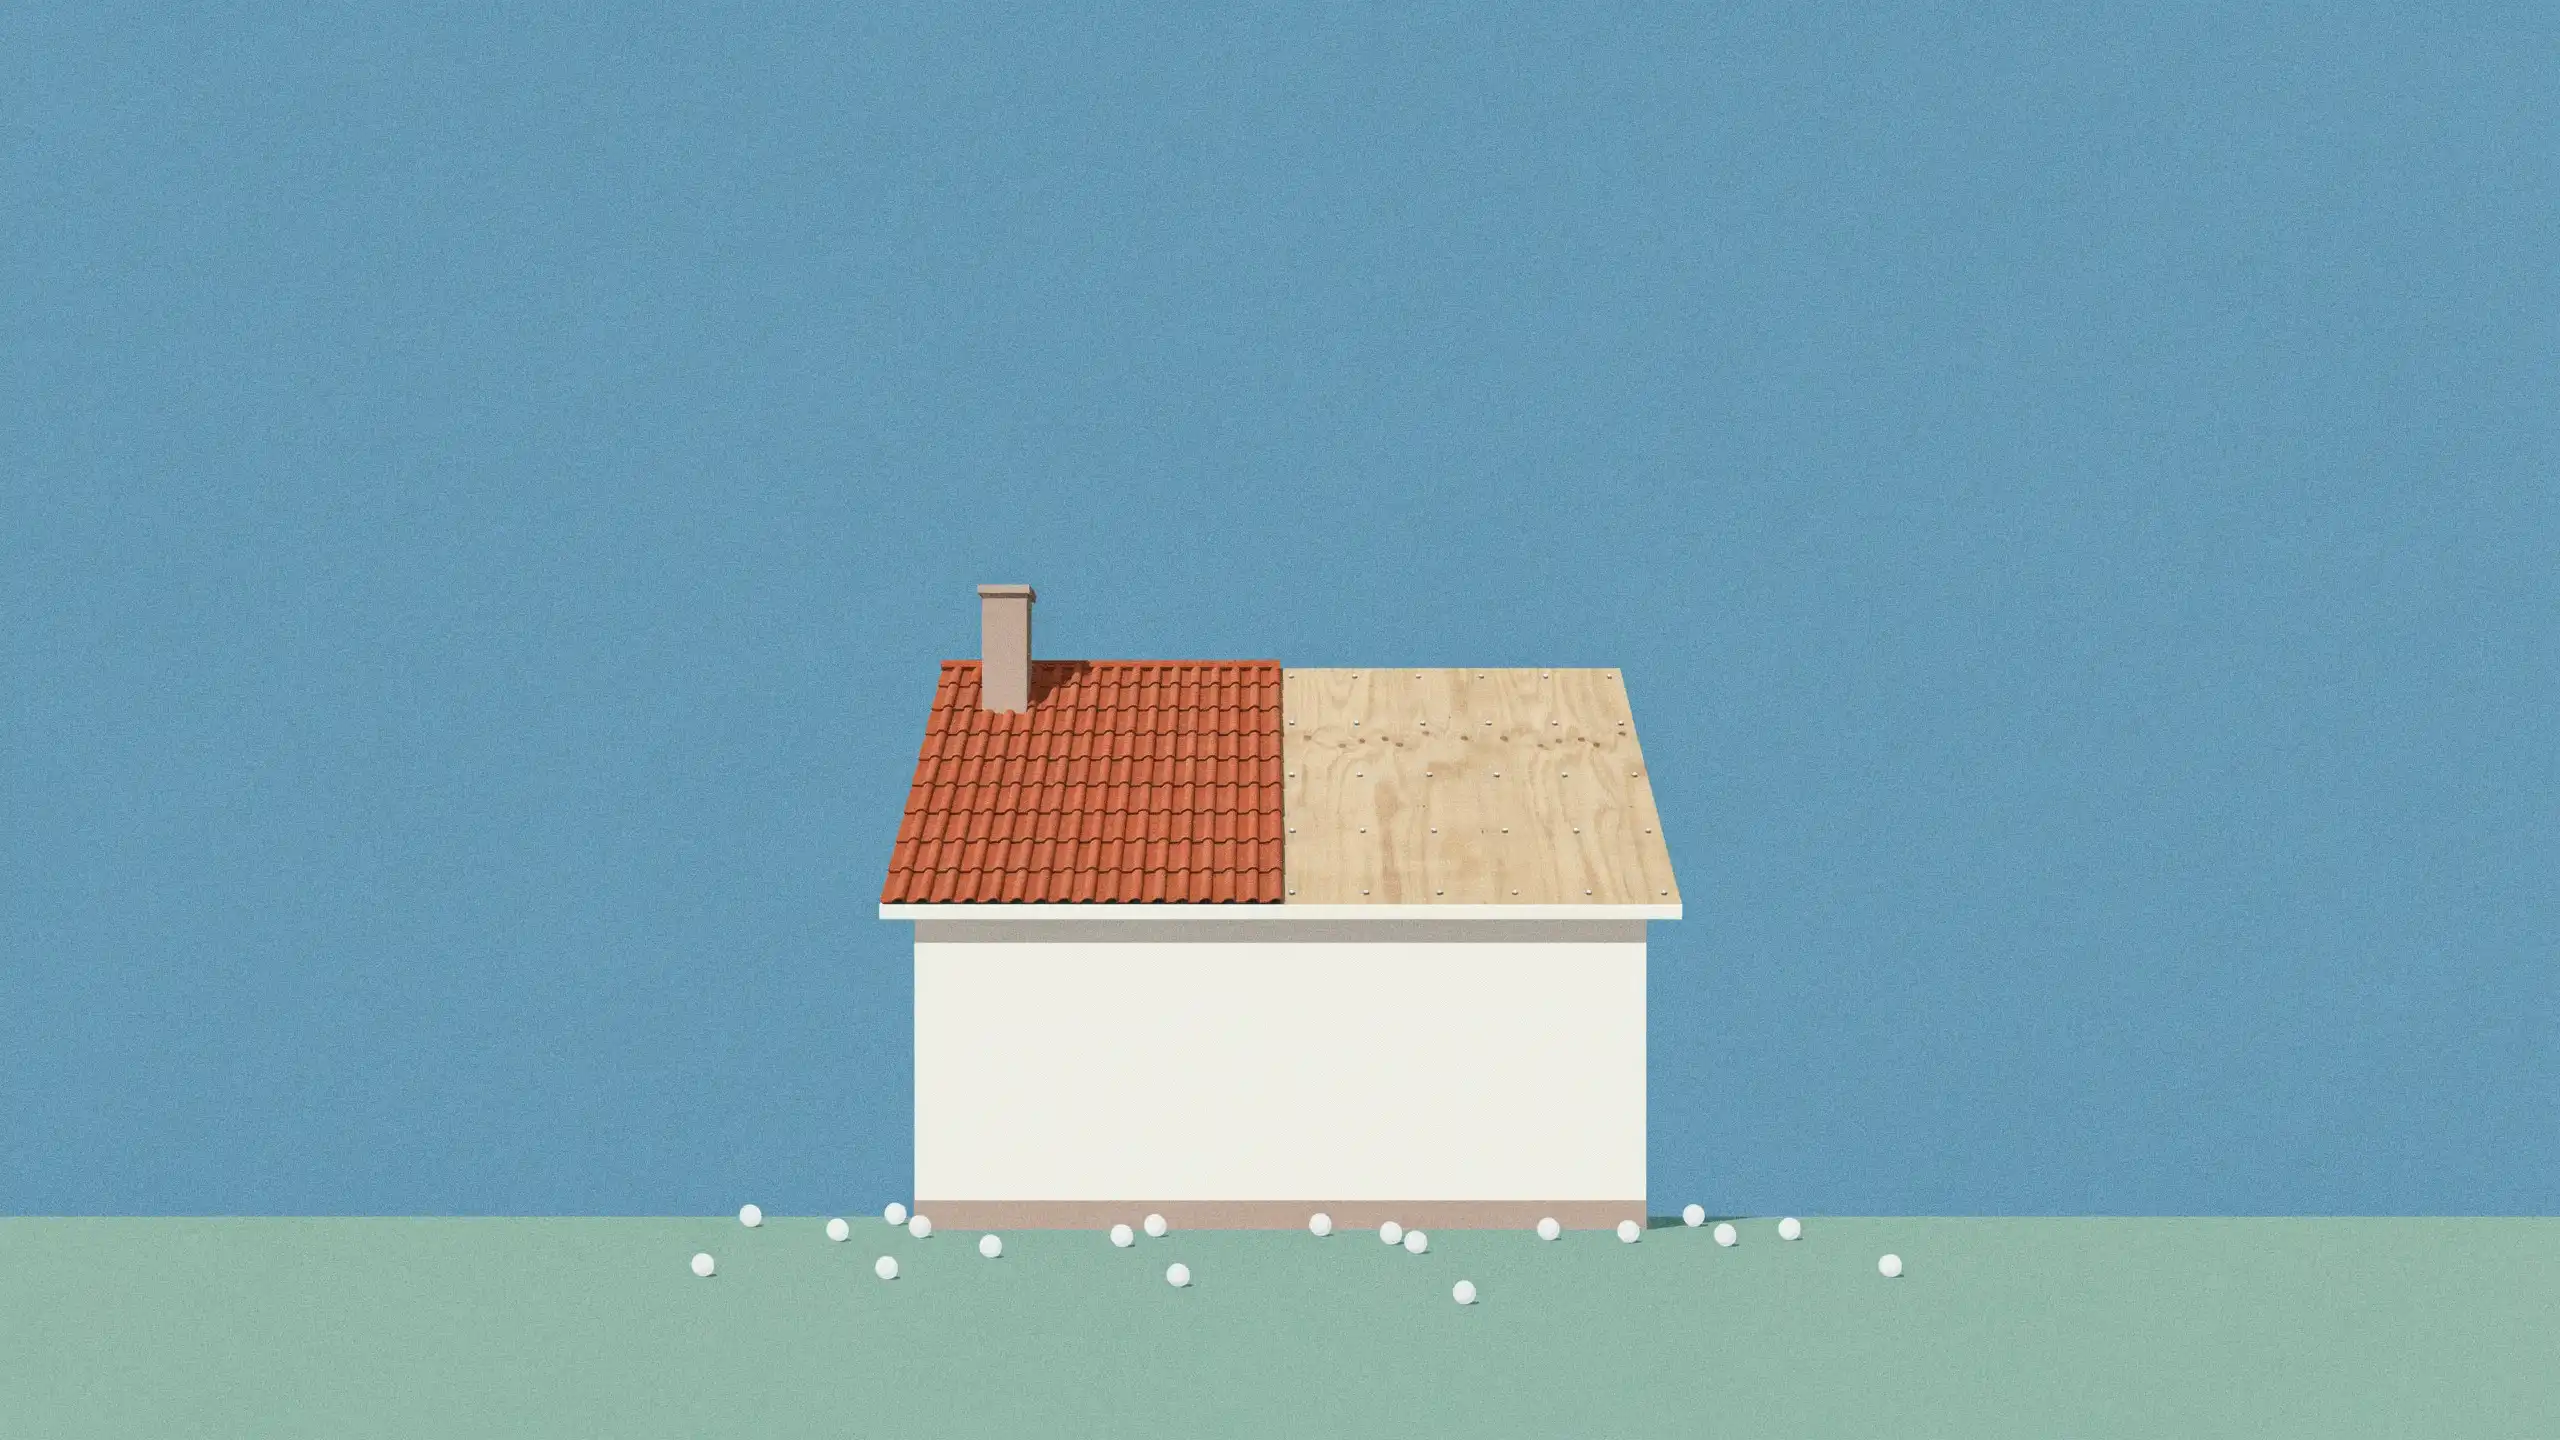
The difference shows up the day a storm takes your roof. Say hail wrecks your 10-year-old shingle roof, a new one costs $12,000, and your deductible is $1,000.
With replacement cost, the insurer pays $11,000 after your deductible. With actual cash value, it subtracts depreciation first. If it figures shingles last 20 years, it counts yours as half used up, values the roof at $6,000, and pays $5,000. Same storm, same roof, and you pay $7,000 yourself instead of $1,000.
The standard homeowners form covers the house itself at replacement cost, but two common exceptions leave claims short. The first is the roof. Many policies now add an endorsement, a clause that switches it to actual cash value, sometimes only for wind and hail damage. Others set the payout by a schedule tied to the roof’s age and material.
The second is your belongings. That standard form pays actual cash value on personal property unless you add replacement cost by endorsement, and on a renters policy that upgrade costs extra too.
Open your declarations page, the summary at the front of the policy, and look for replacement cost or actual cash value beside the dwelling and personal property coverages. Then read the endorsements it lists for anything that names the roof.
Know how replacement cost pays, too. Most insurers send the actual cash value first and the rest after the work is done and they see the bill. You usually have a deadline to finish the job. On that roof, that’s $5,000 up front and $6,000 once the new roof is on.
If you find actual cash value on the roof or your belongings, or can’t tell either way, ask your agent to quote the replacement-cost upgrade. Weigh the added premium against the gap it closes, $6,000 on that roof alone.
It’s a five-minute check, and the only time to find actual cash value on your policy is before an adjuster does.

Editorial & Advertiser Disclosure: The editorial content on this page is not provided, commissioned, reviewed, approved, or otherwise endorsed by any advertiser. Opinions expressed here are ours alone, not those of any advertiser. The offers that appear on this site are from companies that compensate us. That compensation may influence which products we cover and where and how they appear on a page – including the order in which they appear – but it does not influence our evaluations, ratings, or opinions. We do not include every company or offer available in the marketplace.
Related: