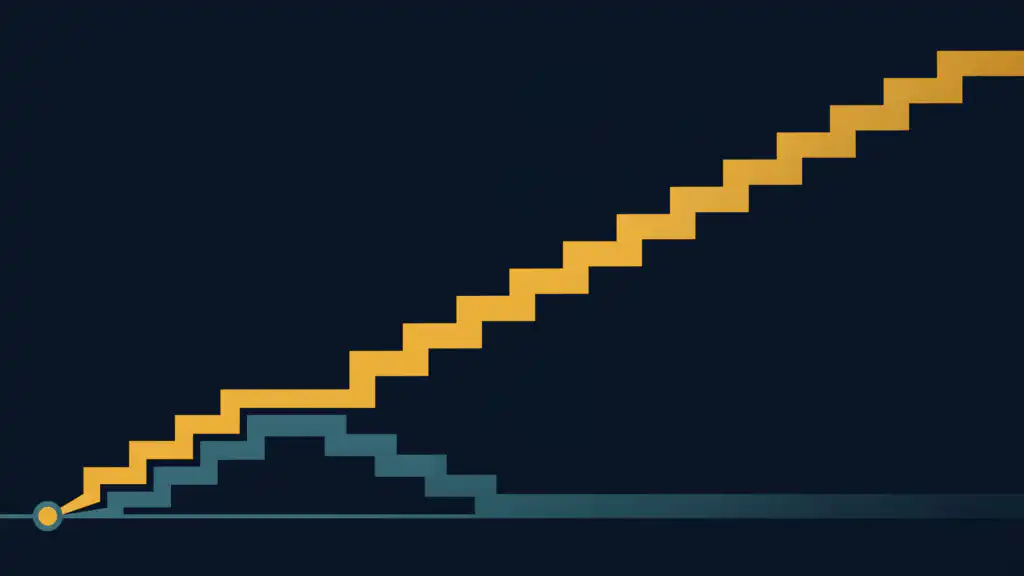

When you start investing from scratch, your savings rate moves your balance far more than the return you earn, so raise what you contribute before you hunt for a better fund. At a 7% return, a year’s gains don’t overtake a year’s savings until about a decade in, and then returns take over.
A return is a percentage of what you already have, and early on you don’t have much. A 7% year on a $5,000 balance earns $350, while saving $100 more a month adds $1,200 a year.
That gap closes on a schedule you can work out. Start from zero and invest the same amount every month at a 7% annual return, and a year’s gains stay smaller than a year’s deposits until your balance passes about 14 times your annual deposits. By our math, that takes about 10 years. How much you deposit doesn’t change the timing. Only the return does, and at 5% the wait stretches to about 14 years.
Say you invest $500 a month. Three years in, you’d have about $20,000, so finding a fund that earns one extra percentage point adds about $200 a year. Raising your deposit to $600 a month adds $1,200 a year. Until the crossover, spend your effort on how much you deposit.
- Raise your savings rate by a percentage point or two of your pay each year, and send part of every raise to your investments.
- Take the full employer match first. A 50% match is a 50% return on those dollars before the market moves, once you’ve stayed long enough to keep it.
- Pick a low-cost, broadly diversified index fund and stop shopping for a better one.
The math flips later. At a $300,000 balance, one extra percentage point of return is worth $3,000 a year, two and a half times the $1,200 a year that the extra $100 a month adds. That’s the stage when low fees and holding your mix of stocks and bonds through bad years do the most for you.
To see which stage you’re in, divide your balance by what you deposit in a year. Under about 14 at a 7% return, or 20 at 5%, saving more is your best move. Past it, turn your attention to costs and your mix of stocks and bonds.

Editorial & Advertiser Disclosure: The editorial content on this page is not provided, commissioned, reviewed, approved, or otherwise endorsed by any advertiser. Opinions expressed here are ours alone, not those of any advertiser. The offers that appear on this site are from companies that compensate us. That compensation may influence which products we cover and where and how they appear on a page – including the order in which they appear – but it does not influence our evaluations, ratings, or opinions. We do not include every company or offer available in the marketplace.
Related: