
If you’re married, file jointly, and one of you isn’t earning, a spousal IRA lets the working spouse’s income fund an IRA in the other spouse’s name. Open the account and fund it every year you’re down to one paycheck, because a skipped year can’t be made up later.
IRA contributions normally require earned income, so many at-home spouses assume they’re shut out. Joint filers get an exception, whether the spouse without a paycheck is raising kids, caring for a parent, between jobs, or retired early.
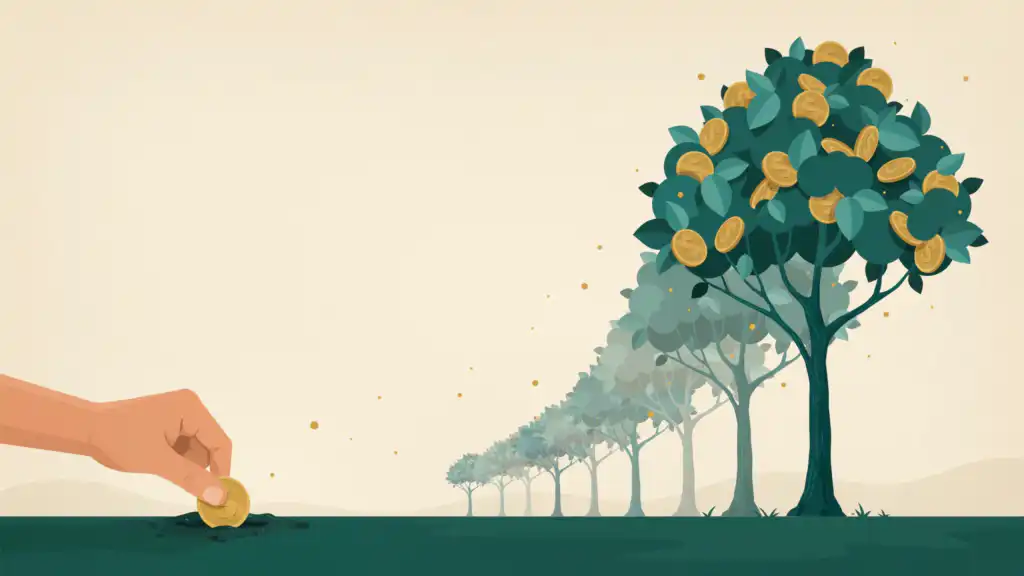
Years at home with young kids often come early in a career, so money put in then has the most time to compound. Say you step away from work at 30 and return at 35. If $500 a month from your spouse’s paycheck goes into your spousal IRA for those five years, that $30,000 grows to more than $300,000 by 67 at an assumed 7% average annual return. Skip those years and you give up far more than $30,000, because no later contribution gets that much time to grow.
The account is also yours alone, because the IRS doesn’t allow joint IRAs. That matters if the marriage ends. A court can still divide savings built during the marriage, but you’d already hold retirement money in your own name instead of depending entirely on a share of your spouse’s accounts.
To qualify, you must be married and file a joint return, and your combined earned income has to cover the contributions to both spouses’ IRAs.
The account itself is an ordinary traditional or Roth IRA, opened at any brokerage in your name. Roth eligibility has income limits, and so does the traditional IRA deduction when either spouse has a retirement plan at work. The IRS publishes each year’s figures, so check the current numbers before you choose.
You can make a year’s contribution until that year’s tax-filing deadline, usually April 15 of the following year, and a filing extension doesn’t add time.
Open the account now and set up an automatic monthly transfer from the working spouse’s pay, so every year at home adds to retirement savings in your own name.

Editorial & Advertiser Disclosure: The editorial content on this page is not provided, commissioned, reviewed, approved, or otherwise endorsed by any advertiser. Opinions expressed here are ours alone, not those of any advertiser. The offers that appear on this site are from companies that compensate us. That compensation may influence which products we cover and where and how they appear on a page – including the order in which they appear – but it does not influence our evaluations, ratings, or opinions. We do not include every company or offer available in the marketplace.
Related: