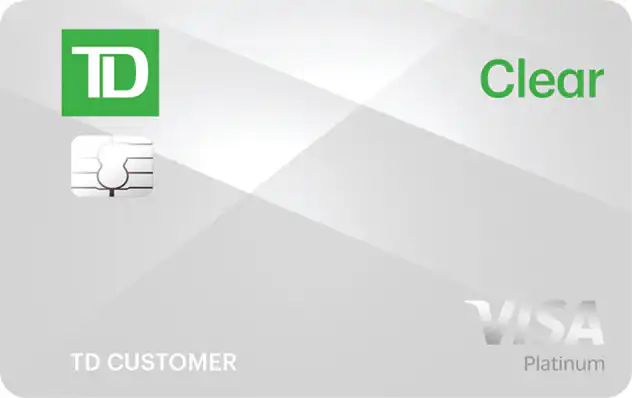
TD Clear Visa® Platinum Credit Card
- Best for: Residents of TD’s East Coast states who owe more than 57% of the limit month after month
- What Sets It Apart: No interest at all; a flat monthly fee set by the limit you choose
- Cost: $10 a month for a $1,000 limit or $20 for $2,000, billed even if you don’t use the card; $0 late, balance transfer, cash advance, and foreign transaction fees
- Features: Minimum payment of $45 or $70, fee included; cell phone protection when you pay your phone bill with the card
- Pros: Costs less than interest at the 21.19% average bank card rate once you owe more than 57% of the limit; a cost that doesn’t grow with your balance; no late fee
- Cons: Paying in full still costs $120 or $240 a year; no rewards; limits of only $1,000 or $2,000; offered only in 15 East Coast states and D.C.

Get the TD Clear Visa® Platinum Credit Card only if you’ll owe more than 57% of its limit every month. At that balance, its $10 or $20 monthly fee, charged instead of interest, costs less than a typical card’s interest. Skip it if you pay in full, since the fee is billed every month either way.
Over a year, that fee comes to 12% of the credit limit you pick. By our math, the fee costs less than interest only when you owe more than 57% of the limit, at the 21.19% average rate the Federal Reserve reported for bank credit cards in August 2026.
Key Features
- A fee of $10 a month on a $1,000 limit or $20 on a $2,000 limit, billed even if you don’t use the card
- No interest on purchases, balance transfers, or cash advances, and no fee for any of them
- A minimum payment, fee included, of $45 on the $1,000 limit or $70 on the $2,000, or the whole balance when it’s less
- No late fee, though a missed payment lets TD close the account and can show up on your credit report
- Open only to residents of CT, DE, FL, MA, MD, ME, NC, NH, NJ, NY, PA, RI, SC, VA, VT, and Washington, D.C. (in Vermont, only the $2,000 limit)
Pros
- Cheaper than a typical card’s interest above $570 owed on the $1,000 limit or $1,140 on the $2,000
- A fixed cost, the same on $100 owed as on $900
- Cell phone protection of up to $500 a claim, after a $50 deductible, when you pay your phone bill with the card
- No foreign transaction fee
Cons
- Paying in full still costs $120 or $240 a year
- No rewards
- Limits of only $1,000 or $2,000
- Aimed only at applicants with credit scores of 620 and up
- Carrying over 57% of the limit means high credit utilization on the card, which can lower your credit score
Readers in TD’s states who’ll owe more than 57% of the limit month after month pay less in fees on TD Clear than they would in interest on a typical card. Anyone who pays in full or owes less spends less on a card with no monthly fee than on TD Clear, so weigh a low rate against rewards to pick one.
Learn more about the TD Clear Visa® Platinum Credit Card or see how it compares to the best low interest credit cards.

Editorial & Advertiser Disclosure: The editorial content on this page is not provided, commissioned, reviewed, approved, or otherwise endorsed by any advertiser. Opinions expressed here are ours alone, not those of any advertiser. The offers that appear on this site are from companies that compensate us. That compensation may influence which products we cover and where and how they appear on a page – including the order in which they appear – but it does not influence our evaluations, ratings, or opinions. We do not include every company or offer available in the marketplace.
Related: