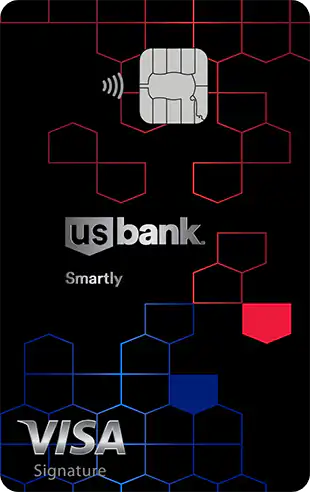
U.S. Bank Smartly™ Visa Signature® Card
- Best for: U.S. Bank customers who keep $10,000 or more in Smartly Checking
- What Sets It Apart: Checking balances, not spending categories, set its rate, up to 4%
- Rewards: 2.5%, 3%, or 4% on the first $10,000 of eligible purchases a billing cycle with $10,000, $50,000, or $100,000 in Smartly Checking or Safe Debit; 2% otherwise; 6% on prepaid hotels and car rentals in U.S. Bank’s Travel Center
- Features: Boost needs a Smartly Savings account; waives the $5 Smartly Savings and $12 Smartly Checking monthly fees
- Annual Fee: $0
- Intro APR: 0% for 12 billing cycles on purchases, and on balance transfers in the first 60 days
- APR: 18.49% to 28.49% variable
- Cost: Balance transfer fee 5% ($5 minimum); foreign transaction fee 3%; cash advance fee 5% ($10 minimum); late fee up to $41
- Credit Needed: Good to excellent
- Pros: Flat 2% with no annual fee or bank account needed; up to 4% without tracking categories; fee waivers on two U.S. Bank accounts; 0% intro APR on purchases and transfers
- Cons: Only checking balances count, and checking pays almost no interest; no welcome offer; 3% foreign transaction fee; no boost on insurance, tax, gift card, or education purchases

Get the U.S. Bank Smartly™ Visa Signature® Card if you already keep $10,000 or more in Smartly Checking. With a Smartly Savings account, that balance lifts its 2% cash back to at least 2.5% on your first $10,000 of eligible purchases each billing cycle. Don’t move savings into checking to qualify, since checking pays almost no interest.
Only balances in Smartly Checking or U.S. Bank’s checkless Safe Debit account count toward the boost, averaged over 30 days, so money in savings, a money market account, or a CD doesn’t help. Without that balance, it’s a no-fee card paying a flat 2%, while the U.S. Bank Cash+ suits readers who’d rather pick two 5% categories each quarter.
Key Features
- No annual fee
- 2% cash back on every purchase, and 6% on prepaid hotels and car rentals booked through U.S. Bank’s Travel Center
- Boost to 2.5% with $10,000, 3% with $50,000, or 4% with $100,000 in Smartly Checking or Safe Debit ($4.95 a month), plus a Smartly Savings account
- Boost limited to the first $10,000 of eligible purchases each billing cycle
- Intro APR of 0% for 12 billing cycles on purchases, and on balance transfers in the first 60 days, then 18.49% to 28.49% variable
Pros
- Flat 2% with no annual fee and no bank account needed
- Up to 4% back without tracking categories
- Waives the $12 Smartly Checking and $5 Smartly Savings monthly fees
- 0% intro APR on both purchases and balance transfers
Cons
- Only checking balances count, and checking pays almost no interest
- No welcome bonus
- 3% foreign transaction fee and 5% balance transfer fee
- No boost on insurance, tax, gift card, or education purchases
U.S. Bank customers with $10,000 already in Smartly Checking need only add a Smartly Savings account to earn at least 2.5% on up to $10,000 of eligible spending a billing cycle, more than any no-fee 2% card pays. Savers earning 4% elsewhere would forgo $400 a year on $10,000 moved into checking, more than the extra 0.5% pays on less than $80,000 a year of spending, so a no-fee 2% card with a welcome bonus suits them better.
Learn more about the U.S. Bank Smartly™ Visa Signature® Card or see how it compares to the best cash back credit cards.

Editorial & Advertiser Disclosure: The editorial content on this page is not provided, commissioned, reviewed, approved, or otherwise endorsed by any advertiser. Opinions expressed here are ours alone, not those of any advertiser. The offers that appear on this site are from companies that compensate us. That compensation may influence which products we cover and where and how they appear on a page – including the order in which they appear – but it does not influence our evaluations, ratings, or opinions. We do not include every company or offer available in the marketplace.
Related: