
Cashing out a 401k when you leave a job costs you income tax, usually a 10% penalty, and decades of growth. Left invested at a 7% average return, $10,000 at age 30 grows to about $107,000 by 65. Ask your old plan for a direct rollover into your new plan or an IRA instead.
The temptation shows up at a bad time. A job change can bring moving costs or a gap between paychecks, and the old 401k starts to look like a spare emergency fund.
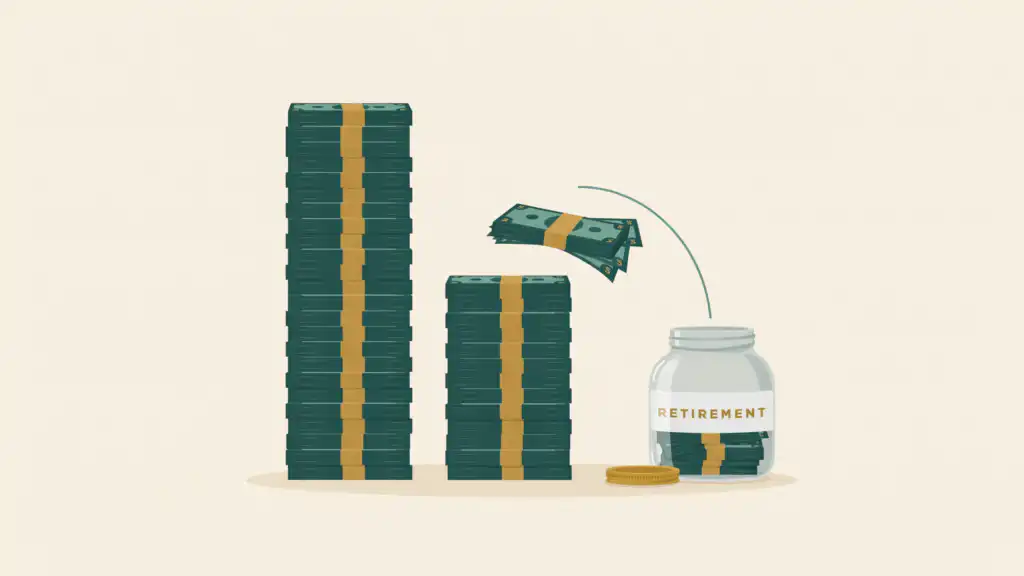
The day-one math is worse than it looks. The plan withholds 20% for federal taxes before it sends the check, and the whole withdrawal counts as income that year. In the 22% bracket, taxes plus the 10% penalty take $3,200 of a $10,000 balance before any state tax. You keep about $6,800.
So the real trade is about $6,800 in cash today against the full $10,000 kept invested and growing tax-deferred for decades.
Any of three moves keeps the money growing tax-deferred:
- Roll it into your new employer’s 401k, if that plan takes rollovers, so everything sits in one account
- Roll it into an IRA, which usually offers more investment choices
- Leave it where it is, if the old plan allows it and its fund lineup is solid
Whichever you pick, ask for a direct rollover, which sends the money straight from the old plan to the new account with nothing withheld. If the plan mails you a check instead, it withholds 20%, and you have 60 days to deposit the full balance. Any part you don’t redeposit, including the withheld 20% you’d have to cover from savings, is taxed as a withdrawal.
Small balances need speed. A plan can mail you a check for $1,000 or less without asking. It can also move a balance of up to $7,000 into an IRA it picks if you don’t give instructions, and that account is easy to lose track of. A check you didn’t ask for still starts the 60-day clock.
Choose the destination before your last day, while you can still ask HR how the old plan handles rollovers.

Editorial & Advertiser Disclosure: The editorial content on this page is not provided, commissioned, reviewed, approved, or otherwise endorsed by any advertiser. Opinions expressed here are ours alone, not those of any advertiser. The offers that appear on this site are from companies that compensate us. That compensation may influence which products we cover and where and how they appear on a page – including the order in which they appear – but it does not influence our evaluations, ratings, or opinions. We do not include every company or offer available in the marketplace.
Related: