
Pay a large tax bill with a new card whose sign-up bonus your payment earns, such as the Capital One Venture, since that bonus is worth far more than the card processing fee. A no-fee 2% card beats the cheaper IRS processor’s 1.75% fee by only $25 per $10,000, so save it for payments after the bonus.
The IRS takes card payments through two processors, Pay1040 at 1.75% of the payment and ACI Payments at 1.85%, each with a $2.50 minimum for a personal credit card. The cards below beat those fees with a sign-up bonus that one large payment can earn, or with a rate above them on every payment.
Pay the card off by its due date unless it charges 0% on new purchases. At an 18% yearly interest rate, a month’s interest on the balance is 1.5%, six times what a 2% card nets after Pay1040’s fee. And check that your card counts a tax payment as a purchase. None of the cards below excludes taxes in its rewards terms, but the Robinhood Gold Card’s rewards rules name taxes and government services among payments that may not earn points.
Sign-up bonuses a large tax payment can earn
Each charges $95 a year, and one tax payment can cover the spending its bonus requires, so the bonus makes up most of what that payment earns.
Capital One Venture Rewards Credit Card
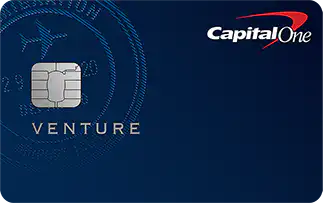
Suits a traveler with a big tax bill. It earns 2 miles per dollar, $200 toward travel on a $10,000 payment, $25 more than Pay1040’s $175 fee even without the bonus.
- Best for: Travelers who want one flat-rate miles card for all their spending
- What Sets It Apart: 2 miles per dollar on every purchase; transfers to 22 airline and hotel programs, most at one to one
- Cost: $95 annual fee; no foreign transaction fee; 19.74%, 24.74%, or 28.74% variable APR
- Features: 75,000 miles after $4,000 in purchases in 3 months; a one-time $300 Capital One Travel credit for hotels and vacation rentals in year one; 5X on Capital One Travel reservations for hotels, vacation rentals, or rental cars; up to $120 every 4 years for Global Entry or TSA PreCheck
- Pros: No bonus categories to track; a first-year offer worth up to $1,050 toward travel; transferred miles worth more than a cent each on awards that cost fewer miles than their cash price in cents
- Cons: 2X beats the no-fee VentureOne’s 1.25X after the fee only past about $12,700 a year; no airport lounge access; 5X and the $300 credit only on Capital One Travel bookings
For more information, read our full Capital One Venture Rewards Credit Card Review.
Chase Sapphire Preferred® Card
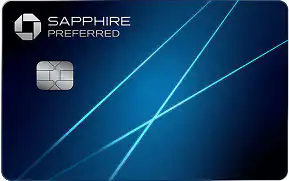
It earns 1 point per dollar on a tax payment, $100 on $10,000 and $75 short of Pay1040’s $175 fee, so it suits a taxpayer whose payment earns the bonus.
- Best for: Travelers who book at least one hotel stay a year through Chase Travel
- What Sets It Apart: A $100 annual Chase Travel hotel credit that covers the $95 fee, plus transfers to airline and hotel programs
- Cost: $95 annual fee; no foreign transaction fee; 19.49% to 27.74% variable APR; balance transfer fee 5% (min. $5)
- Features: 75,000 points after $5,000 in purchases in 3 months; 5x on Chase Travel; 3x on dining, gas, EV charging, streaming, and online grocery; up to $120 every four years for Global Entry, TSA PreCheck, or NEXUS
- Pros: $100 hotel credit exceeds the $95 fee; primary rental car coverage; trip cancellation and trip delay coverage
- Cons: Credit only on Chase Travel hotel bookings, which usually earn no hotel loyalty points; 1x on non-bonus purchases; Points Boost limited to select bookings; no intro APR
For more information, read our full Chase Sapphire Preferred® Card Review.
Bank of America® Premium Rewards® Credit Card
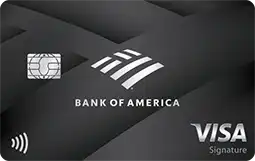
Suits a customer with $100,000 at Bank of America and Merrill, whose 50% BofA Rewards boost lifts the card to 2.25 points per dollar, $225 on a $10,000 payment against Pay1040’s $175 fee.
- Best for: Bank of America customers who’ll use a $100 yearly airline fee credit
- What Sets It Apart: Up to $100 a year in airline fee credits against a $95 fee; 2 points per $1 on travel and dining; points worth 1 cent each as cash
- Cost: $95 annual fee; no foreign transaction fee; variable APR of 19.74% to 27.74%
- Features: 60,000 points after $4,000 in purchases in the first 90 days; 1.5 points per $1 on everything else; up to $100 every four years for TSA PreCheck or Global Entry; 10% to 75% more points through BofA Rewards; trip delay, cancellation, and lost luggage coverage
- Pros: Airline credit more than covers the fee; 3 points per $1 on travel and dining with $100,000 in balances; points don’t expire while the account is open
- Cons: 1.5 points per $1 on everyday purchases without BofA Rewards; no airline or hotel transfer partners; no airline credit for tickets or on Allegiant, Spirit, or Sun Country
For more information, read our full Bank of America® Premium Rewards® Credit Card Review.
No-fee cards paying 2% on every payment
Each pays 2% with no annual fee, so a $10,000 tax payment returns $200, $25 more than Pay1040’s 1.75% fee and $15 more than ACI Payments’ 1.85%.
Citi Double Cash® Card
Fits a taxpayer with a smaller bill who wants cash back, since a single quarterly estimated payment can cover the spending its bonus requires.
- Best for: Spenders who pay in full and want one rate on everything; moving a balance to 0% for 18 months
- What Sets It Apart: 1% on each purchase plus 1% when you pay for it; 18 months at 0% on balance transfers
- Cost: $0 annual fee; 18.49% to 28.74% variable APR; 3% balance transfer fee ($5 minimum) in the first 4 months, then 5%; 3% foreign purchase fee
- Features: $200 bonus after $1,500 in purchases in 6 months; 5 points per $1 on Citi Travel hotels, car rentals, and attractions; points worth 1 cent each as cash
- Pros: No categories or caps; long balance transfer intro; cash redemptions in any amount
- Cons: No intro APR on purchases; 3% foreign purchase fee; purchases accrue interest while a transferred balance remains
For more information, read our full Citi Double Cash® Card Review.
Wells Fargo Active Cash® Card
Suits a taxpayer who needs time to pay the card off, since 0% on purchases for 12 months from account opening leaves the processing fee as the only cost of the payment.
- Best for: People who want one no-fee card for all their U.S. spending
- What Sets It Apart: Flat 2% cash rewards with 0% interest on both purchases and balance transfers for 12 months; cell phone protection when the card pays your phone bill
- Cost: $0 annual fee; 3% foreign transaction fee; a variable APR of 18.74%, 24.74%, or 28.74% after the 0% period; 3% balance transfer fee (at least $5) for 120 days, then up to 5%
- Features: Visa Signature card; $100 bonus once you spend $500 in 3 months; up to $600 per claim in cell phone protection with a $25 deductible; rewards as a card or Wells Fargo account credit, gift cards, or PayPal checkout
- Pros: No categories to track; 0% on purchases as well as balance transfers; coverage for every phone line on the bill; rewards don’t expire while the account is open
- Cons: 3% foreign transaction fee; less than a category card pays in its bonus categories; balance transfer fee during the 0% period; no coverage for a phone that goes missing
For more information, read our full Wells Fargo Active Cash® Card Review.
Synchrony Premier World Mastercard®
Works for a taxpayer who pays quarterly and wants the gain without redeeming anything, since its 2% comes off the card bill on its own after each payment.
- Best for: People who pay in full and want 2% back on everything with nothing to redeem
- What Sets It Apart: 2% cash back applied to your bill automatically, within two billing periods of each purchase
- Cost: $0 annual fee; variable APR of 20.49%, 27.49%, or 33.24%; 3% foreign transaction fee; $1.99 per paper statement on a balance over $2.50
- Features: World Mastercard; no cap or categories; prequalification before you apply
- Pros: One rate everywhere; no redemption step; no annual fee
- Cons: No 0% interest period; no cell phone, purchase, or rental car protection; uncredited cash back lost if you close the account
For more information, read our full Synchrony Premier World Mastercard® Review.
Fidelity® Rewards Visa Signature® Credit Card
Suits a Fidelity investor who’d rather invest each tax payment’s 2% than spend it, since the card deposits it into a Fidelity account.
- Best for: Fidelity customers who pay in full and want their 2% deposited into a brokerage account, IRA, health savings account, or 529 college savings plan
- What Sets It Apart: 2% paid as a deposit into up to five Fidelity accounts; automatic monthly deposits; no foreign transaction fee
- Cost: $0 annual fee; 16.74% to 26.74% variable APR; 5% balance transfer fee ($5 minimum)
- Features: 2 points per $1, worth 1 cent each as a Fidelity deposit; up to 10,000 points toward Global Entry or TSA PreCheck every four years; auto rental collision coverage up to $75,000
- Pros: Flat 2% with no categories or caps; deposits can go to a family member’s account; points don’t expire while the account is open
- Cons: Other redemptions get a different value; no sign-up bonus; IRA deposits count toward the current year’s contribution limit
For more information, read our full Fidelity® Rewards Visa Signature® Credit Card Review.
SoFi Unlimited 2% Credit Card
Suits someone who already pays $10 a month for SoFi Plus, whose 10% boost lifts the card’s 2% to 2.2%, or $220 on a $10,000 payment against Pay1040’s $175 fee.
- Best for: Readers SoFi invites who want one no-fee 2% card for home and travel
- What Sets It Apart: Full 2% as a statement credit or toward SoFi accounts and loans; no foreign transaction fee; 2.2% for SoFi Plus members
- Cost: $0 annual fee; variable purchase APR of 20.24% to 32.99%; SoFi Plus, for the boost, $10 a month
- Features: 2 points per $1, worth 1 cent each; 3% back on SoFi Travel; cell phone protection up to $800 per claim and $1,000 a year
- Pros: Same value however you redeem; no caps or redemption minimum; full 2% abroad
- Cons: Invitation only; no welcome bonus or intro APR; a late minimum payment forfeits that cycle’s rewards
For more information, read our full SoFi Unlimited 2% Credit Card Review.
A plain 2% card clears the processing fee by a small margin, so a tax payment pays off through a sign-up bonus or a boosted rate. Open the Capital One Venture before a large payment is due so the payment counts toward its bonus, or choose the Bank of America Premium Rewards instead once you keep $100,000 there.

Editorial & Advertiser Disclosure: The editorial content on this page is not provided, commissioned, reviewed, approved, or otherwise endorsed by any advertiser. Opinions expressed here are ours alone, not those of any advertiser. The offers that appear on this site are from companies that compensate us. That compensation may influence which products we cover and where and how they appear on a page – including the order in which they appear – but it does not influence our evaluations, ratings, or opinions. We do not include every company or offer available in the marketplace.
Related: