
FDIC insurance covers your checking, savings, CDs, and other deposits at an insured bank, up to $250,000 per ownership category, such as single or joint accounts. It doesn’t cover stocks, mutual funds, annuities, or crypto, even when you buy them at the bank. Confirm your bank on the FDIC’s BankFind, then total each category in its EDIE estimator.
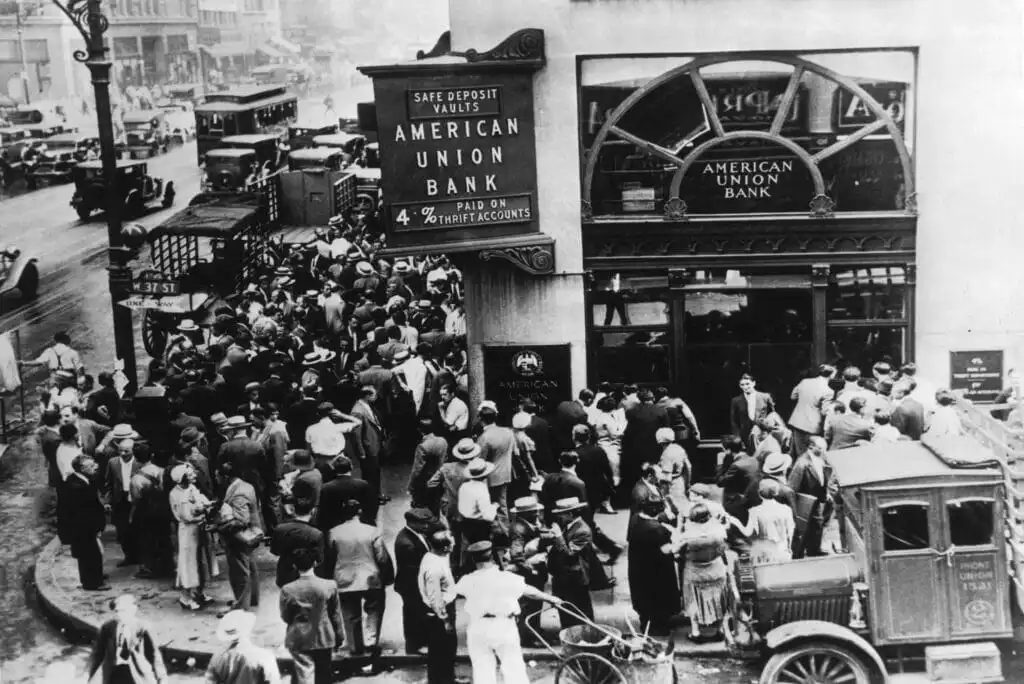
A bank with the FDIC sign at its teller windows can still hold some of your money that the FDIC won’t cover. The branch that opens your savings account may also sell you an annuity, and a CD you open later can push your total past the limit.
Deposits are insured automatically, with nothing to apply for. But the FDIC doesn’t cover bonds, life insurance, or the contents of a safe deposit box. A money market deposit account counts as a deposit, while a money market fund, despite the similar name, is an investment with no FDIC coverage.
An ownership category is the way you own an account. The common ones are single accounts in your name alone, joint accounts, retirement accounts such as IRAs, and trust accounts, which include a savings account or CD naming a beneficiary to inherit it. Each category is insured on its own, but all your accounts in one category at one bank share one limit, whether they’re checking, savings, or CDs. Opening one at another branch of the same bank doesn’t change that.
Take a saver with two accounts at one bank, both in her name alone with no beneficiary. Her savings account holds $180,000, and her CD holds $90,000. Both are single accounts, so the FDIC adds them together, and her $270,000 is $20,000 over the limit. She could name a beneficiary on the CD, which would make it a trust account with its own limit, or move $20,000 to a different insured bank.
To check your own coverage, search the FDIC’s BankFind by your bank’s name or web address to confirm it’s insured. Then enter each account’s balance and owners in EDIE, the FDIC’s Electronic Deposit Insurance Estimator, which shows what’s insured at that bank and any amount over the limit. For a money app that isn’t a bank, look up the bank behind it instead.
Leave room under each category’s limit for at least a year of interest, since interest counts toward the limit through the day a bank fails.


Subscribe and we'll send you 101 Essential Money Tips to get you started.
The 101 money moves that matter most, from the foundations to protecting what you’ve built.
Advertiser Disclosure: Many or all of the offers that appear on this site are from companies that compensate us, and some companies pay for sponsored content. That compensation may influence which products we cover and where and how they appear on a page, including the order in which they appear. We do not include every company or offer available in the marketplace.