
Get the Chase Sapphire Preferred if you want a credit line of at least $5,000 for a $95 annual fee, and add an American Express card with no preset spending limit once you need more room. Your income, debts, and credit still decide how much room you get on either one.
Under the federal ability-to-pay rule, a card issuer has to weigh your income or assets against your current debts before it opens an account or raises your credit line. It can also look at your credit reports and scores. So a premium card can raise the smallest line an issuer will give you, but it never promises a specific one.
Visa’s rules require a Visa Signature credit card, one of the network’s premium tiers, to let you carry a balance of at least $5,000. Some issuers, PenFed among them, put you on a lower tier of the same card when they approve less than $5,000. Every card here either has a minimum line, set by its issuer or by Visa, or has no preset spending limit, which means no fixed line at all. To get more room on a card you already hold, ask the issuer for a credit limit increase. If rewards matter more to you than the size of the line, choose from the best credit cards for excellent credit.
A set minimum line
Best for most people: Chase Sapphire Preferred® Card
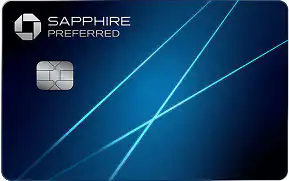
As a Visa Signature card, its line is at least $5,000, and it suits anyone who wants that minimum at a low fee, with no membership to join first.
- What Sets It Apart: A $100 annual Chase Travel hotel credit that covers the $95 fee, plus transfers to airline and hotel programs
- Welcome Offer: 75,000 points after $5,000 in purchases in 3 months
- Rewards: 5x on Chase Travel; 3x on dining, gas, EV charging, streaming, and online grocery
- Features: Up to $120 every four years for Global Entry, TSA PreCheck, or NEXUS
- Annual Fee: $95
- APR: 19.49% to 27.74% variable
- Cost: No foreign transaction fee
- Pros: $100 hotel credit exceeds the $95 fee; primary rental car coverage; trip cancellation and trip delay coverage
- Cons: Credit only on Chase Travel hotel bookings, which usually earn no hotel loyalty points; 1x on non-bonus purchases; Points Boost limited to select bookings; no intro APR
For more information, read our full Chase Sapphire Preferred® Card Review.
Members only: Flagship Premier Visa Signature® Card
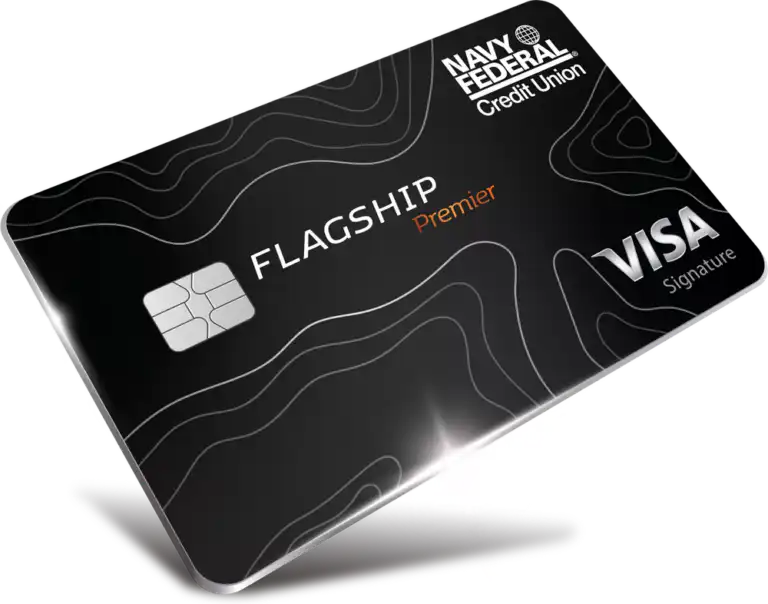
Navy Federal’s own application sets its minimum credit line at $5,000, so members can get at least that much from the credit union they already use.
- Best for: Navy Federal members who spend at least $100 a year with airlines
- What Sets It Apart: A $100 airline credit each year after $100 in airline purchases, which covers the $95 fee; 4x on travel booked anywhere; interest rates that top out at 18%
- Welcome Offer: 50,000 bonus points after $4,000 in purchases in 90 days
- Rewards: 4x on travel; 3x on dining; 1x on everything else; points worth 1 cent each as cash
- Features: Up to $120 every four years for Global Entry or TSA PreCheck
- Annual Fee: $95
- APR: 15.74% to 18.00% variable
- Cost: No balance transfer fee; no foreign transaction fee
- Eligibility: Navy Federal membership, open to service members, veterans, Defense Department civilians, and their families
- Pros: Credit covers the fee with $100 a year in airline purchases; travel bonus includes rideshares, parking, and tolls; points don’t expire while the account is open
- Cons: Members only; 1x outside travel and dining; points worth 1 cent, with no transfers to airline or hotel programs; no lounge access or trip cancellation coverage
For more information, read our full Flagship Premier Visa Signature® Card Review.
Highest minimum line: Chase Sapphire Reserve®
Chase sets its minimum line at $10,000, so approval takes income and credit that support that much, and the fee is worth paying only if you’ll use its credits.
- Best for: Frequent travelers who will use the travel credit and at least two of the dining, StubHub, and The Edit credits
- What Sets It Apart: $300 travel credit that covers almost any travel purchase; lounge access with up to two guests
- Welcome Offer: 100,000 points after $6,000 in 3 months
- Rewards: 8x on Chase Travel; 4x on flights and hotels booked direct; 3x on dining; points worth up to 2 cents each with Points Boost
- Features: Up to $500 for prepaid The Edit stays; $300 dining credit; $300 StubHub credit; up to $120 Global Entry, TSA PreCheck, or NEXUS credit every 4 years
- Annual Fee: $795
- APR: 19.74% to 28.24% variable
- Cost: No foreign transaction fees; $195 per authorized user
- Pros: Automatic $300 travel credit; Chase Sapphire Lounges and 1,300+ Priority Pass lounges; transfers to United, Southwest, and World of Hyatt; up to $75,000 in rental car coverage
- Cons: $795 fee; dining and StubHub credits paid in $150 halves; several perks end in 2027; 1 cent per point in Chase Travel without Points Boost
For more information, read our full Chase Sapphire Reserve® Review.
No preset spending limit
Amex adjusts what you can charge to your purchase, payment, and credit history, though it can assign a set limit because of your credit score, late payments, or high card balances.
Best for food spending: American Express® Gold Card
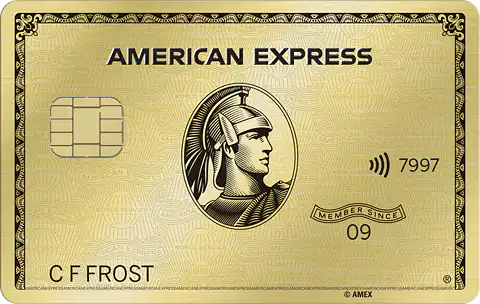
At $325 a year against the Platinum’s $895, it’s the one to pick when you spend more on restaurants and groceries than on flights.
- What Sets It Apart: 4X points at restaurants worldwide and at U.S. supermarkets; $424 a year in dining, Uber, Resy, and Dunkin’ credits
- Welcome Offer: Up to 100,000 points after $8,000 in purchases in 6 months
- Rewards: 5X on prepaid Amex Travel hotels; 4X at restaurants (up to $50,000 a year) and U.S. supermarkets (up to $25,000); 3X on flights booked with airlines or Amex Travel; Uber and Lyft rides earn 1X; 1X elsewhere
- Features: $10 a month in Uber Cash; up to $10 a month at Grubhub and select restaurants; up to $50 every six months at Resy restaurants; up to $7 a month at Dunkin’; enrollment required
- Annual Fee: $325
- APR: 19.74% to 28.74% variable on Pay Over Time balances
- Cost: No foreign transaction fee
- Pros: 4X on restaurant meals abroad with no foreign transaction fee; welcome offer worth up to $1,000 toward Amex Travel flights
- Cons: Points worth 0.6 cent as statement credits; dining credits need enrollment and don’t carry over; no airport lounge access
For more information, read our full American Express® Gold Card Review.
Best for frequent flyers: American Express Platinum Card®
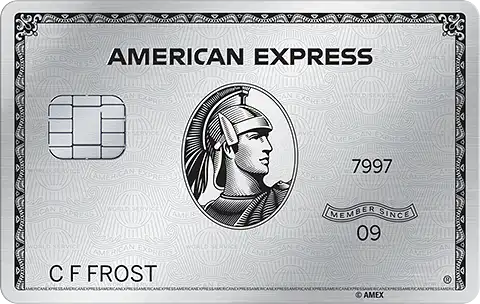
Choose it over the Gold only if you fly often enough to use its airport lounges and travel credits, since those are what its $895 fee pays for.
- What Sets It Apart: Access to more than 1,550 airport lounges; Hilton Honors Gold and Marriott Bonvoy Gold Elite status; 11 yearly credits worth $2,994 at face value
- Welcome Offer: Up to 175,000 points after $12,000 in purchases in 6 months
- Rewards: 5 points per dollar on flights booked with airlines or Amex Travel (up to $500,000 a year) and on prepaid Amex Travel hotels; 1 point elsewhere
- Features: $600 a year for prepaid Fine Hotels + Resorts or Hotel Collection stays; $200 in airline fees; $200 in Uber Cash; $219 for CLEAR+; up to $120 for Global Entry every 4 years
- Annual Fee: $895
- APR: 19.74% to 28.74% variable on Pay Over Time balances
- Cost: No foreign transaction fee; $195 per additional Platinum card
- Pros: Free entry to Centurion lounges and 10 Delta Sky Club visits a year on eligible Delta flights; up to two free guests at Priority Pass, Escape, and Plaza Premium lounges
- Cons: Credits split into monthly, quarterly, and half-year amounts; $50 per Centurion Lounge guest until $75,000 in yearly spending; 1 point per dollar on everyday spending
For more information, read our full American Express Platinum Card® Review.
A set minimum tells you the least you’ll get, while no preset limit lets your spending power adjust to how you buy and pay. Start with the Sapphire Preferred, and add an Amex card once your monthly spending nears its line.
To spread one big purchase over several months, compare the best credit cards for a large purchase.

Editorial & Advertiser Disclosure: The editorial content on this page is not provided, commissioned, reviewed, approved, or otherwise endorsed by any advertiser. Opinions expressed here are ours alone, not those of any advertiser. The offers that appear on this site are from companies that compensate us. That compensation may influence which products we cover and where and how they appear on a page – including the order in which they appear – but it does not influence our evaluations, ratings, or opinions. We do not include every company or offer available in the marketplace.
Related: