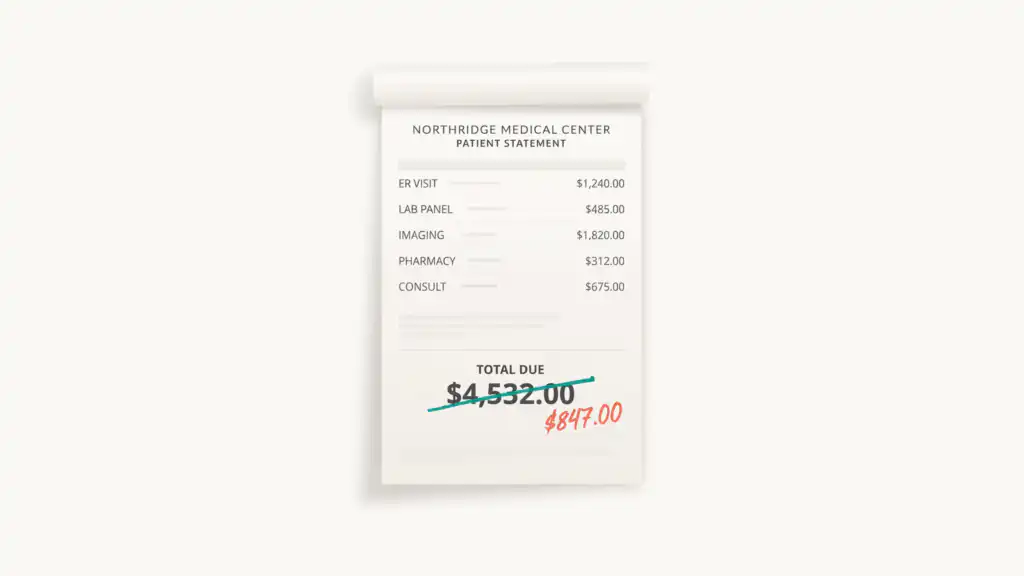

Your health insurer’s explanation of benefits isn’t a bill, but it shows what your plan says you still owe. Before paying any medical bill, match its total to that amount. If the provider asks for more than that, call its billing office with the explanation of benefits in hand before you pay.
A medical bill is supposed to come last, after your provider files a claim and your insurer sends its decision in an explanation of benefits (EOB). A wrong bill is far easier to fix before you pay it than after.
If the bill arrives first, wait for the EOB or find it on your insurer’s website. If none ever comes, call your plan to confirm the provider filed a claim.
Four numbers on the EOB matter, whatever your insurer labels them: the amount billed, the allowed amount your plan negotiated, what the plan paid, and what you owe. An in-network provider has agreed to write off the gap between billed and allowed, so a bill that charges you any of it is an error.
Matching totals catches billing errors. Reading each line catches claim errors, where the bill and the EOB agree and both are wrong. Say your plan covers an annual checkup in full, but the office codes yours as a sick visit. The EOB shows the deductible applied, and a $0 visit becomes a $200 bill that matches it exactly. When a visit that should cost nothing shows a deductible or copay, ask the billing office to recode it as preventive and resubmit the claim. A separate charge can be legitimate if you raised a new health problem during the visit.
Two more claim errors are worth catching.
- A claim from an in-network provider processed as out-of-network, which inflates your share. Ask your insurer to reprocess it.
- A denial. The EOB states the reason, and if it’s wrong, appeal it. Employer and marketplace plans allow at least 180 days from the denial notice.
Some out-of-network charges have a legal ceiling. Under the federal No Surprises Act, you owe only your in-network share for emergency care and for out-of-network specialists, such as anesthesiologists, at an in-network hospital. Before planned care, some specialists can ask you to sign away that protection, but anesthesiologists can’t.
A bill that checks out line by line is correct. Pay it, or negotiate the bill first if it’s more than you can afford.

Editorial & Advertiser Disclosure: The editorial content on this page is not provided, commissioned, reviewed, approved, or otherwise endorsed by any advertiser. Opinions expressed here are ours alone, not those of any advertiser. The offers that appear on this site are from companies that compensate us. That compensation may influence which products we cover and where and how they appear on a page – including the order in which they appear – but it does not influence our evaluations, ratings, or opinions. We do not include every company or offer available in the marketplace.
Related: