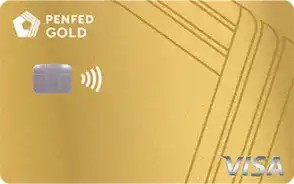
PenFed Gold Visa® Card
- Best for: Paying off a large purchase or a transferred balance before the 0% ends
- What Sets It Apart: A 0% start, then a low ongoing rate; no military tie needed to join PenFed
- Features: Cell phone protection up to $1,000 a year
- Annual Fee: $0
- Intro APR: 0% for 15 months on both purchases and balance transfers
- APR: 17.99%, variable on purchases and fixed on balance transfers
- Cost: 3% balance transfer fee; $0 foreign transaction fee
- Credit Needed: Good to excellent
- Eligibility: PenFed membership, opened with the application
- Pros: Ongoing rate below the 22.36% bank card average; can’t climb past the 18% federal credit union ceiling; no higher rate for paying late; no cash advance fee
- Cons: No rewards; same ongoing rate as PenFed’s Power Cash Rewards card, which pays 1.5% to 2% back; 0% only on balances moved within 60 days of opening

Get the PenFed Gold Visa® Card if you’ll use its 0% intro rate for 15 months to pay off a big purchase or a balance you transfer within 60 days of opening the account. After that it charges 17.99%, the same rate as PenFed’s Power Cash Rewards card, which pays cash back.
The PenFed Gold Visa Card is a no-rewards card from PenFed Credit Union, and you don’t need a military tie to get it. Anyone of age can join PenFed, which opens your membership as part of the card application.
Key Features
- 0% intro APR (annual percentage rate) for 15 months on purchases and on balance transfers made within 60 days of opening the account
- 3% fee on each balance transfer
- 17.99% APR after the intro, variable on purchases and fixed on balance transfers
- No annual, foreign transaction, or cash advance fee
- Requires good to excellent credit
Pros
- A 17.99% ongoing rate, below the 22.36% average on bank credit card accounts that paid interest in August 2026, per the Federal Reserve
- A variable rate that can’t climb past 18%, the cap the National Credit Union Administration sets for federal credit unions like PenFed through Sept. 10, 2027
- No higher rate for paying late, though a payment more than 60 days late ends the 0% intro
- Cell phone protection up to $500 a claim and $1,000 a year, less a $50 deductible, when the card pays your wireless bill
Cons
- No rewards, while PenFed’s no-annual-fee Power Cash Rewards card pays 1.5% to 2% cash back at the same 17.99% rate
- Carrying a transferred balance past the intro means new purchases are charged interest from the day you make them
- A $2 fee for each mailed paper statement, avoided with e-statements
A borrower who transfers $5,000 when opening the card and pays about $344 a month clears the balance before the 0% ends, for nothing more than the $150 transfer fee. If you pay in full every month, you’d pay no interest anyway, so choose a credit card on its rewards, such as the Power Cash Rewards card.
Learn more about the PenFed Gold Visa® Card or see how it compares to the best low interest credit cards.

Subscribe and we'll send you 101 Essential Money Tips to get you started.
The 101 money moves that matter most, from the foundations to protecting what you’ve built.
Editorial Disclosure: The editorial content on this page is not provided, commissioned, reviewed, approved, or otherwise endorsed by any advertiser. Opinions expressed here are ours alone, not those of any advertiser. Compensation does not influence our editorial evaluations, ratings, or opinions.
Advertiser Disclosure: Many or all of the offers that appear on this site are from companies that compensate us, and some companies pay for sponsored content. That compensation may influence which products we cover and where and how they appear on a page, including the order in which they appear. We do not include every company or offer available in the marketplace.