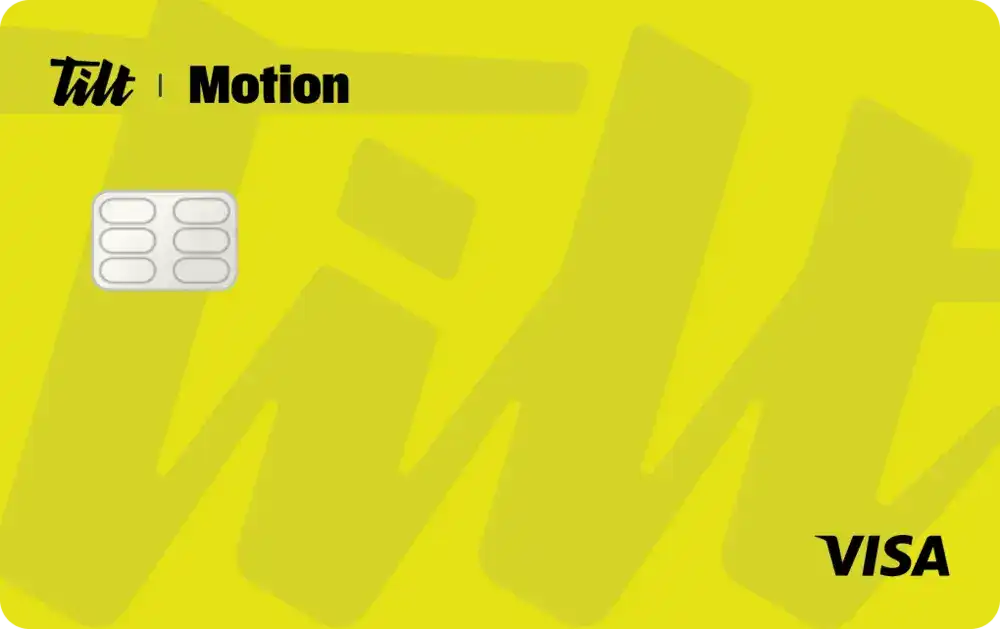
Tilt Motion VISA® Credit Card
- Best for: People with little or no credit history who pay in full each month
- What Sets It Apart: Can approve you on a linked bank account’s income and spending when you have no credit score; no security deposit
- Cost: $0 annual fee; $0 security deposit; 29.49% to 34.49% variable interest rate; late fee up to $40
- Features: 1% to 10% cash back at select merchants in the Tilt app; considered for a higher limit from four months; reports to all three credit bureaus
- Pros: No credit history required; checking whether you qualify won’t affect your credit score; no foreign transaction fee
- Cons: High interest rate; no cash back outside merchant offers; Tilt may approve you for the $59-a-year Engage instead

Get the Tilt Motion VISA® Credit Card if you have little or no credit history and will pay your balance in full every month. It charges no annual fee or deposit and can approve you without a credit score. Skip it if you’d carry a balance, since its interest rate runs 29.49% to 34.49%.
If you have no credit score, or Tilt can’t decide on your score alone, it asks you to link a bank account and judges your application on the income and spending it shows.
Tilt, the company formerly called Empower, now owns Petal, and the Motion uses the same cash back program as the Petal 1 Visa.
Key Features
- No annual fee or security deposit
- 29.49% to 34.49% variable interest rate on purchases
- 1% to 10% cash back at select merchants listed in the Tilt app, with no enrollment needed
- Considered for a higher credit limit as early as four months after opening
- Reports to all three major credit bureaus
Pros
- No credit history required
- Checking whether you qualify before applying doesn’t affect your credit score
- Six straight on-time payments of at least 15% of your statement balance earn a review for a credit limit increase of $50 or more
- No foreign transaction or returned payment fee
- Cash back doesn’t expire while your account stays open and in good standing
Cons
- High interest rate on any balance you carry
- No published range for starting credit limits
- No cash back on purchases outside its merchant offers
- Merchant offers don’t pay on purchases made through a digital wallet, such as Apple Pay, or a payment app
- Tilt weighs one application for all three of its cards and may approve you for the Tilt Engage, with a $59 annual fee, instead
It suits borrowers with steady income and little or no credit history who pay the statement balance in full each month, since the card then costs them nothing. Anyone likely to carry a balance should get a card from a federal credit union instead, whose rates the National Credit Union Administration caps at 18%.
Learn more about the Tilt Motion VISA® Credit Card or see how it compares to the best credit cards for bad credit.

Editorial & Advertiser Disclosure: The editorial content on this page is not provided, commissioned, reviewed, approved, or otherwise endorsed by any advertiser. Opinions expressed here are ours alone, not those of any advertiser. The offers that appear on this site are from companies that compensate us. That compensation may influence which products we cover and where and how they appear on a page – including the order in which they appear – but it does not influence our evaluations, ratings, or opinions. We do not include every company or offer available in the marketplace.
Related: