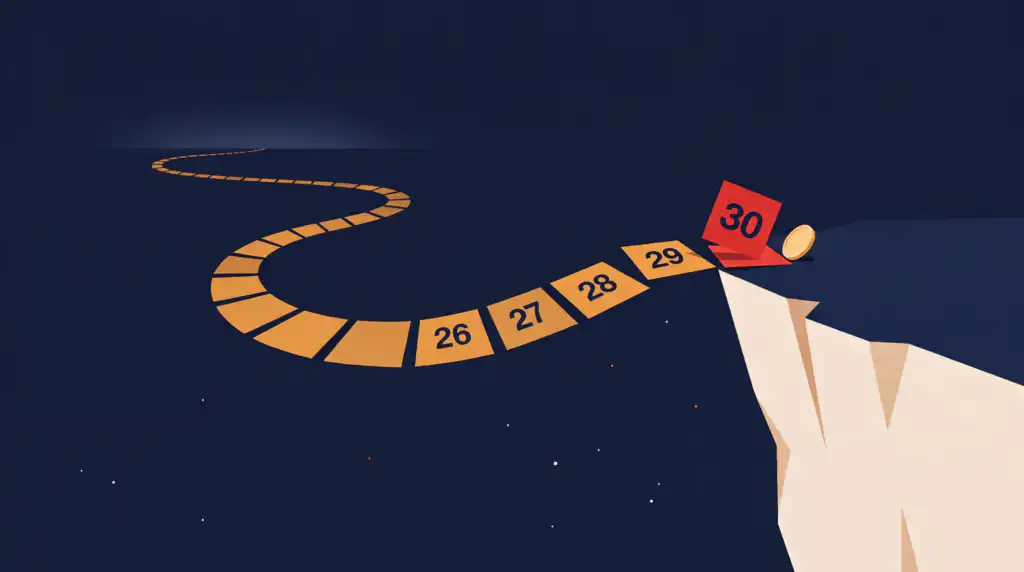

Missing your credit card’s minimum payment starts a clock. A late fee can hit right away, a credit report mark at 30 days, a penalty rate at 60, and collections near 180. Each stage is easier to stop than the one after it, so call your issuer before the due date and pay the missed minimum before day 30.
The first month is your window, because card issuers don’t report a late payment to the credit bureaus until it’s 30 days past due. A late fee can hit right after the due date, but federal rules cap it at your missed minimum payment.
Once the issuer reports the late payment, it can stay seven years on your credit report, counted from the date you first fell behind. At 60 days late, the issuer can apply any penalty rate your card carries to the balance you already owe, not just to new purchases. Around 180 days late, it writes off the account as a loss, called a charge-off, and may send or sell the debt to a collection agency. You still owe it, and the charge-off can stay on your report until seven years after the first missed payment.
Check your statement, which lists the late fee and any penalty rate a late payment can trigger. Then start with the earliest step you still have time for:
- Before the due date, call the number on your card. Ask about a hardship plan, which can lower your rate or payment, or about moving your due date to after payday.
- If you can’t cover the full minimum, pay what you can once rent, utilities, and your car payment are covered. A payment short of the minimum can still count as late, but it shrinks what you’ll need to catch up.
- Before the payment is 30 days late, pay everything that’s past due, and the issuer has no late payment to report.
- Once you’re caught up, ask the issuer to waive the late fee. In LendingTree’s 2025 survey, 89% of people who asked for a waiver got one.
- If the issuer moved your balance to a penalty rate, make the first six minimum payments due after the increase on time. Federal rules then require the issuer to restore your old rate on that balance.
Missing day 30 still leaves two deadlines, day 60 and day 180. Each deadline you beat keeps the next stage from starting.

Editorial & Advertiser Disclosure: The editorial content on this page is not provided, commissioned, reviewed, approved, or otherwise endorsed by any advertiser. Opinions expressed here are ours alone, not those of any advertiser. The offers that appear on this site are from companies that compensate us. That compensation may influence which products we cover and where and how they appear on a page – including the order in which they appear – but it does not influence our evaluations, ratings, or opinions. We do not include every company or offer available in the marketplace.
Related: