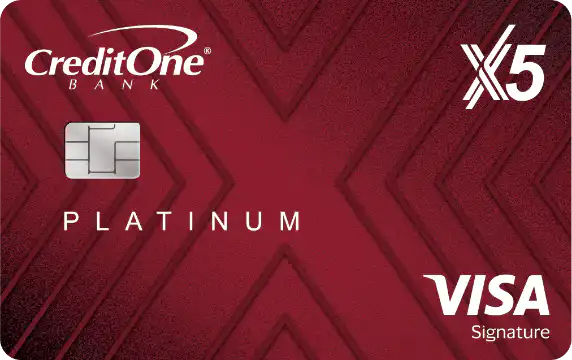
Credit One Bank® Platinum X5 Visa Signature® Card
- Best for: Average-credit cardholders who pay in full and spend $160 or more a month on gas, groceries, and phone, internet, or TV service
- What Sets It Apart: 5% cash back on gas, groceries, and mobile phone, internet, cable, and satellite TV service, on the first $5,000 each calendar year
- Cost: $95 annual fee, billed when the account opens ($8 a month on some offers); 29.74% variable APR; no foreign transaction fee
- Features: 1% cash back on other purchases; $400 minimum credit line; automatic credit line increase reviews; reports to the credit bureaus
- Pros: 5% on phone, internet, and TV bills; no foreign transaction fee; cash back doesn’t expire while the account is in good standing
- Cons: Fee billed at opening cuts your starting credit; Walmart, Target, warehouse clubs, and PayPal purchases earn 1%; 29.74% APR

Get the Credit One Bank® Platinum X5 Visa Signature® Card if you have average credit and spend at least $160 a month in its 5% categories: gas stations, supermarkets, and phone, internet, or TV service. At 5% back, that spending covers the $95 fee. Skip it if you’d carry a balance, since 29.74% interest can exceed the cash back.
Credit One recommends the Platinum X5 for average to excellent credit, and its card for weaker credit is the Platinum Visa for Rebuilding Credit. If you came here for Credit One’s Cash Back Rewards card, the bank no longer offers it.
Key Features
- $95 annual fee, billed when the account opens (some offers bill $8 a month, $96 a year)
- 5% cash back on the first $5,000 each calendar year of gasoline, grocery, mobile phone, internet, cable, and satellite TV purchases, then 1%
- 1% cash back on all other purchases
- 29.74% variable APR, the interest rate on purchases
- $400 minimum credit line, reviewed automatically for increases
Pros
- 5% on phone, internet, and TV bills as well as gas and groceries
- No foreign transaction fee on purchases made abroad
- Reports to the credit bureaus, so on-time payments build your credit history
- Cash back doesn’t expire while the account is in good standing
Cons
- When billed at opening, the fee leaves about $305 available on a $400 credit line
- Walmart, Target, warehouse clubs, and PayPal purchases earn 1%, not 5%
- The 5% stops after $5,000 of purchases in its categories each year, so it pays $250 at most
- A $1,000 balance kept all year costs about $300 in interest at 29.74%, more than the $250 the 5% can pay
Average-credit cardholders who pay in full and spend $160 a month or more in its 5% categories earn back the $95 fee, and up to $155 a year more at the $5,000 cap. If you’d carry a balance or spend less there, a no-fee card from a federal credit union costs less, since the National Credit Union Administration caps those cards’ rates at 18%, against this card’s 29.74%.
Learn more about the Credit One Bank® Platinum X5 Visa Signature® Card or see how it compares to the best credit cards for bad credit.

Editorial & Advertiser Disclosure: The editorial content on this page is not provided, commissioned, reviewed, approved, or otherwise endorsed by any advertiser. Opinions expressed here are ours alone, not those of any advertiser. The offers that appear on this site are from companies that compensate us. That compensation may influence which products we cover and where and how they appear on a page – including the order in which they appear – but it does not influence our evaluations, ratings, or opinions. We do not include every company or offer available in the marketplace.
Related: