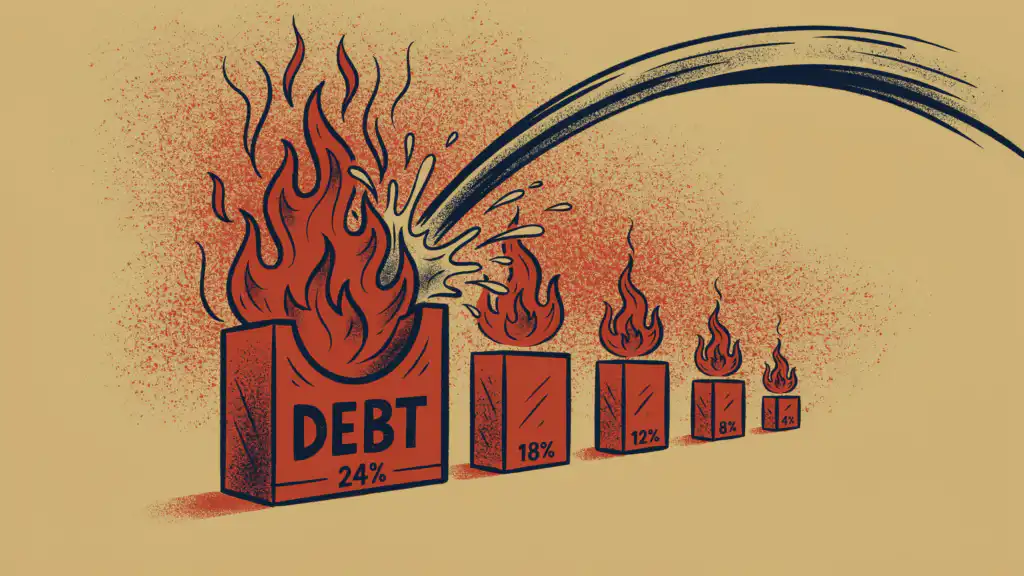

A home equity line of credit (HELOC) is secured by your house, so it charges interest at a fraction of a credit card’s rate, and moving card balances onto one can save thousands. Keep the savings by borrowing only what you owe, repaying the line on a fixed three- to five-year schedule, and leaving the paid-off cards unused.
Paying off $20,000 over four years costs about $11,300 in interest at a 24% card rate and about $3,700 at an 8.5% HELOC rate, by our math. That’s roughly $7,600 saved before any fees, or about $6,700 if the HELOC’s variable rate averages two points higher.
A HELOC also leaves your first mortgage and its rate alone, which a cash-out refinance can’t do.
The catch is the minimum payment. A HELOC usually lets you borrow for five to 10 years before a repayment period begins, and during that draw period the minimum may cover interest only. On that $20,000, it’s about $142 a month. Pay just that for four years, and you’ve spent $6,800 and still owe the full $20,000.
The rate also floats with a benchmark such as the prime rate. Like any borrowing against your home, a HELOC uses the house as collateral, so falling behind can cost you the home. And during the draw period, every dollar you repay can be borrowed again, which makes the line as easy to run up as the cards.
To keep the savings:
- Ask for a credit limit close to your card balances, and draw on it once to pay them off.
- Set autopay at a payoff amount, not the minimum. For the $20,000 example, that’s about $493 a month for four years.
- Ask whether the lender will lock your balance at a fixed rate. Expect a higher rate than the variable one, but it can’t climb.
- Compare fees along with rates. Some lenders charge closing costs or an annual fee, while others waive the up-front costs.
- Take the cleared cards out of your wallet and off every app and shopping site that stores them.
A fixed-rate personal loan usually costs more than a HELOC. At 12%, near the Federal Reserve‘s 11.9% average for two-year personal loans at banks, the same payoff costs about $5,300 in interest against the HELOC’s $3,700. But its required payment clears the debt by a set date, and it isn’t secured by your house. If you’d rather not count on willpower, that’s worth the extra $1,600.
If a HELOC still fits, compare the best home equity loan and HELOC rates.

Editorial & Advertiser Disclosure: The editorial content on this page is not provided, commissioned, reviewed, approved, or otherwise endorsed by any advertiser. Opinions expressed here are ours alone, not those of any advertiser. The offers that appear on this site are from companies that compensate us. That compensation may influence which products we cover and where and how they appear on a page – including the order in which they appear – but it does not influence our evaluations, ratings, or opinions. We do not include every company or offer available in the marketplace.
Related: