
For a trip or two abroad a year, take a card with no annual fee or foreign transaction fee, such as the U.S. Bank Altitude Connect. If you go abroad several times a year, the $95 Chase Sapphire Preferred is worth its fee for primary rental car coverage, trip insurance, and points that transfer to airlines.
Every card here charges no foreign transaction fee on purchases abroad. The ones with no annual fee are enough for an occasional trip, while the cards that charge $95 to $395 a year add travel credits, airport lounges, or broader trip insurance for people who travel often.
Most of them run on Visa or Mastercard. The exceptions are the Discover it Miles and possibly a new Capital One card, since Capital One owns Discover and issues cards on all three networks. Discover counts 185-plus countries and territories where you can use its cards, against 200-plus for Visa, so check the network’s logo on your card before you rely on it abroad. Before the trip, set up a PIN for the ticket machines and gas pumps that ask for one, and pay in the local currency whenever a terminal offers to charge you in dollars.
No annual fee
U.S. Bank Altitude® Connect Visa Signature® Card
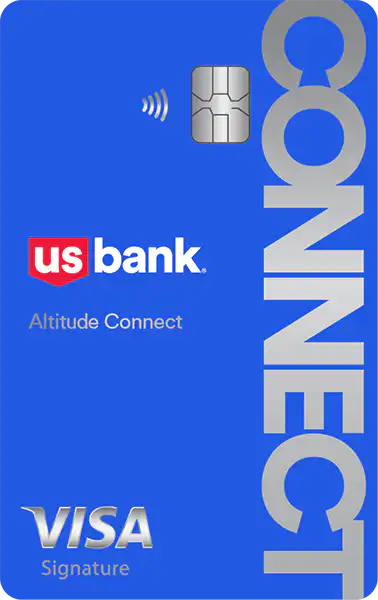
It suits travelers who fly abroad at least once a year and want no annual fee, since airfare, hotels, rental cars, and taxis paid for directly earn 4X points.
- Best for: Road-trippers and travelers who spend heavily on flights, hotels, and gas
- What Sets It Apart: Four free Priority Pass lounge visits a year and up to $100 toward TSA PreCheck or Global Entry every four years, with no annual fee
- Cost: $0 annual fee; no foreign transaction fee; 0% intro APR on purchases and on balance transfers made in the first 60 days for 15 billing cycles, then 17.74% to 27.74% variable APR; 5% balance transfer fee ($5 minimum)
- Rewards: 5X on hotels and car rentals prepaid through U.S. Bank’s Travel Center; 4X on travel; 2X on dining, streaming, and groceries (not at supercenters or warehouse clubs); 1X on everything else; 20,000 bonus points after $1,000 in purchases in the first 90 days
- Gas: 4X on the first $1,000 of gas and EV charging each quarter, then 1X; 1X on gas from warehouse clubs, supercenters, and grocery stores
- Points: Full value for travel or a deposit to a U.S. Bank checking or savings account; may be worth less as a statement credit
- Pros: Lounge visits and a TSA PreCheck or Global Entry credit with no annual fee; lounge passes when a registered flight runs two or more hours late; trip cancellation, interruption, and delay coverage when you charge the trip
- Cons: Gas bonus capped at $1,000 a quarter; points can’t move to airline or hotel programs; 1X outside the bonus categories
For more information, read our full U.S. Bank Altitude® Connect Visa Signature® Card Review.
Wells Fargo Autograph® Card
An occasional traveler earns 3X on a trip’s meals and local transport as well as the flight, from restaurants to trains, taxis, ferries, and parking.
- Best for: Households that put more than half their card spending on dining, gas, travel, transit, streaming, and phone bills
- Rewards: 3 points per dollar, with no cap, on restaurants, travel, transit, popular streaming services, and phone plans; 1 point per dollar on everything else; points worth 1 cent each as cash
- Gas: 3 points per dollar at gas stations and EV charging stations, with no cap; gas at warehouse clubs, superstores, and grocery stores may earn 1 point
- Cost: $0 annual fee; no foreign transaction fee; 0% interest on purchases for the first 12 months, then 18.74%, 24.74%, or 28.74% variable
- Features: Welcome bonus of 20,000 points, worth $200, after $1,000 in purchases in the first 3 months; cell phone protection up to $600 per claim with a $25 deductible; one-for-one point transfers to select travel loyalty programs
- Pros: Uncapped bonus categories; paying the phone bill with it earns 3 points and covers the phone; no foreign transaction fee
- Cons: 1 point per dollar on groceries; third-party delivery services and streaming billed through another company may earn 1 point; no 0% offer on balance transfers
For more information, read our full Wells Fargo Autograph® Card Review.
Chase Freedom Flex®
Since Chase dropped its foreign transaction fee in September 2026, it works as one no-fee card for home and the occasional trip, if you’ll activate its 5% categories.
- Best for: Cardholders who will activate rotating 5% categories every quarter
- What Sets It Apart: 5% on up to $1,500 in quarterly categories plus 3% on dining and drugstores, with no annual or foreign transaction fee
- Cost: $0 annual fee; 18.49% to 27.99% variable APR after a 15-month 0% intro period; balance transfer fee 3% (min. $5) for 60 days, then 5%
- Features: $250 bonus after $500 in purchases in 3 months (limited time); 5% on Chase Travel; purchase protection and extended warranty
- Pros: Up to $75 a quarter from the categories; no foreign transaction fee; points don’t expire while the account is open
- Cons: 5% requires activation each quarter; $1,500 quarterly cap; 1% base rate
For more information, read our full Chase Freedom Flex® Review.
Bank of America® Travel Rewards Credit Card
Bank of America customers who travel abroad once or twice a year get the most from it, since joining the bank’s BofA Rewards program adds at least 10% to its points.
- Best for: Travelers who want a no-annual-fee card abroad; Bank of America and Merrill customers whose balances earn a BofA Rewards boost
- What Sets It Apart: BofA Rewards adds 10% to 75% to its 1.5 points per $1; points cover travel and dining charges from the past 12 months
- Cost: $0 annual fee; no foreign transaction fees; 0% intro APR for 15 billing cycles on purchases and on balance transfers made in the first 60 days, then 17.74% to 27.74% variable; balance transfer fee 3% for the first 60 days, then 5%
- Features: 1.5 points per $1; 3 points per $1 through the Bank of America Travel Center; 25,000 bonus points for spending $1,000 in the first 90 days; points worth 1 cent toward travel and dining or 0.6 cent as cash
- Pros: No foreign transaction fee; no blackout dates; points cover dining too; points don’t expire while the account is open
- Cons: Cash worth only 0.6 cent a point; 50% and 75% boosts need $100,000 and $1 million in balances; no travel credits or point transfers
For more information, read our full Bank of America® Travel Rewards Credit Card Review.
Capital One VentureOne Rewards Credit Card
On a trip or two abroad a year, it earns miles you can turn into airline or hotel points, with no annual fee to earn back.
- Best for: Travelers who want transferable miles and no foreign transaction fee without paying an annual fee
- What Sets It Apart: Transfers to 22 airline and hotel programs, most one to one, on a card with no annual fee
- Cost: $0 annual fee; no foreign transaction fee; 0% intro interest for 15 months, then 18.74%, 24.74%, or 28.74% variable; balance transfer fee 3% for the first 15 months
- Features: 20,000 bonus miles after $500 in purchases in 3 months; 5 miles per dollar on Capital One Travel hotels, vacation rentals, and rental cars, and 1.25 on other purchases; Hertz Five Star status
- Pros: Miles worth 1 cent each toward travel; transfers to 22 airline and hotel programs; miles don’t expire while the account is open
- Cons: Trails no-fee 2% cash back cards at home if you won’t transfer miles; flights through Capital One Travel earn only 1.25 miles per dollar; no Global Entry or TSA PreCheck credit
For more information, read our full Capital One VentureOne Rewards Credit Card Review.
Capital One Savor Cash Rewards Credit Card
Built for trips spent eating out and sightseeing, since tickets to tourist attractions, theaters, zoos, and aquariums earn the same 3% as restaurant meals.
- Best for: People who spend a lot on groceries, dining, entertainment, and streaming
- What Sets It Apart: 3% back on four everyday categories with no cap and no annual fee
- Cost: $0 annual fee; no foreign transaction fee; 0% intro APR for 12 months, then 18.74%, 24.74%, or 28.74% variable APR
- Features: 3% at grocery stores and on dining, entertainment, and streaming; 8% on Capital One Entertainment tickets; 5% on hotel, vacation rental, and rental car bookings made through Capital One Travel; 1% on everything else; $200 bonus after $500 in purchases in the first 3 months
- Pros: No cap on 3% rewards; cash back in any amount that doesn’t expire while the account is open; 12 months at 0% on purchases and balance transfers
- Cons: 1% on gas and other spending; groceries at superstores, warehouse clubs, and discount stores earn 1%; needs excellent credit
For more information, read our full Capital One Savor Cash Rewards Credit Card Review.
Capital One Quicksilver Cash Rewards Credit Card
For the occasional traveler who wants cash back without categories to track, since a café bill, a train ticket, and a museum entry all earn the same 1.5%.
- Best for: People who travel abroad often and want one no-fee, flat-rate cash back card
- What Sets It Apart: Flat 1.5% cash back with no foreign transaction fee; 15 months at 0% on purchases and balance transfers
- Cost: $0 annual fee; no foreign transaction fee; 18.74%, 24.74%, or 28.74% variable APR after the 0% period; 3% fee on balances transferred in the first 15 months
- Features: $200 bonus once you spend $500 in 3 months; 5% when you book hotels, vacation rentals, and rental cars through Capital One Travel; cash back in any amount, with no expiration while the account is open
- Pros: No rotating categories to track; the full 1.5% on purchases abroad; a $200 bonus for $500 in spending
- Cons: 1.5% trails no-fee 2% cards; some cards issued on Capital One’s Discover network, accepted at fewer merchants abroad than Mastercard; 5% only through Capital One Travel
For more information, read our full Capital One Quicksilver Cash Rewards Credit Card Review.
Discover it® Miles
Take it on one trip abroad in its first year and the match doubles that trip’s miles, as long as Discover is taken where you’re going.
- Best for: Travelers who want one no-fee card for a trip or two a year, with miles they can take as cash
- What Sets It Apart: Every mile from the first year matched; no foreign transaction fee
- Cost: $0 annual fee; $0 foreign transaction fee; 0% intro rate on purchases and balance transfers for the first 15 months (3% transfer fee), then 17.74% to 26.74% variable
- Features: 1.5 miles per $1 on all purchases; 5 miles per $1 on Capital One Travel bookings of hotels, vacation rentals, and rental cars; miles worth 1 cent as cash or travel credit
- Pros: Doubled miles in year one; no fee on purchases abroad; cash out in any amount
- Cons: Acceptance abroad varies by country; no airline or hotel transfer partners of its own; no travel credits or insurance
For more information, read our full Discover it® Miles Review.
Annual fee with travel perks
Chase Sapphire Preferred® Card
Travelers who go abroad a few times a year and rent cars there get coverage that pays before their own insurance, up to $60,000 for theft or collision damage on most rentals.
- Best for: Travelers who book at least one hotel stay a year through Chase Travel
- What Sets It Apart: A $100 annual Chase Travel hotel credit that covers the $95 fee, plus transfers to airline and hotel programs
- Cost: $95 annual fee; no foreign transaction fee; 19.49% to 27.74% variable APR; balance transfer fee 5% (min. $5)
- Features: 75,000 points after $5,000 in purchases in 3 months; 5x on Chase Travel; 3x on dining, gas, EV charging, streaming, and online grocery; up to $120 every four years for Global Entry, TSA PreCheck, or NEXUS
- Pros: $100 hotel credit exceeds the $95 fee; primary rental car coverage; trip cancellation and trip delay coverage
- Cons: Credit only on Chase Travel hotel bookings, which usually earn no hotel loyalty points; 1x on non-bonus purchases; Points Boost limited to select bookings; no intro APR
For more information, read our full Chase Sapphire Preferred® Card Review.
Citi Strata Premier® Card
A Mastercard for frequent travelers who want one card for home too, since it pays 3X on airfare and hotels and at supermarkets and gas stations.
- Best for: Households that spend heavily at restaurants, supermarkets, and gas stations and will transfer points to airlines
- What Sets It Apart: 3X points on dining, including takeout and delivery, plus supermarkets, gas, airfare, and hotels; transfers to 15 airline and five hotel programs; $100 off one Citi Travel hotel stay a year
- Cost: $95 annual fee; no foreign transaction fee; 19.74% to 27.74% variable interest rate
- Features: 60,000 bonus points after $4,000 in purchases in the first 3 months; 10X on Citi Travel bookings of hotels, car rentals, and attractions; 3X on air travel, hotels booked elsewhere, restaurants, supermarkets, gas stations, and electric-vehicle charging; 1X on everything else
- Pros: No cap on points; most airline transfers at 1 mile per point; trip delay, trip cancellation, lost luggage, and rental car coverage
- Cons: Points worth 1 cent each through Citi Travel; 1X outside the bonus categories; warehouse clubs and discount stores don’t earn the supermarket or gas bonus
For more information, read our full Citi Strata Premier® Card Review.
Wells Fargo Autograph Journey℠ Card
With points worth a cent each, its extra points over the no-fee Autograph plus a $50 airline credit cover the $95 fee once you spend about $1,500 a year each with hotels and airlines.
- Best for: Travelers who book hotel stays and flights directly with the hotel or airline
- What Sets It Apart: 5 points per dollar on hotels and 4 on airlines booked directly; a $50 airline credit each year; trip cancellation and lost baggage coverage
- Cost: $95 annual fee; no foreign transaction fee; a variable APR of 19.74%, 25.74%, or 28.74%; 3% balance transfer fee (at least $5) for 120 days, then up to 5%
- Features: Visa Signature card; bonus of 60,000 points after $4,000 in purchases in the first 3 months; 3 points per dollar on restaurants and other travel; up to $1,000 per claim in cell phone protection with a $25 deductible; points worth 1 cent each as cash or transferable one for one to airline partners
- Pros: Top rates on hotels and flights booked directly; trip cancellation coverage up to $15,000 per traveler; no foreign transaction fee; points that don’t expire while the account is open
- Cons: 3 points, not 5, on hotels booked through travel sites; 1 point on gas, transit, streaming, and phone plans; secondary trip and U.S. rental car coverage; bonus points that may not post on mobile wallet purchases
For more information, read our full Wells Fargo Autograph Journey℠ Card Review.
Bank of America® Premium Rewards® Credit Card
If you bank with Bank of America and fly abroad a few times a year, its travel insurance covers trip delays and lost luggage and extends to emergency evacuation.
- Best for: Bank of America customers who’ll use a $100 yearly airline fee credit
- What Sets It Apart: Up to $100 a year in airline fee credits against a $95 fee; 2 points per $1 on travel and dining; points worth 1 cent each as cash
- Cost: $95 annual fee; no foreign transaction fee; variable APR of 19.74% to 27.74%
- Features: 60,000 points after $4,000 in purchases in the first 90 days; 1.5 points per $1 on everything else; up to $100 every four years for TSA PreCheck or Global Entry; 10% to 75% more points through BofA Rewards; trip delay, cancellation, and lost luggage coverage
- Pros: Airline credit more than covers the fee; 3 points per $1 on travel and dining with $100,000 in balances; points don’t expire while the account is open
- Cons: 1.5 points per $1 on everyday purchases without BofA Rewards; no airline or hotel transfer partners; no airline credit for tickets or on Allegiant, Spirit, or Sun Country
For more information, read our full Bank of America® Premium Rewards® Credit Card Review.
Capital One Venture Rewards Credit Card
Suits travelers abroad several times a year who’d rather earn 2X miles on everything than plan their spending around bonus categories.
- Best for: Travelers who want one flat-rate miles card for all their spending
- What Sets It Apart: 2 miles per dollar on every purchase; transfers to 22 airline and hotel programs, most at one to one
- Cost: $95 annual fee; no foreign transaction fee; 19.74%, 24.74%, or 28.74% variable APR
- Features: 75,000 miles after $4,000 in purchases in 3 months; a one-time $300 Capital One Travel credit for hotels and vacation rentals in year one; 5X on Capital One Travel reservations for hotels, vacation rentals, or rental cars; up to $120 every 4 years for Global Entry or TSA PreCheck
- Pros: No bonus categories to track; a first-year offer worth up to $1,050 toward travel; transferred miles worth more than a cent each on awards that cost fewer miles than their cash price in cents
- Cons: 2X beats the no-fee VentureOne’s 1.25X after the fee only past about $12,700 a year; no airport lounge access; 5X and the $300 credit only on Capital One Travel bookings
For more information, read our full Capital One Venture Rewards Credit Card Review.
Capital One Venture X Rewards Credit Card
Frequent international travelers get the most from it, since it’s a Visa Infinite card with access to Capital One Lounges and more than 1,300 Priority Pass lounges worldwide.
- Best for: Frequent travelers who’ll book at least $300 a year through Capital One Travel
- What Sets It Apart: $300 yearly travel credit and 10,000 anniversary miles worth $400 toward travel, more than the $395 fee
- Cost: $395 annual fee; no foreign transaction fees; 19.74%, 24.74%, or 28.74% variable APR
- Features: 75,000 bonus miles after $4,000 in purchases in 3 months; 2X miles on all purchases; 5X on Capital One Travel flights and vacation rentals; 10X on Capital One Travel hotels and rental cars; up to $120 back for Global Entry or TSA PreCheck every 4 years
- Pros: Lounge access for the primary cardholder at Capital One Lounges and Priority Pass lounges; miles worth 1 cent each toward travel; transfers to more than 15 airline and hotel programs
- Cons: Travel credit works only on Capital One Travel bookings and expires each year; lounge guests cost $45 per adult at Capital One Lounges and $35 at Priority Pass; $125 a year for each authorized user’s lounge access
For more information, read our full Capital One Venture X Rewards Credit Card Review.
For one or two trips a year, a no-fee Visa or Mastercard does the job, and U.S. Bank’s Altitude Connect adds lounge visits and trip coverage at no annual cost. Step up to a $95 card once you’re abroad several times a year and will use its credits and insurance.

Editorial & Advertiser Disclosure: The editorial content on this page is not provided, commissioned, reviewed, approved, or otherwise endorsed by any advertiser. Opinions expressed here are ours alone, not those of any advertiser. The offers that appear on this site are from companies that compensate us. That compensation may influence which products we cover and where and how they appear on a page – including the order in which they appear – but it does not influence our evaluations, ratings, or opinions. We do not include every company or offer available in the marketplace.
Related: