
Pick the credit card that pays the most where your household already spends. That’s a warehouse club’s card if you buy groceries at Costco, Sam’s Club, or BJ’s, the card for Walmart, Target, or Amazon if one of them is your main store, or the Blue Cash Preferred for supermarkets. Put the rest on a flat 2% card.
The average household spent $6,491 on groceries and $2,503 on gas in 2025, the Bureau of Labor Statistics reports. Earning 5% on those groceries rather than 1% is worth about $260 a year, so the cards here are grouped by where a family shops.
A partner or teen added as an authorized user gets a card on your account, and their purchases add to your rewards, but only you owe the balance. A joint credit card makes both of you owe it.
Supermarkets & streaming
Best for big grocery bills: Blue Cash Preferred® Card from American Express
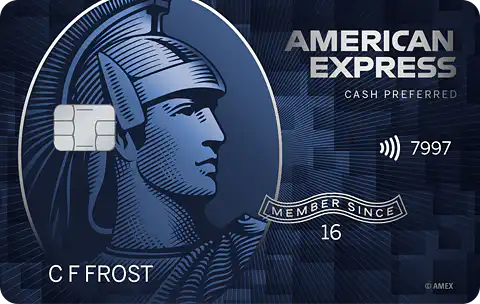
At supermarkets, it pays the highest grocery rate here. For a family spending over $200 a month there, its extra over a flat 2% card covers the $95 fee.
- What Sets It Apart: 6% on U.S. groceries, up to $6,000 a year, and on select U.S. streaming
- Welcome Offer: Up to $300 back after $3,000 in purchases in the first 6 months; your amount shown before you accept
- Rewards: 6% back on the first $6,000 spent each year at U.S. supermarkets (then 1%) and on select U.S. streaming subscriptions; 3% at U.S. gas stations with no yearly cap; 3% on transit, rideshare included, with no cap
- Features: Up to $10 a month back on Disney+, Hulu, or ESPN with enrollment
- Annual Fee: $0 intro the first year, then $95
- Intro APR: 0% for 12 months on purchases and on balance transfers requested in the first 60 days
- APR: 19.74% to 28.74% variable
- Cost: Balance transfer fee 3% (min. $5); 2.7% foreign transaction fee
- Pros: Up to $360 a year from groceries at 6%; uncapped 3% on gas and transit; first year free
- Cons: 6% grocery rate stops at $6,000 a year; superstores and warehouse clubs don’t count as supermarkets
For more information, read our full Blue Cash Preferred® Card from American Express Review.
Best for Disney families: Disney® Inspire Visa® Card
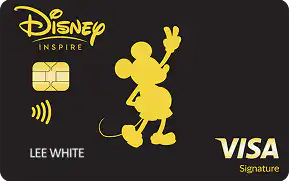
The only card here built around Disney suits a family that streams Disney+, Hulu, or ESPN and visits a U.S. Disney park or resort every year.
- What Sets It Apart: Yearly Disney credits that can more than cover the fee
- Welcome Offer: A $300 Disney gift card on approval plus a $200 statement credit after $1,000 in purchases within 3 months of opening the account
- Rewards: 10% on Disney+, Hulu, and ESPN bought directly; 3% at gas stations and most Disney locations in the U.S.; 2% at restaurants and grocery stores; 1% elsewhere
- Features: A $10 monthly credit when you spend $10 on Disney+, Hulu, or ESPN, activated yearly; $100 a year after $200 in U.S. Disney park tickets; 200 Rewards Dollars a year after $2,000 in U.S. Disney resort stays and cruises
- Annual Fee: $149
- APR: 18.49% to 27.99% variable
- Cost: No foreign transaction fee
- Pros: Up to $220 a year in streaming and park ticket credits, $71 more than the fee; 10% on Disney streaming; Rewards Dollars good for flights booked directly with any airline
- Cons: Streaming alone nets a $29 cost, where the no-fee Blue Cash Everyday pays up to $84; rewards only for U.S. Disney purchases or airfare
For more information, read our full Disney® Inspire Visa® Card Review.
Warehouse clubs
Each card here needs a membership at its club to apply, and its rewards are redeemed only at that club, so pick the card for the club your family already belongs to.
Best for gas & dining: Costco Anywhere Visa® Card by Citi
Costco families that drive a lot and eat out do best with it, since it pays more at the pump and at restaurants than on Costco purchases themselves.
- What Sets It Apart: 4% to 5% on gas and 3% on dining with no annual fee beyond the membership
- Rewards: 5% at Costco and 4% at other eligible stations and EV chargers on the first $7,000 a year combined, then 1%; 3% on restaurants and eligible travel; 2% on other Costco and Costco.com purchases; 1% on everything else
- Features: Doubles as your Costco membership card; no fee for authorized users who hold a Costco membership
- Annual Fee: $0
- APR: 18.99% to 26.99% variable
- Cost: No foreign transaction fee
- Eligibility: A paid Costco membership, $65 a year for Gold Star or $130 for Executive
- Pros: 3% on dining and travel; no foreign transaction fee
- Cons: Rewards come once a year as a certificate redeemable only at U.S. Costco warehouses by Dec. 31; 1% outside its categories; gas at Walmart, Sam’s Club, Kroger, and other excluded stations earns 1%
For more information, read our full Costco Anywhere Visa® Card by Citi Review.
Best for frequent fill-ups: Sam's Club® Mastercard®
This one suits a Sam’s Club household that buys a lot of gas. Its 3% in the club goes to Plus members alone, so Club members get it mostly for the 5% on gas.
- What Sets It Apart: 5% on gas with no annual fee beyond the membership; Sam’s Club Plus members’ own 2% back stacks with the card’s club rate for 5% at the club
- Rewards: 5% at almost any gas station and on electric vehicle charging on the first $6,000 a year, then 1%; 3% on dining and takeout; 3% at Sam’s Club for Plus members, 1% for Club members; 1% on everything else
- Features: Sam’s Cash for club or online purchases, your membership renewal, or cash at a club’s member services desk
- Annual Fee: $0
- APR: 20.40% or 28.40% variable
- Eligibility: A Sam’s Club membership, $60 a year for Club or $120 for Plus
- Pros: 5% on gas at almost any station; Sam’s Cash posted within one or two billing cycles, with no minimum to spend it
- Cons: Rewards good only at Sam’s Club or as cash at a club; forfeited if your membership ends; 1% on gas past $6,000 a year
For more information, read our full Sam's Club® Mastercard® Review.
Best for big BJ's bills: BJ's One+® Mastercard®
Pick this BJ’s card once your household spends $250 a month at BJ’s, the point where 5% back instead of 3% on the BJ’s One covers the extra $60 a year that Club+ costs.
- What Sets It Apart: 5% back at BJ’s with no cap; 15¢ off a gallon at BJ’s Gas; rewards that never expire and can go toward the Club+ fee
- Rewards: 5% back on most BJ’s purchases in-club, online, and in the app; 2% back outside BJ’s
- Features: Rewards added monthly and usable from $10
- Annual Fee: $0
- APR: 19.99% or 28.49% variable
- Cost: No foreign transaction fee
- Eligibility: A BJ’s Club+ membership, $120 a year plus any sales tax
- Pros: Lifts Club+’s 2% to 5% at BJ’s; triples Club+’s 5¢-a-gallon gas discount to 15¢; no foreign transaction fee
- Cons: Rewards usable only at BJ’s; Club+ costs $60 a year more than Club; no welcome bonus
For more information, read our full BJ's One+® Mastercard® Review.
Best for small BJ's bills: BJ's One® Mastercard®
Under $250 a month at BJ’s, this card is the one to get, since it needs only the $60 Club membership and still pays 3% there.
- What Sets It Apart: 3% back in BJ’s rewards at BJ’s, plus a per-gallon discount at BJ’s Gas, with no annual fee
- Rewards: 3% back on most BJ’s purchases; 1.5% back everywhere else
- Features: 10 cents off each gallon at BJ’s Gas; rewards that never expire while the card is open; up to four authorized users
- Annual Fee: $0
- APR: 19.99% or 28.49% variable
- Eligibility: A BJ’s Club membership, generally $60 a year
- Pros: 3% at BJ’s tops a 2% flat-rate card; rewards can pay the membership fee; no foreign transaction fee
- Cons: Rewards spendable only at BJ’s; 1.5% elsewhere trails 2% cards; no rewards on BJ’s Gas purchases
For more information, read our full BJ's One® Mastercard® Review.
Walmart, Target & Amazon
Best for Walmart shoppers: OnePay CashRewards World Mastercard®
It fits a Walmart household, groceries included. Walmart+ lifts its rate from 3% to 5% there, and that extra 2% covers the $98 annual membership at about $410 a month of Walmart spending.
- What Sets It Apart: Unlimited 5% back at Walmart with Walmart+, in stores, at Walmart gas stations, on Walmart.com, and in the Walmart app; 3% without Walmart+
- Welcome Offer: $35 at account opening plus 3% back outside Walmart for the first 90 days, on applications made by December 31, 2026
- Rewards: 5% at Walmart with Walmart+; 3% at Walmart without it; 1.5% on all other purchases; points worth 1 cent each
- Features: Points redeemed in the OnePay app as a statement credit or a OnePay Cash deposit; prequalification with no credit score impact
- Annual Fee: $0
- APR: 20.49% or 30.99% variable
- Cost: No foreign transaction fee
- Pros: No cap on 5%; 5% on the Walmart+ renewal fee when the card pays it
- Cons: 1.5% outside Walmart and from third-party sellers there; 5% requires Walmart+ ($98 a year on the annual plan); lower APR expected for only a limited number of applicants
For more information, read our full OnePay CashRewards World Mastercard® Review.
Best for no membership fee: Target Circle™ Credit Card
Target households that pay in full each month should carry it, and it’s the only store card here that needs no paid membership for its top rate.
- What Sets It Apart: 5% off most Target and Target.com purchases at checkout; free shipping on orders under $35; 30 extra days for returns
- Welcome Offer: $50 in Target Circle Rewards after $50 of qualifying purchases within 60 days of approval
- Rewards: 5% on top of Target Circle deals
- Features: Target Circle 360 for $49 a year instead of $99; 5% off restaurant and travel gift cards sold at Target
- Annual Fee: $0
- APR: 28.45% variable
- Pros: Discount comes off at the register, with nothing to redeem; no annual fee; free shipping on small orders
- Cons: Works only at Target; interest on a carried balance soon outweighs the discount; no discount on prescriptions, Target GiftCards, or prepaid cards
For more information, read our full Target Circle™ Credit Card Review.
Best for Amazon shoppers: Prime Visa
For a Prime household whose shopping runs through Amazon.com and Whole Foods Market, groceries included, it’s the pick.
- What Sets It Apart: 5% for Prime members on Amazon, Whole Foods, and Chase Travel spending, with no fee for the card itself
- Welcome Offer: $150 Amazon gift card on approval
- Rewards: 5% back at Amazon, Whole Foods Market, and Chase Travel; 2% at gas stations, restaurants, and local transit; 1% on other purchases; rotating Prime Card Bonus offers of 10% or more on select Amazon items
- Features: Purchase protection and extended warranty
- Annual Fee: $0
- APR: 18.99% to 27.74% variable
- Cost: No foreign transaction fees; Prime membership needed for 5% ($139 a year or $14.99 a month for the standard plan)
- Pros: No annual card fee; rewards spendable at Amazon checkout as soon as the next day
- Cons: 5% rate requires Prime; 1% on purchases outside its categories; no 5% on Amazon Pay or international Amazon sites
For more information, read our full Prime Visa Review.
Everywhere else
Best beside a store card: Wells Fargo Active Cash® Card
Use it when your household’s spending is spread across many stores, or as the second card beside a store card for purchases that card rewards at 1% or 1.5%.
- What Sets It Apart: 2% on everything with no annual fee, plus an intro period on purchases and transfers alike; cell phone protection when the card pays your phone bill
- Welcome Offer: $100 bonus once you spend $500 in 3 months
- Rewards: Flat 2% cash rewards
- Features: Visa Signature card; up to $600 per claim in cell phone protection with a $25 deductible; rewards as a card or Wells Fargo account credit, gift cards, or PayPal checkout
- Annual Fee: $0
- Intro APR: 0% interest on purchases and balance transfers for 12 months
- APR: 18.74%, 24.74%, or 28.74% variable after the 0% period
- Cost: 3% balance transfer fee (at least $5) for 120 days, then up to 5%
- Pros: No categories to track; 0% on purchases as well as balance transfers; coverage for every phone line on the bill; rewards don’t expire while the account is open
- Cons: 3% foreign transaction fee; less than a category card pays in its bonus categories; balance transfer fee during the 0% period; no coverage for a phone that goes missing
For more information, read our full Wells Fargo Active Cash® Card Review.
The right card for your household pays the most at the store that gets the biggest share of your budget. Start with a flat 2% card, then add your main store’s card, or the Blue Cash Preferred once supermarket spending tops $200 a month.
For more cards judged on grocery rewards alone, compare the best credit cards for groceries.

Subscribe and we'll send you 101 Essential Money Tips to get you started.
The 101 money moves that matter most, from the foundations to protecting what you’ve built.
Editorial Disclosure: The editorial content on this page is not provided, commissioned, reviewed, approved, or otherwise endorsed by any advertiser. Opinions expressed here are ours alone, not those of any advertiser. Compensation does not influence our editorial evaluations, ratings, or opinions.
Advertiser Disclosure: Many or all of the offers that appear on this site are from companies that compensate us, and some companies pay for sponsored content. That compensation may influence which products we cover and where and how they appear on a page, including the order in which they appear. We do not include every company or offer available in the marketplace.