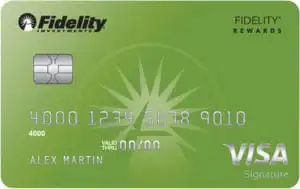
Fidelity® Rewards Visa Signature® Credit Card
- Best for: Fidelity customers who pay in full and want their 2% deposited into a brokerage account, IRA, health savings account, or 529 college savings plan
- What Sets It Apart: 2% paid as a deposit into up to five Fidelity accounts; automatic monthly deposits; no foreign transaction fee
- Cost: $0 annual fee; 16.74% to 26.74% variable APR; 5% balance transfer fee ($5 minimum)
- Features: 2 points per $1, worth 1 cent each as a Fidelity deposit; up to 10,000 points toward Global Entry or TSA PreCheck every four years; auto rental collision coverage up to $75,000
- Pros: Flat 2% with no categories or caps; deposits can go to a family member’s account; points don’t expire while the account is open
- Cons: Other redemptions get a different value; no sign-up bonus; IRA deposits count toward the current year’s contribution limit

Get the Fidelity® Rewards Visa Signature® Credit Card if you’re already a Fidelity customer. Its 2% back comes only as a deposit to an eligible Fidelity account, such as a brokerage account or IRA, and it can make those deposits automatically each month. Without a Fidelity account, choose a 2% card that pays cash.
The card earns 2 points per $1 on eligible purchases, each worth 1 cent as a deposit, so $1,500 a month in purchases would add $360 a year to your Fidelity account. Elan Financial Services issues the card, and you can get it without a Fidelity account, but deposits go only into one that’s already open and funded.
Key Features
- No annual fee and a variable interest rate (APR) of 16.74% to 26.74%, depending on your credit
- Deposits into as many as five eligible Fidelity accounts, yours or a family member’s, among them a Fidelity brokerage account, IRA, health savings account, 529 college savings plan, or Cash Management Account
- Automatic monthly deposits, or deposits whenever you choose
- Auto rental collision coverage up to $75,000 when you pay with the card and decline the rental company’s coverage
- Up to 10,000 points ($100) for a Global Entry or TSA PreCheck application fee paid with the card, once every four years
Pros
- A flat 2% with no categories or caps
- No foreign transaction fee
- Points that don’t expire while the account is open
Cons
- Points used for travel, gift cards, merchandise, or statement credits get a different value than a Fidelity deposit
- No sign-up bonus on Fidelity’s standard application
- IRA deposits count toward the current year’s contribution limit
- Deposits to a brokerage account or IRA arrive as cash, so investing them is still up to you
Fidelity customers who pay in full each month get 2% back, deposited into accounts they already use, without an annual fee or a fee on purchases abroad. If you don’t have a Fidelity account, the Citi Double Cash Card also pays 2% with no annual fee, as cash back you can take as a statement credit or a deposit to your bank account.
Learn more about the Fidelity® Rewards Visa Signature® Credit Card or see how it compares to the best cash back credit cards.

Editorial & Advertiser Disclosure: The editorial content on this page is not provided, commissioned, reviewed, approved, or otherwise endorsed by any advertiser. Opinions expressed here are ours alone, not those of any advertiser. The offers that appear on this site are from companies that compensate us. That compensation may influence which products we cover and where and how they appear on a page – including the order in which they appear – but it does not influence our evaluations, ratings, or opinions. We do not include every company or offer available in the marketplace.
Related: