
Dave Ramsey’s Baby Steps put your money goals in a simple order, and the debt snowball’s quick wins keep you going. But when Baby Step 2 tells you to pause investing, keep contributing enough to your 401(k) to collect the full employer match. It’s worth more than the interest a faster payoff saves.
“Yes, that even includes your employer match,” Ramsey Solutions says of the pause on its Baby Step 2 page. Most families take 18 to 24 months to finish that step, the company says, and retirement saving doesn’t restart until Step 4.
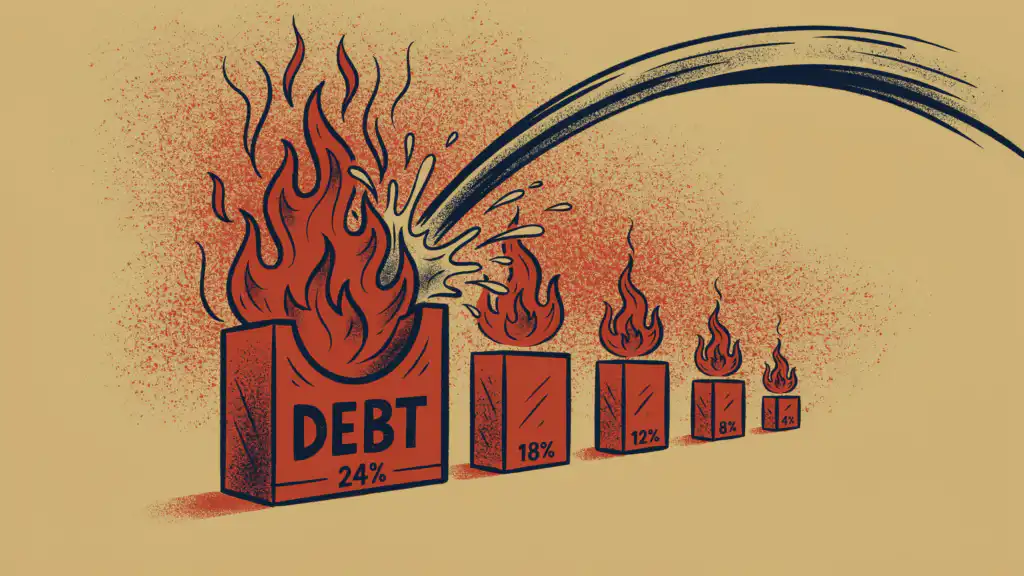
The rest of the plan holds up. The debt snowball sends every spare dollar to your smallest balance first, whatever its rate. That can cost more interest than paying the highest rate first, but each closed account is a win you can see. A 2012 Journal of Marketing Research study of debt settlement clients found that the more accounts people closed, the likelier they were to finish the program.
The match pause is the exception. Ramsey Solutions’ case for it compares debt charging 7% to 20% or more with the 10% to 12% investing might earn in a good year. A 50% match adds 50 cents to every dollar you contribute up to its cap, more than double a year’s interest on a 20% balance, and a match you skip is never paid later. That’s why our financial order of operations puts the full match ahead of extra debt payments.
Ramsey Solutions lists the seven steps this way:
- Save $1,000 for a starter emergency fund
- Pay off all debt except the mortgage, smallest balance first
- Save three to six months of expenses
- Invest 15% of household income for retirement
- Save for your kids’ college
- Pay off the house early
- Build wealth and give
Follow them as written, but in Step 2, contribute just enough to collect the full match and send every other spare dollar to the snowball. On a $60,000 salary with a 50% match on the first 6% of pay, you’d put in $300 a month and your employer would add $1,800 a year. Skip those contributions for two years and you forfeit $3,600 of free money before any growth. Keep the match running through Step 3, too.
At Step 4, raise your retirement saving to the 15% of household income the plan calls for, with the match on top.

Editorial & Advertiser Disclosure: The editorial content on this page is not provided, commissioned, reviewed, approved, or otherwise endorsed by any advertiser. Opinions expressed here are ours alone, not those of any advertiser. The offers that appear on this site are from companies that compensate us. That compensation may influence which products we cover and where and how they appear on a page – including the order in which they appear – but it does not influence our evaluations, ratings, or opinions. We do not include every company or offer available in the marketplace.
Related: