Chase Freedom Flex®
- Best for: Cardholders who will activate rotating 5% categories every quarter
- What Sets It Apart: 5% on up to $1,500 in quarterly categories plus 3% on dining and drugstores, with no annual or foreign transaction fee
- Cost: $0 annual fee; 18.49% to 27.99% variable APR after a 15-month 0% intro period; balance transfer fee 3% (min. $5) for 60 days, then 5%
- Features: $250 bonus after $500 in purchases in 3 months (limited time); 5% on Chase Travel; purchase protection and extended warranty
- Pros: Up to $75 a quarter from the categories; no foreign transaction fee; points don’t expire while the account is open
- Cons: 5% requires activation each quarter; $1,500 quarterly cap; 1% base rate

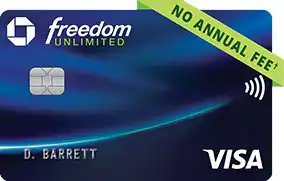
Get the Chase Freedom Flex® if you’ll activate its 5% categories every quarter, because those categories pay up to $75 a quarter on the first $1,500 you spend in them. Otherwise get the Freedom Unlimited, which pays 1.5% where the Flex pays 1% but charges a 3% foreign transaction fee the Flex doesn’t.
The Chase Freedom Flex® is a no-annual-fee cash back card that pays 5% on the first $1,500 you spend each quarter in rotating categories, but only if you activate them by the quarter’s deadline. Outside those categories it pays 1%, apart from higher rates on dining, drugstores, and travel booked through Chase Travel.
Key Features
- $0 annual fee and no foreign transaction fee
- 5% back on the first $1,500 you spend each quarter in the categories you activate, then 1%
- 5% on Chase Travel bookings, 3% at restaurants and drugstores, and 1% on everything else
- $250 bonus after $500 in purchases in the first 3 months, a limited-time offer up from $200
- 0% intro APR on purchases and balance transfers for 15 months, then 18.49% to 27.99% variable
Pros
- Up to $75 a quarter from the 5% categories ($1,500 at 5%)
- Points that don’t expire while the account is open and can move to another card in your household that earns the same Chase points
- Purchase protection for 120 days (90 in New York), up to $500 per item, plus extended warranty coverage
- Trip cancellation and interruption coverage up to $1,500 per traveler
Cons
- Miss the activation deadline and you lose that quarter’s 5% rate
- The 5% rate stops after $1,500 in combined category purchases each quarter
- 1% base rate trails the Chase Freedom Unlimited® at 1.5%
- Balance transfer fee rises from 3% ($5 minimum) to 5% after the first 60 days
Cardholders who activate on schedule and steer purchases into the 5% categories earn as much as $3.50 more per $100 of those purchases than with the 1.5% Freedom Unlimited, before the cap. Everyone else should get the Unlimited, which pays 50 cents more per $100 wherever the Flex pays 1%, unless they often buy abroad, since it charges a 3% fee there that the Flex doesn’t.
Learn more about the Chase Freedom Flex® or see how it compares to the best cash back credit cards.

Editorial & Advertiser Disclosure: The editorial content on this page is not provided, commissioned, reviewed, approved, or otherwise endorsed by any advertiser. Opinions expressed here are ours alone, not those of any advertiser. The offers that appear on this site are from companies that compensate us. That compensation may influence which products we cover and where and how they appear on a page – including the order in which they appear – but it does not influence our evaluations, ratings, or opinions. We do not include every company or offer available in the marketplace.
Related: