
Choose a no-annual-fee credit card by the spending you already do. Take the Wells Fargo Active Cash for a flat 2% if you won’t track categories, the Blue Cash Everyday if groceries and gas lead your bills, or the VentureOne if you’d rather earn travel miles than cash.
With no annual fee to earn back, a card’s rewards are profit from the first purchase, as long as you pay the bill in full. A card with a fee beats a no-fee card only when its extra rewards or credits outearn the fee on spending you already do, which is how to judge whether an annual fee is worth paying.
The cards below are grouped by how they pay, so start with the group that pays most where your money already goes. If you’ll spend abroad, a card with no foreign transaction fee matters more than the rewards rate, since a 3% fee costs more than a flat 2% card earns. Frequent flyers and loyal hotel guests may do better with an airline card or a hotel card from the brand they already use.
One flat rate on everything
Wells Fargo Active Cash® Card
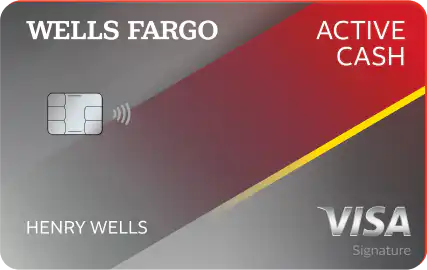
Anyone who won’t track categories gets 2% cash rewards on every purchase, with nothing to activate or choose and no cap on what it earns.
- Best for: People who want one no-fee card for all their U.S. spending
- What Sets It Apart: 2% on everything with no annual fee, plus an intro period on purchases and transfers alike; cell phone protection when the card pays your phone bill
- Welcome Offer: $100 bonus once you spend $500 in 3 months
- Rewards: Flat 2% cash rewards
- Features: Visa Signature card; up to $600 per claim in cell phone protection with a $25 deductible; rewards as a card or Wells Fargo account credit, gift cards, or PayPal checkout
- Annual Fee: $0
- Intro APR: 0% interest on purchases and balance transfers for 12 months
- APR: 18.74%, 24.74%, or 28.74% variable after the 0% period
- Cost: 3% balance transfer fee (at least $5) for 120 days, then up to 5%
- Pros: No categories to track; 0% on purchases as well as balance transfers; coverage for every phone line on the bill; rewards don’t expire while the account is open
- Cons: 3% foreign transaction fee; less than a category card pays in its bonus categories; balance transfer fee during the 0% period; no coverage for a phone that goes missing
For more information, read our full Wells Fargo Active Cash® Card Review.
Citi Double Cash® Card
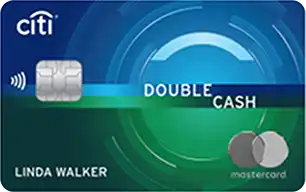
Someone moving a balance from another card gets a low introductory rate on the transfer but not on purchases, so wait to shop with it until that balance is paid off.
- Best for: Spenders who pay in full and want one rate on everything; moving a balance to 0% for 18 months
- What Sets It Apart: 2% on everything, half when you buy and half when you pay; 18 months at 0% on balance transfers
- Welcome Offer: $200 bonus after $1,500 in purchases in 6 months
- Rewards: 5 points per $1 on Citi Travel hotels, car rentals, and attractions; 1% on each purchase plus 1% when you pay for it; points worth 1 cent each as cash
- Features: Cash redemptions in any amount, by statement credit or direct deposit
- Annual Fee: $0
- Intro APR: 0% interest for 18 months from account opening on balances transferred in the first 4 months
- APR: 18.49% to 28.74% variable
- Cost: 3% balance transfer fee ($5 minimum) in the first 4 months, then 5%; 3% foreign purchase fee
- Pros: No categories or caps; long balance transfer intro
- Cons: No intro APR on purchases; 3% foreign purchase fee; purchases accrue interest while a transferred balance remains
For more information, read our full Citi Double Cash® Card Review.
Higher rates in set categories
American Express Blue Cash Everyday® Card
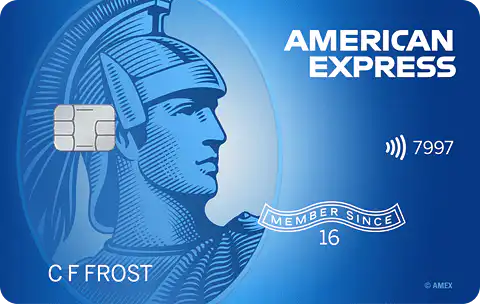
A family whose U.S. supermarket, gas station, and online shopping bills each stay under $500 a month earns 3% on all of them, since each category’s 3% covers the first $6,000 a year.
- Best for: Everyday spenders who want bonus cash back on groceries, gas, and online shopping without an annual fee
- What Sets It Apart: 3% in three everyday categories that stay the same all year, with no annual fee
- Welcome Offer: Up to $200 back after $2,000 in purchases in the first 6 months; amount varies by applicant
- Rewards: 3% at U.S. supermarkets and on U.S. online retail purchases, each on the first $6,000 a year, then 1%; 3% at U.S. gas stations on the first $6,000 a year, then 1%; 1% on other purchases
- Features: Up to $7 a month in Disney+, Hulu, or ESPN streaming credits with enrollment; purchase protection; cash back usable at Amazon.com checkout
- Annual Fee: $0
- Intro APR: 0% for 15 months on purchases and balance transfers
- APR: 19.74% - 28.74% variable after the intro period
- Cost: 2.7% foreign transaction fee
- Pros: No annual fee; separate $6,000 cap per category; no minimum to redeem
- Cons: 1% outside the bonus categories; 2.7% foreign transaction fee; balance transfers only in the first 60 days
For more information, read our full American Express Blue Cash Everyday® Card Review.
Citi Strata® Card
Home cooks who also drive or ride transit earn 3 points per dollar at supermarkets, gas and EV charging stations, and on select transit, plus one category they choose.
- Best for: Households that spend more at supermarkets, gas stations, and on transit than on purchases outside its bonus categories
- What Sets It Apart: 3x on transit and on a category you choose, with no annual fee
- Welcome Offer: 20,000 bonus points after $1,000 in purchases in the first 3 months
- Rewards: 5x on Citi Travel hotels, car rentals, and attractions; 3x at supermarkets, gas and EV charging stations, select transit, and one chosen category; 2x at restaurants; 1x on everything else
- Features: ThankYou points usable for gift cards and Citi Travel, or transferable to airline and hotel programs
- Annual Fee: $0
- Intro APR: 0% for 15 months on purchases and balance transfers
- APR: 18.74% to 28.74% variable
- Cost: 3% balance transfer fee for 4 months, then 5%; 3% foreign transaction fee
- Pros: 3x on everyday costs; category you can switch each quarter; 15 months at 0% on purchases and balance transfers
- Cons: 1x outside bonus categories; reduced airline transfer rates; no supermarket bonus at superstores or warehouse clubs; 3% foreign transaction fee
For more information, read our full Citi Strata® Card Review.
Capital One Savor Cash Rewards Credit Card
Households that spend heavily on dining, groceries, entertainment, and popular streaming services earn an uncapped 3% on all four, though groceries bought at Walmart or Target earn 1%.
- Best for: People who spend a lot on groceries, dining, entertainment, and streaming
- What Sets It Apart: 3% back on four everyday categories with no cap and no annual fee
- Welcome Offer: $200 bonus after $500 in purchases in the first 3 months
- Rewards: 8% on Capital One Entertainment tickets; 5% on hotel, vacation rental, and rental car bookings made through Capital One Travel; 3% at grocery stores and on dining, entertainment, and streaming; 1% on everything else
- Features: Cash back in any amount that doesn’t expire while the account is open
- Annual Fee: $0
- Intro APR: 0% for 12 months on purchases and balance transfers
- APR: 18.74%, 24.74%, or 28.74% variable
- Cost: 3% balance transfer fee; no foreign transaction fee
- Credit Needed: Excellent, as Capital One lists it
- Pros: No cap on 3% rewards; 12 months at 0% on purchases and balance transfers
- Cons: 1% on gas and other spending; groceries at superstores, warehouse clubs, and discount stores earn 1%
For more information, read our full Capital One Savor Cash Rewards Credit Card Review.
U.S. Bank Altitude® Go Visa Signature® Card
Frequent diners earn 4 points per dollar at restaurants, takeout and delivery included, on up to $2,000 a quarter, with points at full value when deposited into an eligible U.S. Bank account.
- Best for: People who eat out or order takeout often and want no annual fee; U.S. Bank checking or savings customers
- What Sets It Apart: 4 points per dollar on dining, takeout, and restaurant delivery with no annual fee
- Welcome Offer: 20,000 bonus points after $1,000 in purchases in the first 90 days
- Rewards: 4 points per dollar on the first $2,000 of dining each quarter, then 1 point; 2 points per dollar at supermarkets, gas stations, and EV charging stations, and on eligible streaming services; 1 point per dollar on everything else
- Features: $15 streaming credit each year
- Annual Fee: $0
- Intro APR: 0% for 15 billing cycles on purchases and on balances transferred within 60 days of opening
- APR: 17.74% to 27.74% variable
- Cost: 5% balance transfer fee ($5 minimum); 3% foreign transaction fee
- Pros: No annual fee; dining bonus covers takeout and restaurant delivery; $15 streaming credit; 15 billing cycles at 0% interest
- Cons: Dining bonus stops at $2,000 a quarter; 3% foreign transaction fee; statement credits can be worth less than a U.S. Bank deposit; Walmart, Target, and warehouse clubs earn 1 point on groceries and gas
For more information, read our full U.S. Bank Altitude® Go Visa Signature® Card Review.
Wells Fargo Autograph® Card
Commuters and road-trippers who eat out more than they cook earn 3 points per dollar on restaurants, gas, transit, travel, streaming, and phone plans, but just 1 point at supermarkets.
- Best for: Households that put more than half their card spending on dining, gas, travel, transit, streaming, and phone bills
- What Sets It Apart: 3 points per dollar in six everyday categories, with no cap and no annual fee
- Welcome Offer: Bonus of 20,000 points, worth $200, after $1,000 in purchases in the first 3 months
- Rewards: 3 points per dollar, with no cap, on restaurants, travel, transit, popular streaming services, and phone plans; 3 points per dollar at gas stations and EV charging stations, with no cap; 1 point per dollar on everything else
- Features: Cell phone protection up to $600 per claim with a $25 deductible; one-for-one point transfers to select travel loyalty programs
- Annual Fee: $0
- Intro APR: 0% interest on purchases for the first 12 months
- APR: 18.74%, 24.74%, or 28.74% variable
- Cost: No foreign transaction fee
- Pros: Uncapped bonus categories; paying the phone bill with it earns 3 points and covers the phone; no foreign transaction fee
- Cons: 1 point per dollar on groceries; third-party delivery services and streaming billed through another company may earn 1 point; no 0% offer on balance transfers
For more information, read our full Wells Fargo Autograph® Card Review.
Chase Freedom Unlimited®
Diners who won’t juggle categories outearn a flat 2% card once restaurants and drugstores pass a third of their spending, since those earn 3% and everything else 1.5%.
- Best for: Cardholders who want one no-fee card with nothing to activate and who eat out often
- What Sets It Apart: Fixed reward rates: at least 1.5% back on everything, more at restaurants, drugstores, and on Chase Travel
- Welcome Offer: $200 bonus after $500 in purchases in 3 months
- Rewards: 1.5% on every purchase, 3% at restaurants and drugstores, and 5% through Chase Travel, with no rotating categories
- Features: Purchase protection and extended warranty; trip cancellation coverage
- Annual Fee: $0
- Intro APR: 0% for 15 months on purchases and balance transfers
- APR: 18.49% to 27.99% variable
- Cost: Balance transfer fee 3% (min. $5) for 60 days, then 5%; 3% foreign transaction fee
- Pros: Nothing to activate; 3% on dining including takeout; points don’t expire while the account is open
- Cons: 1.5% base trails 2% flat-rate cards; 3% foreign transaction fee; 5% travel only through Chase Travel
For more information, read our full Chase Freedom Unlimited® Review.
Categories you pick or that rotate
Bank of America® Customized Cash Rewards Credit Card
Spenders whose biggest bill shifts with the season can move its 3% category once a month, from gas during summer road trips to online shopping before the holidays.
- Best for: Households with steady spending in one category, such as gas, dining, or online shopping; Bank of America customers whose balances earn a BofA Rewards boost
- What Sets It Apart: A 3% category you pick and can change once a month; BofA Rewards adds 10% to 75%, up to 5.25% in the category
- Welcome Offer: $200 bonus after $1,000 in purchases in the first 90 days; 6% in the category the first year
- Rewards: 3% in one category: gas and EV charging by default, or online shopping, dining, travel, drug stores, or home improvement; 2% at grocery stores and wholesale clubs; both on up to $2,500 combined a quarter, then 1%
- Features: Cash back in any amount; rewards don’t expire while the account is open
- Annual Fee: $0
- Intro APR: 0% for 15 billing cycles on purchases and on balance transfers made in the first 60 days
- APR: 17.74% to 27.74% variable
- Cost: Balance transfer fee 3% for the first 60 days, then 5%; 3% foreign transaction fee
- Pros: Phone, internet, cable, and streaming bills count as online shopping
- Cons: $2,500 quarterly cap shared with groceries and wholesale clubs; 1% past the cap; 3% foreign transaction fee
For more information, read our full Bank of America® Customized Cash Rewards Credit Card Review.
U.S. Bank Cash+® Visa Signature® Card
People with big utility or phone bills can earn 5% on them by picking home utilities and cell phone as their two categories each quarter, on up to $2,000 combined.
- Best for: People whose regular spending falls in two of its 5% categories and who will choose them every quarter
- What Sets It Apart: Two 5% categories you pick each quarter from 12, home utilities, cell phone providers, and ground transportation among them
- Welcome Offer: $200 bonus after $1,000 in purchases in the first 90 days
- Rewards: 5% on the first $2,000 a quarter in your two categories; 5% on prepaid travel booked in U.S. Bank’s Travel Center; 2% on grocery stores, restaurants, or gas and EV charging, whichever you pick; 1% on everything else
- Features: Category picks open 45 days before each quarter, with text or email reminders
- Annual Fee: $0
- Intro APR: 0% for 15 billing cycles on purchases and on balance transfers made in the first 60 days
- APR: 17.99% to 28.24% variable
- Cost: 5% balance transfer fee ($5 minimum); 3% foreign transaction fee
- Credit Needed: Good to excellent, as U.S. Bank says
- Pros: Up to $400 a year at 5%; 5% choices for monthly bills; 15 billing cycles at 0% on purchases
- Cons: 1% on everything until you choose each quarter’s categories; 1% outside your picks; cash back expires 36 months after you earn it
For more information, read our full U.S. Bank Cash+® Visa Signature® Card Review.
Discover it® Cash Back
New cardholders willing to activate each quarter get the most from year one, since Discover matches all cash back earned that year, turning the 1% on other purchases into 2%.
- Best for: People who’ll activate rotating 5% categories every quarter and pay their balance in full
- What Sets It Apart: A first-year match of every dollar of cash back, plus rotating 5% categories, with no annual or foreign transaction fee
- Welcome Offer: $200 statement credit after $500 in purchases in 3 months when you apply through Discover’s page; Cashback Match doubles all the cash back you earn in your first year, with no cap
- Rewards: 5% on up to $1,500 a quarter in categories you activate; 5% on Capital One Travel bookings of hotels, vacation rentals, rental cars, and activities, and on Capital One Entertainment tickets; 1% on all other purchases
- Features: No late fee the first time you pay late
- Annual Fee: $0
- Intro APR: 0% on purchases and balance transfers for 15 months
- APR: 18.74% to 28.74% variable
- Cost: 3% fee on balances transferred in the first 15 months; no foreign transaction fee
- Pros: First-year match on every purchase; categories that cover everyday spending
- Cons: Categories need activating every quarter; 5% capped at $1,500 of purchases a quarter; 1% on everything else after year one; 5% categories only at U.S. merchants
For more information, read our full Discover it® Cash Back Review.
Chase Freedom Flex®
Those who’ll activate its 5% categories every quarter and also eat out earn 3% at restaurants and drugstores year-round, with no foreign transaction fee on trips abroad.
- Best for: Cardholders who will activate rotating 5% categories every quarter
- What Sets It Apart: Quarterly 5% bonus categories plus 3% at restaurants and drugstores, with no annual or foreign transaction fee
- Welcome Offer: $250 bonus after $500 in purchases in 3 months (limited time)
- Rewards: 5% on Chase Travel; 5% on up to $1,500 in quarterly categories plus 3% on dining and drugstores
- Features: Purchase protection and extended warranty
- Annual Fee: $0
- Intro APR: 0% for 15 months on purchases and balance transfers
- APR: 18.49% to 27.99% variable
- Cost: Balance transfer fee 3% (min. $5) for 60 days, then 5%
- Pros: Up to $75 a quarter from the categories; no foreign transaction fee; points don’t expire while the account is open
- Cons: 5% requires activation each quarter; $1,500 quarterly cap; 1% base rate
For more information, read our full Chase Freedom Flex® Review.
Travel points or miles
Capital One VentureOne Rewards Credit Card
Travelers who want airline miles more than cash earn 1.25 miles per dollar that transfer to Capital One’s airline and hotel partners.
- Best for: Travelers who want transferable miles and no foreign transaction fee without paying an annual fee
- What Sets It Apart: Mostly one-to-one miles transfers to 22 travel programs with no annual fee
- Welcome Offer: 20,000 bonus miles after $500 in purchases in 3 months
- Rewards: 5 miles per dollar on Capital One Travel hotels, vacation rentals, and rental cars, and 1.25 on other purchases
- Features: Hertz Five Star status
- Annual Fee: $0
- Intro APR: 0% for 15 months on purchases and balance transfers
- APR: 18.74%, 24.74%, or 28.74% variable
- Cost: Balance transfer fee 3% for the first 15 months; no foreign transaction fee
- Credit Needed: Excellent for the bonus and 0% period; the good-credit version has neither
- Pros: Miles worth 1 cent each toward travel; transfers to 22 airline and hotel programs; miles don’t expire while the account is open
- Cons: Trails no-fee 2% cash back cards at home if you won’t transfer miles; flights through Capital One Travel earn only 1.25 miles per dollar; no Global Entry or TSA PreCheck credit
For more information, read our full Capital One VentureOne Rewards Credit Card Review.
Bank of America® Travel Rewards Credit Card
Bank of America customers who join the free BofA Rewards program see the card’s 1.5 points per dollar rise by 10%, or by 50% with $100,000 in combined Bank of America and Merrill balances.
- Best for: Travelers who want a no-annual-fee card abroad; Bank of America and Merrill customers whose balances earn a BofA Rewards boost
- What Sets It Apart: Up to 75% more points for Bank of America customers with big balances; points cover travel and dining charges from the past 12 months
- Welcome Offer: 25,000 bonus points for spending $1,000 in the first 90 days
- Rewards: 3 points per $1 through the Bank of America Travel Center; 1.5 points per $1; BofA Rewards adds 10% to 75% to its 1.5 points per $1; points worth 1 cent toward travel and dining or 0.6 cent as cash
- Features: No blackout dates; points don’t expire while the account is open
- Annual Fee: $0
- Intro APR: 0% for 15 billing cycles on purchases and on balance transfers made in the first 60 days
- APR: 17.74% to 27.74% variable
- Cost: Balance transfer fee 3% for the first 60 days, then 5%; no foreign transaction fees
- Pros: No foreign transaction fee; points cover dining too
- Cons: Cash worth only 0.6 cent a point; 50% and 75% boosts need $100,000 and $1 million in balances; no travel credits or point transfers
For more information, read our full Bank of America® Travel Rewards Credit Card Review.
Discover it® Miles
Occasional travelers who want simple rewards get the most in year one, since Discover matches every mile earned that year, so each dollar returns 3 cents in cash or travel credit.
- Best for: Travelers who want one no-fee card for a trip or two a year, with miles they can take as cash
- What Sets It Apart: Every mile from the first year matched; no foreign transaction fee
- Welcome Offer: Discover Match, which doubles every mile you earn in your first 365 days, with no cap
- Rewards: 5 miles per $1 on Capital One Travel bookings of hotels, vacation rentals, and rental cars; 1.5 miles per $1 on all purchases; miles worth 1 cent as cash or travel credit
- Features: Miles that never expire, with no minimum to redeem
- Annual Fee: $0
- Intro APR: 0% on purchases and balance transfers for the first 15 months
- APR: 17.74% to 26.74% variable
- Cost: 3% balance transfer fee; $0 foreign transaction fee
- Pros: Doubled miles in year one; no fee on purchases abroad; cash out in any amount
- Cons: Acceptance abroad varies by country; no airline or hotel transfer partners of its own; no travel credits or insurance
For more information, read our full Discover it® Miles Review.
U.S. Bank Altitude® Connect Visa Signature® Card
Road-trippers earn 4 points per dollar on gas and EV charging, on up to $1,000 a quarter, and 4 on travel, from a card that charges no foreign transaction fee.
- Best for: Road-trippers and travelers who spend heavily on flights, hotels, and gas
- What Sets It Apart: Priority Pass visits and a PreCheck credit without an annual fee
- Welcome Offer: 20,000 bonus points after $1,000 in purchases in the first 90 days
- Rewards: 5X on hotels and car rentals prepaid through U.S. Bank’s Travel Center; 4X on travel; 4X on the first $1,000 of gas and EV charging each quarter, then 1X; 2X on dining, streaming, and groceries; 1X on everything else
- Features: Four free Priority Pass visits a year; up to $100 toward TSA PreCheck or Global Entry every four years; trip cancellation, interruption, and delay coverage
- Annual Fee: $0
- Intro APR: 0% on purchases and on balance transfers made in the first 60 days for 15 billing cycles
- APR: 17.74% to 27.74% variable
- Cost: 5% balance transfer fee ($5 minimum); no foreign transaction fee
- Pros: Lounge visits and a TSA PreCheck or Global Entry credit with no annual fee; lounge passes when a registered flight runs two or more hours late
- Cons: Gas bonus capped at $1,000 a quarter; points can’t move to airline or hotel programs; 1X outside the bonus categories
For more information, read our full U.S. Bank Altitude® Connect Visa Signature® Card Review.
Bilt Blue Card
Renters earn points on rent paid through Bilt with no transaction fee, and the rate climbs as their other spending on the card grows toward the full rent.
- Best for: Renters who want points on rent without an annual fee; homeowners paying a mortgage through Bilt
- What Sets It Apart: No-fee rent and mortgage rewards of 0.5X to 1.25X, set by your other card spending each billing cycle; points that transfer to airlines and hotels
- Welcome Offer: $100 in Bilt Cash at account opening
- Rewards: 4% back in Bilt Cash in place of the rent steps; 3X on linked Lyft rides and hotels booked through Bilt’s travel portal; 2X on flights booked there; 1X on purchases
- Features: No card fee on rent; rent stays off your credit line
- Annual Fee: $0
- APR: 26.99% to 34.99% variable
- Cost: No foreign transaction fees
- Pros: One-for-one transfers to most of 26 airline and hotel partners
- Cons: 250 points on rent below 25% in other card spending; 1X on most purchases; Bilt Cash over $100 expires each year; no set value per point
For more information, read our full Bilt Blue Card Review.
The right no-fee card is the one whose top rate applies to spending you already do. Sort last month’s purchases by category, then apply for the card here that pays the most on your biggest one.

Editorial & Advertiser Disclosure: The editorial content on this page is not provided, commissioned, reviewed, approved, or otherwise endorsed by any advertiser. Opinions expressed here are ours alone, not those of any advertiser. The offers that appear on this site are from companies that compensate us. That compensation may influence which products we cover and where and how they appear on a page – including the order in which they appear – but it does not influence our evaluations, ratings, or opinions. We do not include every company or offer available in the marketplace.
Related: