Tilt Engage
- Best for: Applicants Tilt won’t approve for its no-fee Motion; building credit without a security deposit
- What Sets It Apart: Tilt weighs bank account data when a credit score alone isn’t enough to decide
- Rewards: 1% to 10% cash back at select merchants
- Features: Reports to all three major credit bureaus; credit line reviews from month four
- Annual Fee: $59, added to your balance before your first purchase
- APR: 29.49% to 34.49% variable
- Cost: No foreign transaction fee
- Credit Needed: No credit history required
- Pros: No security deposit; prequalifying doesn’t affect your credit score
- Cons: Fee takes about a fifth of a $300 line; same cash back as the no-fee Tilt Motion; cash back only at select merchants

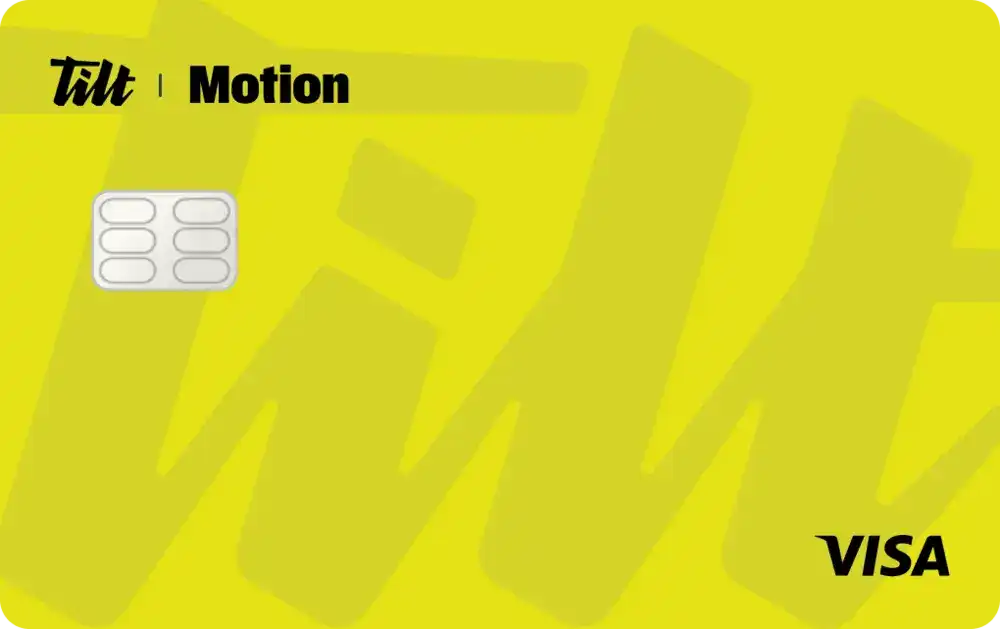
Take the Tilt Engage if it’s the card Tilt offers you and you can’t spare a refundable deposit for a no-fee secured card. Its $59 annual fee buys an unsecured card that Tilt reports to all three credit bureaus, and it pays the same 1% to 10% cash back at select merchants as Tilt’s no-fee Motion.
The Tilt Engage is a Visa credit card for people with little credit history or a damaged score. Petal is now part of Tilt, and the Engage took the place of the Petal 1 Rise with the same $59 annual fee and the same 1% to 10% cash back at select merchants.
Key Features
- $59 annual fee, added to your balance before your first purchase, so in Tilt’s own example a $300 line starts with $241 to spend
- 29.49% to 34.49% variable APR, the interest rate on balances you carry, set by your credit when you open the account
- 1% to 10% cash back at select merchants, listed in the Tilt app, which you redeem as credits against your balance
- A review for at least $50 more credit after six on-time payments in a row, each 15% or more of the statement balance
- Reports to all three major credit bureaus
Pros
- No security deposit or credit history required
- Checking whether you prequalify doesn’t affect your credit score
- Tilt weighs your bank account data when you have no credit score or your score alone isn’t enough to decide
- Credit line reviews start as early as month four
- No foreign transaction fee
Cons
- The fee takes about a fifth of a $300 line before you buy anything
- A fee you don’t get back, unlike a secured card’s deposit
- Same cash back as the no-fee Tilt Motion
- Cash back only at select merchants, not on every purchase
- Any open Tilt cash advance or line of credit must be repaid and closed before you apply
Tilt considers each application for all three of its cards and makes you its best offer, so when that’s the Engage and you have no deposit to spare, it’s a reasonable way to build credit. Anyone who can set aside a refundable deposit should open a no-fee secured card instead.
Learn more about the Tilt Engage or see how it compares to the best unsecured credit cards for bad credit.

Subscribe and we'll send you 101 Essential Money Tips to get you started.
The 101 money moves that matter most, from the foundations to protecting what you’ve built.
Editorial Disclosure: The editorial content on this page is not provided, commissioned, reviewed, approved, or otherwise endorsed by any advertiser. Opinions expressed here are ours alone, not those of any advertiser. Compensation does not influence our editorial evaluations, ratings, or opinions.
Advertiser Disclosure: Many or all of the offers that appear on this site are from companies that compensate us, and some companies pay for sponsored content. That compensation may influence which products we cover and where and how they appear on a page, including the order in which they appear. We do not include every company or offer available in the marketplace.