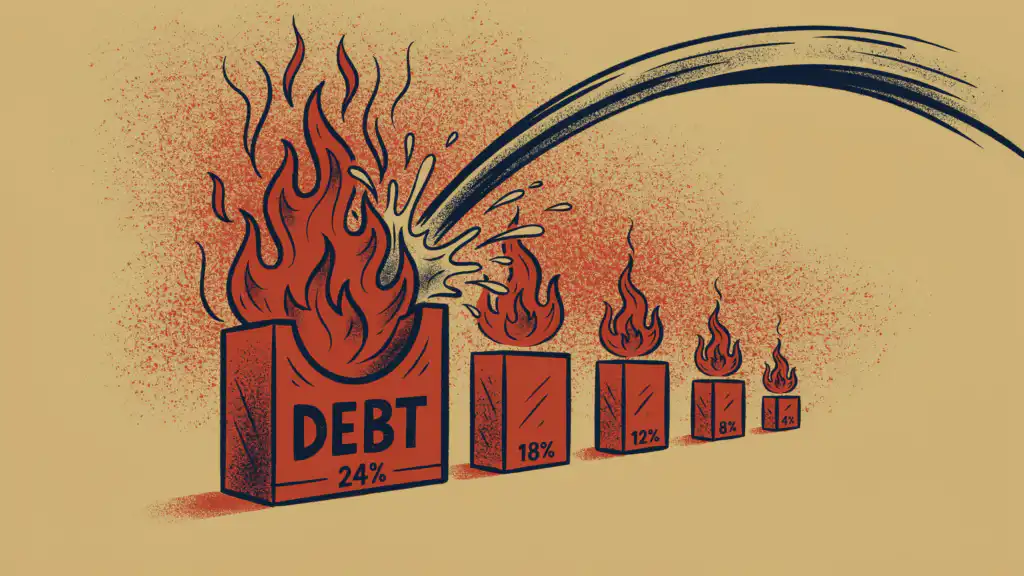

A debt consolidation loan saves you money only when its APR, the yearly rate with the origination fee counted, is lower than your cards’ rates. Stretching the term adds interest that can outweigh what the lower rate saves, so prequalify with several lenders and choose the shortest term with a payment close to what you pay now.
Keeping your payment where it is matters. The Consumer Financial Protection Bureau warns that a lower payment can simply mean a longer loan that costs a lot more overall.
The loan pays off your cards and leaves one monthly payment with a set end date, generally two to seven years out. Many lenders also charge an origination fee, typically 1% to 10% of the loan, and usually subtract it from the money you receive, so you’ll need to borrow enough to cover both your card balances and the fee.
Say you owe $15,000 at 24% and pay $524 a month, which clears the cards in about 43 months with roughly $7,500 in interest. A three-year loan at 12% interest with a 5% fee means borrowing about $15,800, and the fee lifts the APR to about 15.6%. At the same $524 a month, the loan is paid off in 36 months instead of 43. Its interest and fee come to about $3,900, roughly $3,600 less than the cards’ $7,500. Stretch that loan to seven years and the payment drops to about $279 and the APR to 13.7%, yet interest and the fee total about $8,400, about $900 more than the cards’ $7,500.
To check your own offers:
- Get prequalified rates from several lenders, usually through a soft credit check that doesn’t affect your score.
- Compare each offer’s APR, not its interest rate, with your cards’ rates, and rule out any that doesn’t beat them.
- Take the shortest term whose payment you can afford. If that term is longer than it would take to pay off your cards at your current payment, compare the total cost of each in a payoff calculator first.
If you could clear the debt within a 0% promotional period, a balance transfer card may cost less than a loan.
Running the cards back up leaves you with the loan plus new balances. The day the loan pays your cards off, take them out of your wallet and delete them from the stores and apps that save them.

Editorial & Advertiser Disclosure: The editorial content on this page is not provided, commissioned, reviewed, approved, or otherwise endorsed by any advertiser. Opinions expressed here are ours alone, not those of any advertiser. The offers that appear on this site are from companies that compensate us. That compensation may influence which products we cover and where and how they appear on a page – including the order in which they appear – but it does not influence our evaluations, ratings, or opinions. We do not include every company or offer available in the marketplace.
Related: