

An employer 401(k) match adds money to your account for every dollar you contribute, up to a cap, and it’s an instant return no investment can promise. Find the formula and check that your contribution rate reaches the cap, even if you were enrolled automatically, are paying off debt, or aren’t sure you’ll stay.
Being enrolled isn’t the same as collecting the full match. When a plan signs you up automatically, it picks your contribution rate. Vanguard’s 2026 How America Saves report found that nearly two-thirds of plans now start auto-enrolled workers at 4% or more, which leaves more than a third starting lower.
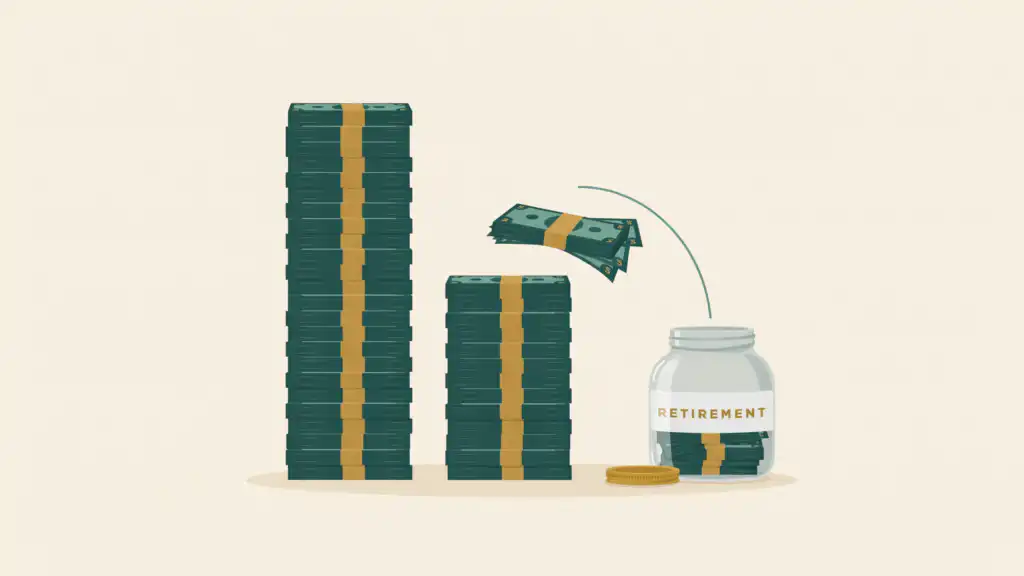
That gap matters because of how matches work. The most common formula on Fidelity’s plans matches every dollar you contribute up to 3% of your salary, then 50 cents per dollar on the next 2%. It takes 5% to collect all of it. On a $60,000 salary, 5% is $3,000, and your employer adds $2,400, an 80% gain before the market moves. Stay at 3% and you collect $1,800 and miss $600 a year.
The usual reasons to wait don’t hold up. Paying down a card that charges 24% interest saves you 24% a year. The match returns up to 100% the day it lands, so fund it first and send the rest to the debt. Vesting, the years some employers make you stay before the match is fully yours, isn’t a reason either. Your own contributions are always yours. Federal rules require matching money to vest fully within three years all at once or six years in steps, and leaving early costs you only the part not yet vested.
Find your formula in the plan’s summary plan description or benefits portal and set your rate at least to the cap. A traditional contribution comes out before income tax, so that $3,000 costs you less than $3,000 in take-home pay. If the full rate is too much at once, raise it a point now and turn on automatic yearly increases if your plan offers them. And if you’ll hit the annual limit early, ask HR about a true-up, a later deposit that covers match you’d miss once your contributions stop.
Then check your 401(k) account after the next payday and confirm the employer deposit equals what the formula promises.

Editorial & Advertiser Disclosure: The editorial content on this page is not provided, commissioned, reviewed, approved, or otherwise endorsed by any advertiser. Opinions expressed here are ours alone, not those of any advertiser. The offers that appear on this site are from companies that compensate us. That compensation may influence which products we cover and where and how they appear on a page – including the order in which they appear – but it does not influence our evaluations, ratings, or opinions. We do not include every company or offer available in the marketplace.
Related: