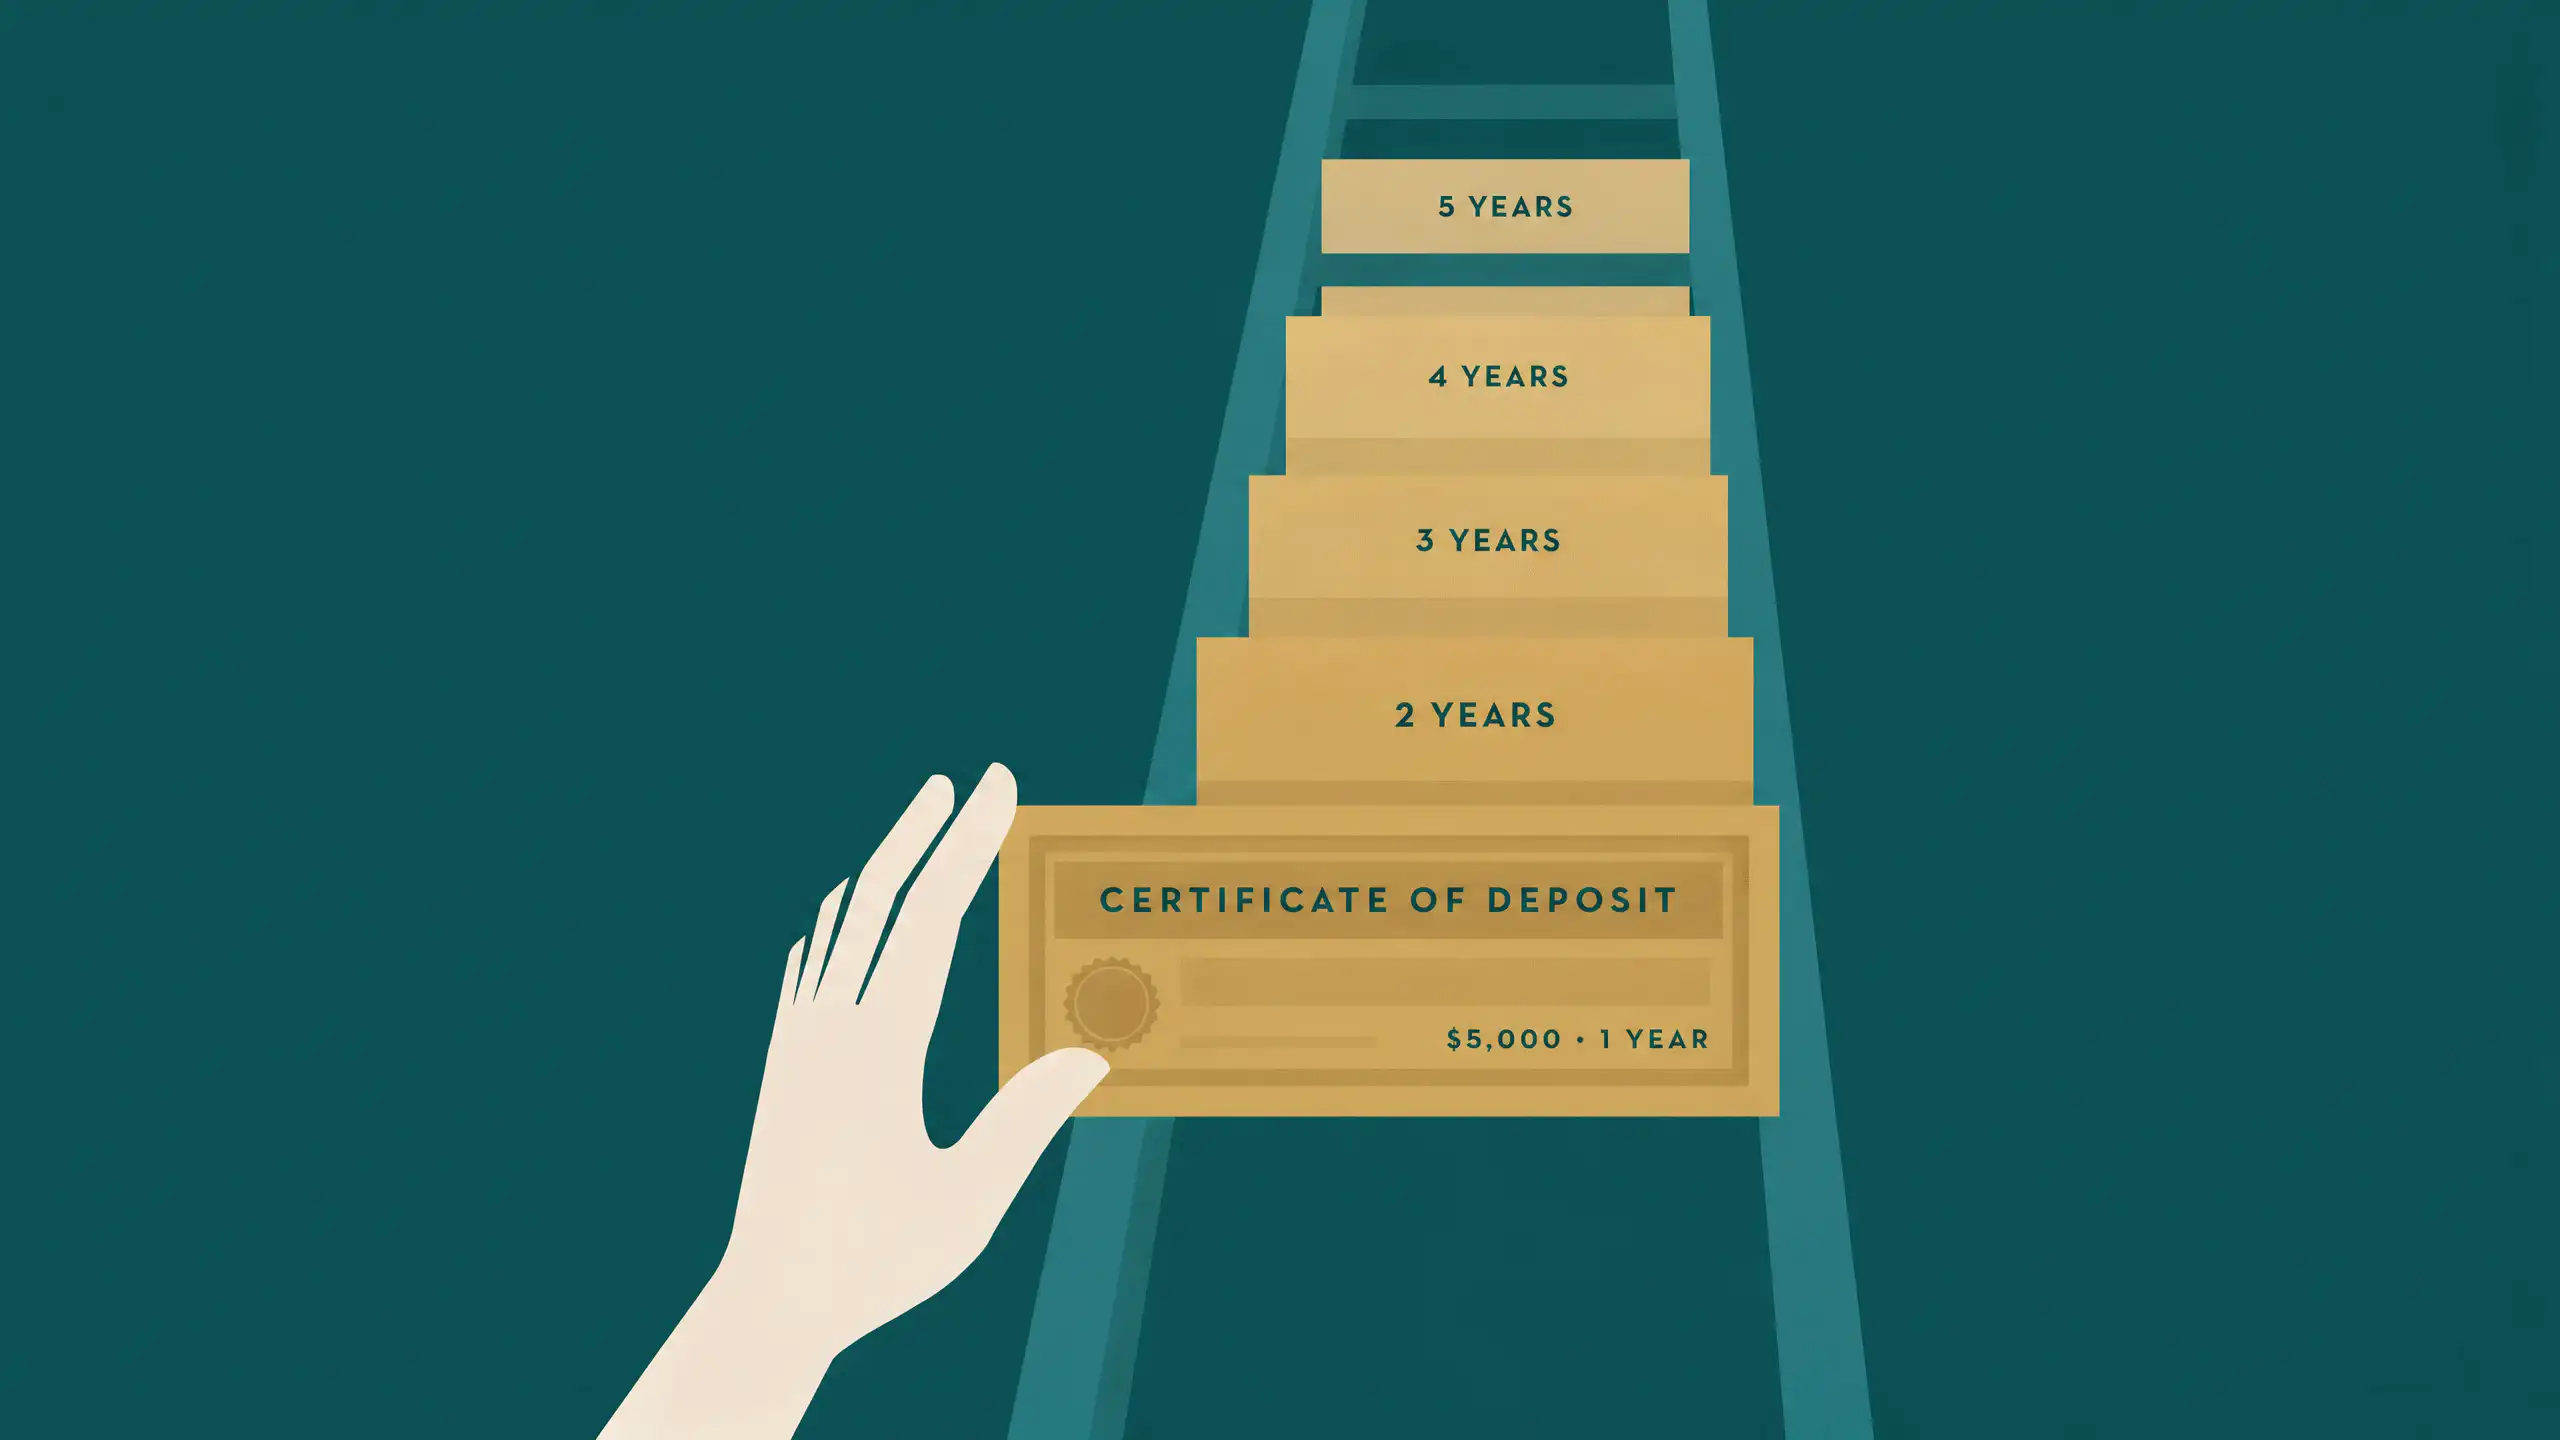

Split savings you won’t need all at once into four equal CDs maturing in 6, 12, 18, and 24 months, and renew each one as a two-year CD when it matures. After 18 months, your whole CD ladder earns two-year rates, and you can pull a quarter of it out penalty-free every six months.
A single two-year CD locks up every dollar until the term ends, and breaking it early triggers a penalty, typically 60 to 365 days of interest. At the steep end, that penalty on a $20,000 CD paying 4% is $800.
A CD ladder solves this by staggering when your money comes due. Put $20,000 into four $5,000 CDs maturing in 6, 12, 18, and 24 months. Each time one matures, reinvest it in a new two-year CD.
By month 18, all four rungs are two-year CDs opened six months apart. From then on, the whole $20,000 earns two-year rates and $5,000 comes due every six months. If you need cash between maturities, you break one rung and pay the penalty on $5,000, not $20,000.
Check the rate gap before you build it. Compare the best two-year CD rate with the best six-month CD and high-yield savings rates, starting with online banks such as CIT Bank and Ally Bank. The ladder is worth building when the two-year rate beats both the six-month CD rate and the savings rate. When it doesn’t, use whichever of the two pays more, since it earns at least as much as the ladder and locks your money up for less time.
Then handle each renewal yourself. Left alone, a maturing CD usually rolls into a new CD of the same term at the bank’s current rate, so your six-month rung would come back as another six-month CD. During the grace period, typically 7 to 10 days after maturity, tell the bank to renew it for 24 months instead. Miss that window and the rung is locked into a fresh term.
Put every maturity date on your calendar the day you open the ladder. After month 18, keeping it running takes two reminders a year.
Pick a bank for each rung from the best CD rates.


Subscribe and we'll send you 101 Essential Money Tips to get you started.
The 101 money moves that matter most, from the foundations to protecting what you’ve built.
Advertiser Disclosure: Many or all of the offers that appear on this site are from companies that compensate us, and some companies pay for sponsored content. That compensation may influence which products we cover and where and how they appear on a page, including the order in which they appear. We do not include every company or offer available in the marketplace.